


EN
Westgold Resources (ASX:WGX) Could Be 33% Undervalued After Beta Hunt Upgrades
Westgold Resources (ASX:WGX) is back in focus after confirming key infrastructure upgrades at its Beta Hunt underground mine, with September operations reaching an annualised 2Mtpa mining rate ahead of the interim ventilation system commissioning.
Recent news flow around the Beta Hunt upgrades has come against a mixed share price backdrop for Westgold Resources, with the stock up 3.8% on the day to A$4.97, yet down 9% over 30 days and almost 23% year to date.
Scan beyond Westgold Resources and see how other producers are positioned by running your filters across 35 elite gold producer stocks, aligned with your risk and return preferences.
After a sharp slide this year followed by a short-term bounce, Westgold Resources now poses a simple question: do the Beta Hunt upgrades and current A$4.97 share price still tilt the risk reward towards buyers?
Most Popular Narrative: 33% Undervalued
Against a last close of A$4.97, the most followed narrative on Westgold Resources anchors value closer to A$7.37, framing the Beta Hunt upgrades within a broader, funded production plan rather than a single mine story.
The integration of the Karora transaction has significantly increased Westgold Resources' production scale and operational flexibility, so higher throughputs and leverage to the gold price still have scope to influence revenue and earnings as the combined portfolio is run for a full cycle.
See why 54 investors see Westgold Resources as 33% undervalued.
Result: Fair Value of A$7.37 (UNDERVALUED)
Still, if all-in sustaining costs remain elevated or analyst revenue assumptions prove too optimistic, the Westgold Resources undervaluation story could easily lose momentum.
Find out about the key risks to this Westgold Resources narrative.
Another View: What Multiples Say About Westgold Resources
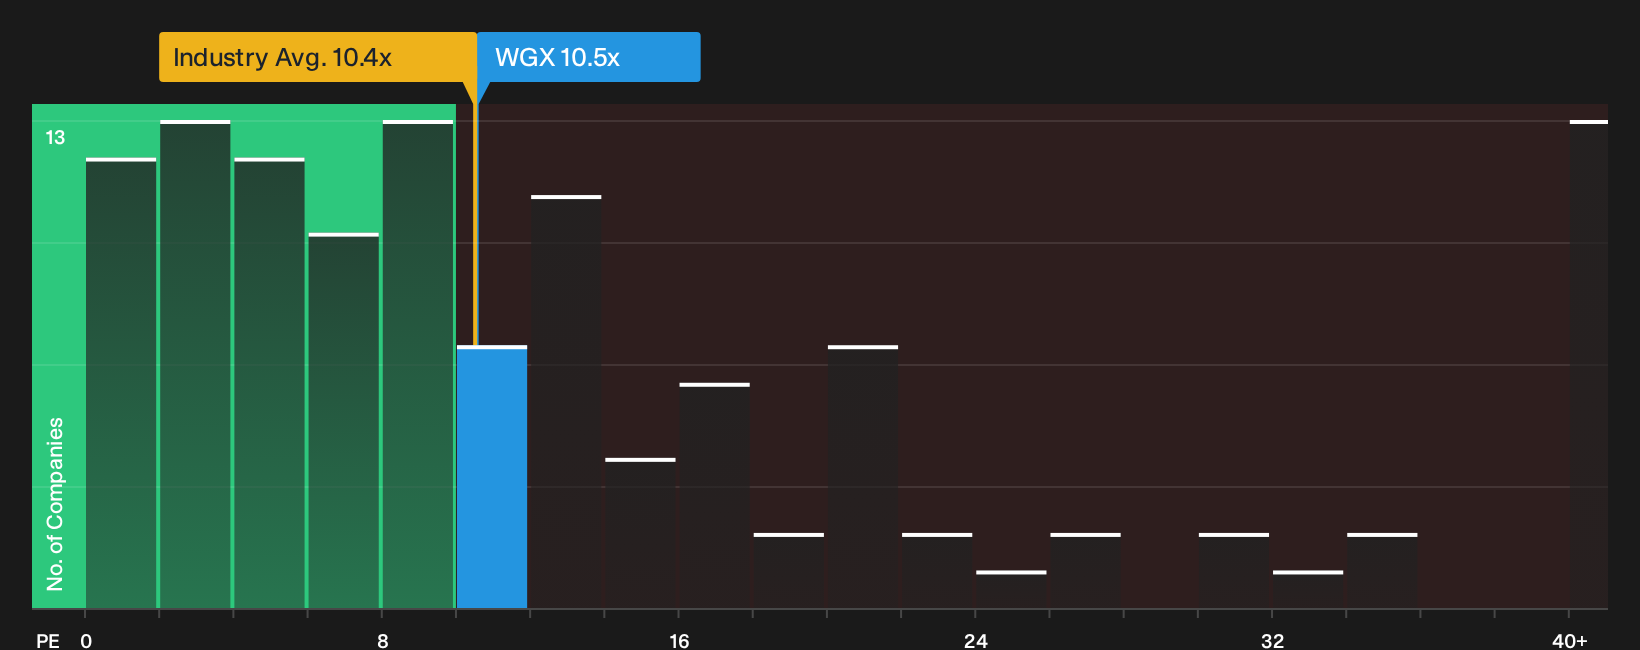
The first narrative leans heavily on analyst models and fair value estimates around A$7.37. A quick look at simple pricing math sends a different signal. Westgold Resources trades on a P/E of 10.5x, only a touch above the Australian metals and mining industry at 10.4x.
That small premium looks modest beside its peer average on 13.3x and an estimated fair ratio of 18.2x. For investors, that gap can either be seen as room for the valuation to catch up or as a sign that the market is already baking in execution risk. Which side of that interpretation do you sit on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of numbers in this Westgold Resources story point in different directions, so it pays to move fast and build your own judgment. To see which potential upsides are getting the most attention right now, start with the 4 key rewards.
Looking for more investment ideas beyond Westgold Resources?
Do not stop with Westgold Resources when the market is full of other potential opportunities that might fit your goals even better.
- Target stability first by screening for businesses with strong finances and durable balance sheets through the list of solid balance sheet and fundamentals (12 results).
- Hunt for potential mispriced opportunities by focusing on companies that score well on quality and valuation using the 2 high quality undervalued stocks.
- Build a watchlist around resilience by filtering for companies with lower risk profiles via the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com