


EN
Should Fertilizer Focus Require Action From SQM Investors?
- Sociedad Química y Minera de Chile is drawing attention as a key supplier of water soluble fertilizers and sustainable crop nutrition inputs, alongside its lithium and specialty chemical operations.
- The core tension is operational, with interest in SQM's fertilizer role and diversified portfolio set against questions about pricing power and long term margins as new lithium and specialty chemical supply comes onstream.
- We will look at how Sociedad Química y Minera de Chile's investment narrative is affected by rising focus on its positioning in water soluble fertilizers.
Scan beyond Sociedad Química y Minera de Chile and compare its fertilizer and materials story with a curated list of potential peers in the 34 best rare earth metal stocks.
Sociedad Química y Minera de Chile Investment Narrative Recap
To own Sociedad Química y Minera de Chile, you need to be comfortable with a business that still leans heavily on lithium while using fertilizers and iodine as ballast. The big picture is about whether lithium demand for EVs and storage can support planned capacity increases, while water soluble fertilizers and specialty plant nutrition help smooth earnings.
The recent 28% share price gain raises the bar for execution but does not change the main near term swing factor, which is lithium pricing versus rising volumes and payments to the Chilean state. The key risk remains that heavy multi year lithium CapEx collides with weaker prices, which could pressure returns and cash generation.
With no fresh company announcements tied directly to this move, the most relevant reference point is the existing lithium growth program. Management is committing about US$3b of spending from 2026 to 2028, plus a further US$3b planned for Salar Futuro, to secure more Chilean brine output and improved environmental metrics.
For you, that means the current share price strength sits against very tangible execution questions. Higher capacity in Chile and Australia could support more lithium sales, but only if projects such as Novandino Lithium, Mt Holland and Salar Futuro come in on time and on budget while unit costs and government payments remain manageable.
Sociedad Química y Minera de Chile’s current analyst script points to revenues of US$8.7b and earnings of US$2.3b by 2029, built on 8.8% yearly revenue growth and an earnings increase of about US$0.9b from US$1.4b today.
Uncover why Sociedad Química y Minera de Chile's fair value indicates a 45% potential upside to its current price that could narrow quickly.
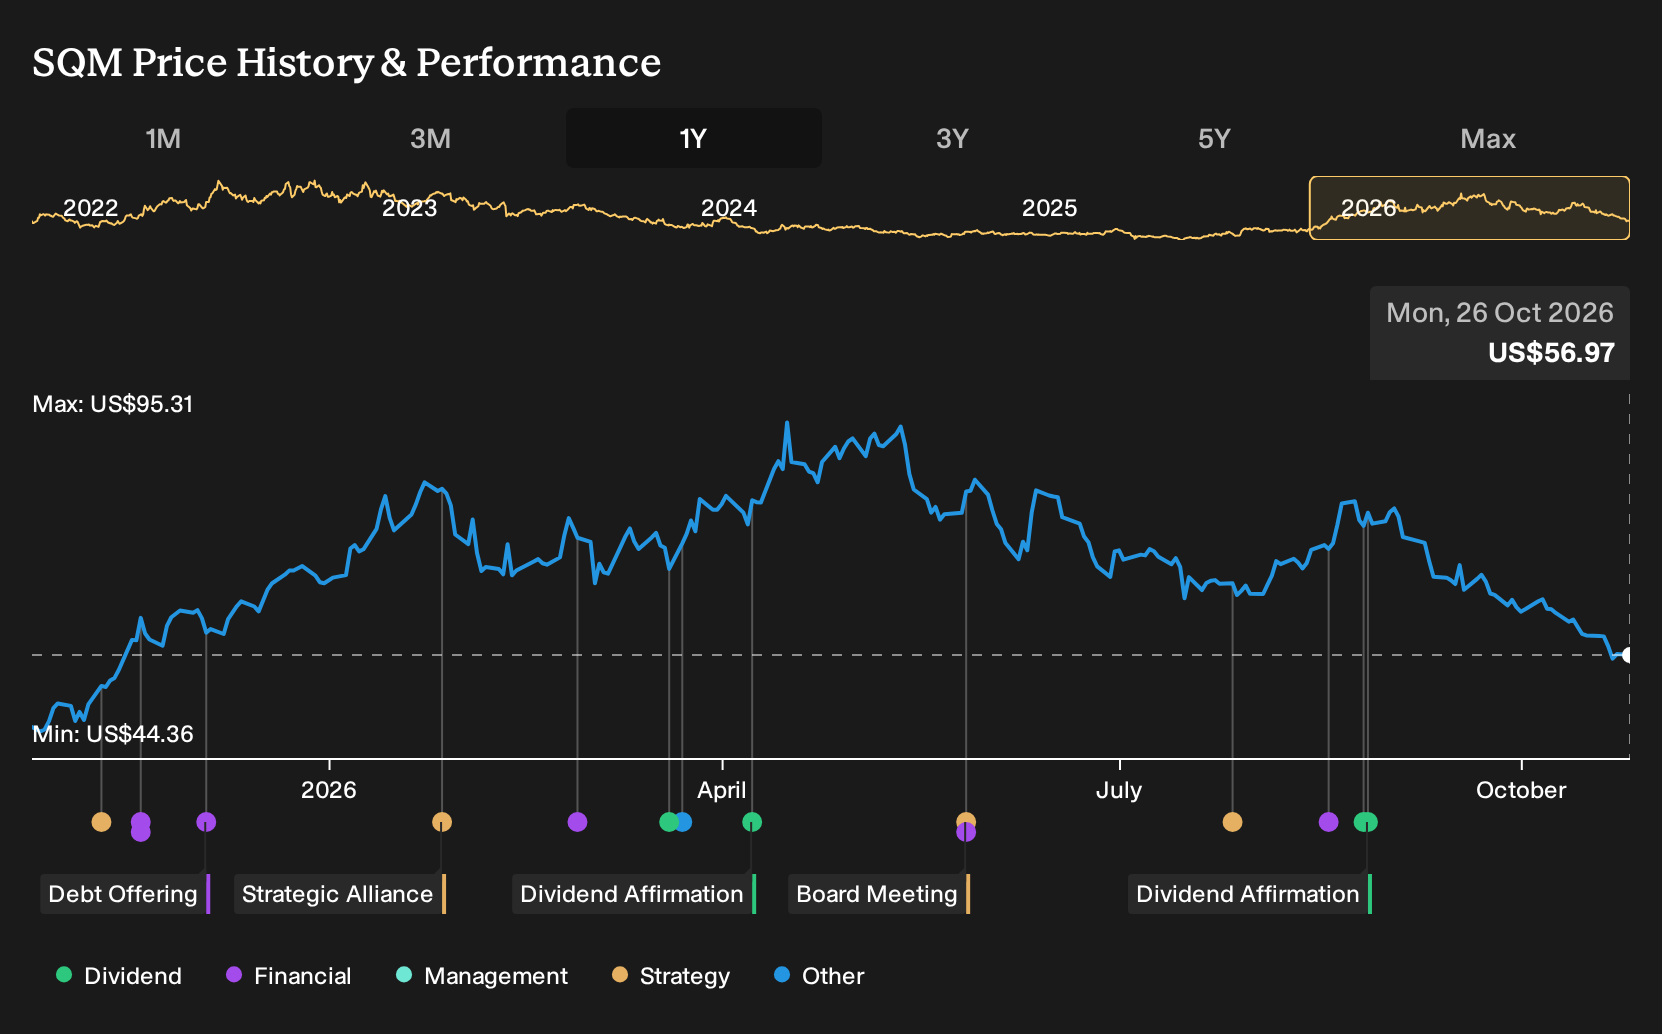
Exploring Other Perspectives
One alternate narrative leans on fertilizers as the real swing factor. In that more optimistic view, Sociedad Química y Minera de Chile could lean on specialty plant nutrition to support earnings, which the most bullish analysts had pegged at US$2.9b on US$10.0b of revenue by 2029 before this latest share price move. Opinions clearly vary, so treat this news as a cue to compare several scenarios for SQM’s future mix of lithium and crop nutrients.
Explore 4 other Sociedad Química y Minera de Chile fair value estimates, including one that suggests up to 107% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sociedad Química y Minera de Chile research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sociedad Química y Minera de Chile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sociedad Química y Minera de Chile's overall financial health at a glance.
Looking for more Sociedad Química y Minera de Chile style ideas?
If you want to round out your watchlist beyond Sociedad Química y Minera de Chile, the Simply Wall St Screener can help you quickly filter for different types of opportunities that match your risk tolerance and income goals.
- If capital preservation and steady businesses matter most to you, start with a 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For those hunting for quality at a reasonable entry point, take a look at a 28 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- Income focused investors can zero in on a 5 dividend fortresses that target reliable cash distributions alongside durable business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com