


EN
Why National Bank Holdings (NBHC) Is Getting Attention Today
National Bank Holdings (NBHC) is back in focus as it prepares to report earnings after Tuesday’s close, with investors watching closely after last quarter’s revenue and net interest income both fell short of expectations.
At around US$38.88, National Bank Holdings has seen its share price slip about 3.2% over the past month and about 8.8% over the last quarter. The year-to-date share price return of 2.6% and 1-year total shareholder return of 7.9% point to only modest momentum, while the 3-year total shareholder return of 39.0% suggests that investors may be reassessing growth prospects and risk after a strong earlier period.
Spot 28 high quality undervalued stocks that, like National Bank Holdings ahead of earnings, trade below intrinsic value estimates while investors wait to see if near term catalysts change the story.National Bank Holdings has grown into a solid regional lender, yet the recent share price slip puts a different question on your screen. Is this a quality franchise that is simply mispriced today, or fairly valued for a slower phase?
Most Popular Narrative: 16% Undervalued
Against the last close of $38.88, the most followed narrative pegs National Bank Holdings’ fair value closer to $46. This puts the current pullback in a different light for anyone weighing earnings, digital spend, and loan growth together.
The main thing that has to go right is that National Bank Holdings converts its loan growth, Vista integration, and digital investments like 2UniFi into durable, high quality earnings without eroding its conservative credit profile or near 4% net interest margin.
A net interest margin guided to remain near 4% in 2026, underpinned by deposit costs of 1.93% and total cost of funds of 2.01% in Q2 2026, gives National Bank Holdings room for core earnings resilience if it maintains its relationship driven, low cost deposit mix.
See why 4 investors see National Bank Holdings as 15% undervalued.
Result: Fair Value of $46 (UNDERVALUED)
Still, heavy exposure to trucking, agriculture and commercial real estate, plus early stage 2UniFi spending with limited revenue so far, could quickly challenge that view that the stock is 16% undervalued.
Find out about the key risks to this National Bank Holdings narrative.
Another View On National Bank Holdings’ Valuation
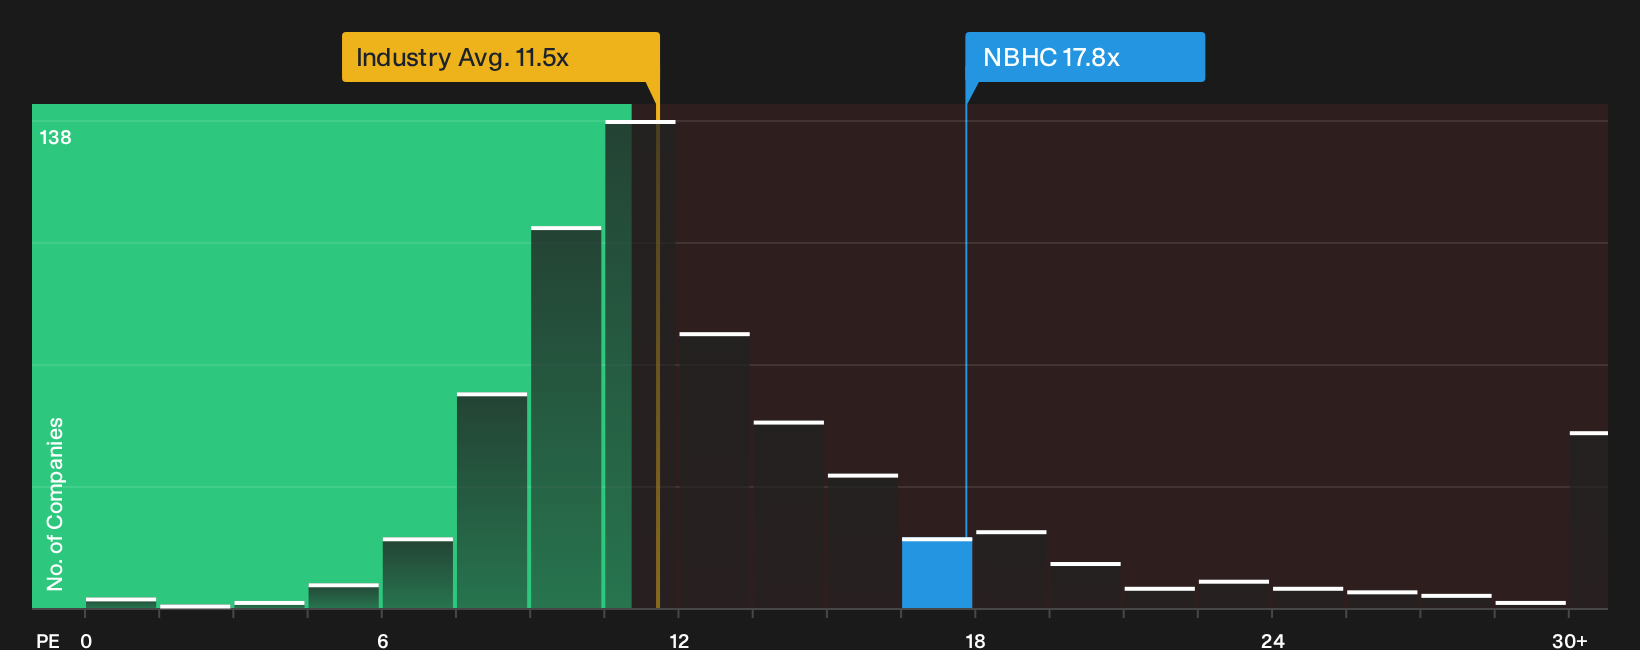
The story shifts once you look at National Bank Holdings through its P/E ratio instead of the narrative fair value. At 17.8x earnings, the stock trades richer than both US Banks at 11.5x and its peer group at 13.1x, and even above an estimated fair ratio of 16.1x. That richer tag suggests less room for error if the growth narrative wobbles. This raises the question of which signal to prioritize when the next earnings print lands.
For a closer look at how this pricing gap lines up with earnings quality, growth forecasts and returns, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around National Bank Holdings can either unsettle you or sharpen your edge. Move quickly, pull up the data, and evaluate both sides of the story against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond National Bank Holdings?
If you stop with National Bank Holdings, you risk missing other opportunities. Use the Simply Wall Street screener to uncover ideas that better match your goals and risk comfort.
- Target reliable income streams by focusing on companies that resemble dividend fortresses using the 5 dividend fortresses.
- Spot resilient businesses that aim to ride out rough patches more smoothly with the help of the 30 resilient stocks with low risk scores.
- Hunt for under the radar opportunities with strong fundamentals before the wider market catches on by scanning the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com