


EN
What Pilgrim's Pride Stock Means For Shareholders Ahead Of Third Quarter Results
- Pilgrim's Pride has already rolled out Pilgrim's FLAMIN' HOT Chicken Tenders and Bites in the frozen aisle, pairing the FLAMIN' HOT flavor with all white meat, no antibiotics ever, and air-fryer ready formats that target at-home snacking, mealtime, and game day occasions.
- The push into branded, higher protein frozen items aligns with Pilgrim's Pride's focus on prepared foods and adds another platform that could influence product mix and capacity use as the business reports its upcoming third quarter.
- We will now look at how Pilgrim's Pride's expanding FLAMIN' HOT frozen chicken lineup could shape its broader investment narrative.
Pilgrim's Pride Investment Narrative Recap
For Pilgrim's Pride, the investment case leans on a shift toward higher value prepared foods, better use of its new processing capacity, and steady demand for affordable protein across the U.S., Europe, and Mexico. The upcoming third quarter update on October 28 sits in the middle of that story, but the FLAMIN' HOT launch alone is unlikely to change the near term earnings picture.
The bigger swing factors are elsewhere. Elevated U.S. chicken supply can still pressure pricing. Mexico profitability fell sharply year on year, and any continued weakness there, combined with legal costs similar to the recent US$136 million settlement expense, could keep group margins and cash generation under strain.
The FLAMIN' HOT frozen chicken launch is the clearest recent example of Pilgrim's Pride leaning into branded, prepared products. It directly lines up with the push toward higher mix offerings that rely more on product positioning and less on commodity chicken pricing, and it plugs into air fryer at home consumption that retailers continue to feature.
For you as a shareholder, the interest in this launch sits in the execution details. Uptake of the tenders and bites will feed into prepared foods volumes and capacity utilization, which links back to the ongoing capex program. If the rollout scales smoothly, it could give the prepared portfolio more weight against pressures from U.S. oversupply, U.K. competition, and soybean cost volatility.
Pilgrim's Pride's current analyst narrative points to revenues of US$19.6b and earnings of US$854.6m by 2029, built on 2.1% yearly top line growth and an earnings increase of about US$309m from the US$545.6m reported today.
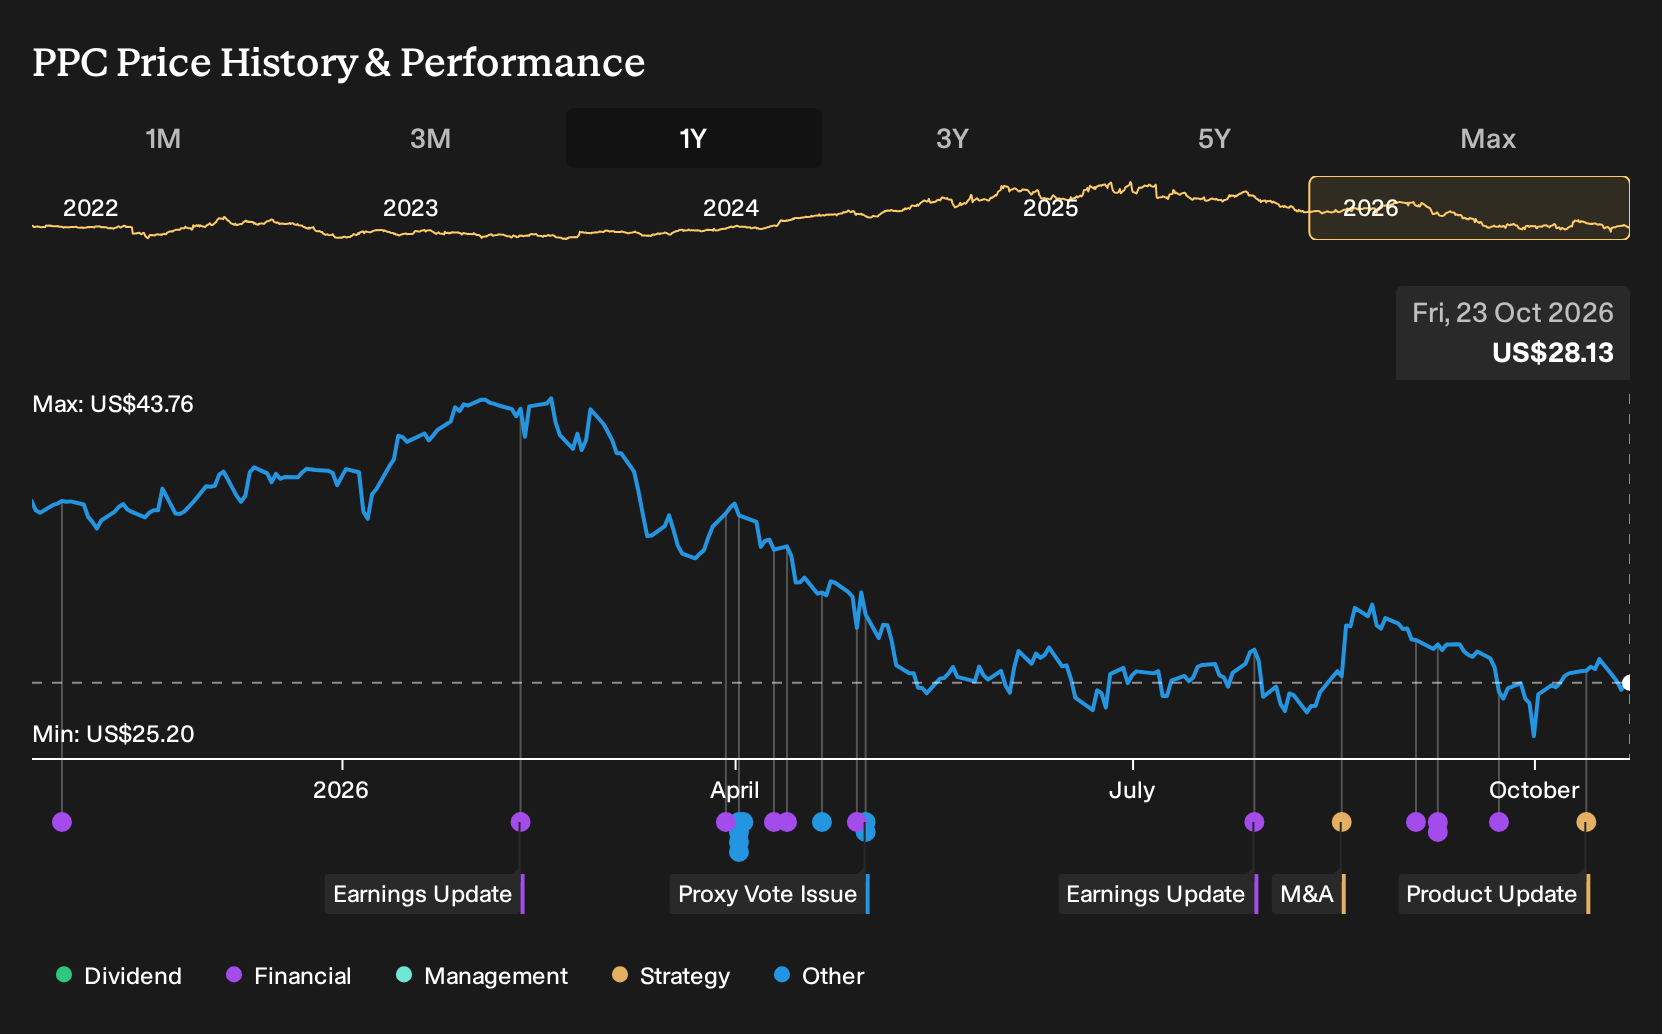
Uncover why Pilgrim's Pride's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans on Mexico risk rather than prepared foods opportunity. The most cautious Pilgrim's Pride analysts were only penciling in about US$19.3b of revenue and US$808.0m of earnings by 2029 before this FLAMIN' HOT frozen push, which is far below the bullish US$1.1b earnings camp. Use that gap as a prompt to explore both narratives yourself.
Explore 2 other Pilgrim's Pride fair value estimates, including one that suggests as much as 8% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pilgrim's Pride research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Pilgrim's Pride. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pilgrim's Pride's overall financial health at a glance.
Looking for more Pilgrim's Pride style investment ideas?
If Pilgrim's Pride has sharpened your interest in protein producers and packaged food businesses, it can help to widen the lens and line it up against other stocks that share similar traits in balance sheet strength, income potential, or valuation support.
The Simply Wall St Screener can surface a broader watchlist for you to research. A few curated filters that often appeal to readers looking at Pilgrim's Pride include:
- If you care most about resilient financial footing, start with companies that pass a tight balance sheet filter using this list of solid balance sheet and fundamentals (24 results).
- For investors who want income on top of potential price returns, consider screening for companies that match your yield and stability preferences through this 5 dividend fortresses.
- When valuation support matters most, focus on businesses that combine quality fundamentals with pricing that still looks appealing by running the 28 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com