


EN
MatsukiyoCocokara (TSE:3088) Draws Fresh Attention On Cash Flow Based Valuation
Event driven spotlight on MatsukiyoCocokara
Fresh valuation work has pushed MatsukiyoCocokara (TSE:3088) back into focus, as analysts highlight how its steady cash flows and recurring consumer demand can be used to anchor intrinsic value estimates that differ from the current share price.
Recent trading has leaned positive, with a 1-day share price return of 1.26% and a 30-day share price gain of 5.33%, yet the year to date share price is still down 2.10% and the 1-year total shareholder return has declined 5.87%. At the same time, the 5-year total shareholder return of 66.29% points to a much stronger long run. This helps explain why fresh valuation work on MatsukiyoCocokara is getting more attention as investors reassess whether the current ¥2,657 share price lines up with that longer track record.
Scan how MatsukiyoCocokara compares with other cash generative retailers that also screen as potential mispricings by reviewing our curated 16 high quality undervalued stocks.
After a solid 5 year run and a recent uptick, the question around MatsukiyoCocokara is simple: Is most of the value already realized, or do the cash flows still point to meaningful upside from here?
Price-to-Earnings of 18.1x: Is it justified?
MatsukiyoCocokara trades on a P/E of 18.1x while the wider JP Consumer Retailing group sits at 13.1x and the closest peer set at 16.2x. At a last close of ¥2,657, that puts the stock on a richer earnings tag than both its sector and its peer average.
P/E simply tells you how many yen investors are currently prepared to pay for each yen of profit. For a retailer built on recurring consumer demand and chain-store scale, this ratio is often used as a shorthand way to compare what the market is paying for earnings across similar businesses.
The current premium looks modest, not extreme, but it is still a premium. Earnings have grown by 14.3% per year over the past 5 years and by 3.1% in the last year, and forecasts point to 5.9% annual profit growth, which is slower than the wider JP market at 9.5%. With Return on Equity at 10.8%, which is assessed as low, the market is effectively paying more than the peer group for earnings that are not forecast to outpace the broader market.
The estimated fair P/E for MatsukiyoCocokara is 16.6x which is below the current 18.1x level. Compared with both the industry at 13.1x and this fair ratio at 16.6x, the pricing looks stretched rather than conservative, suggesting some room for the multiple to drift closer to that lower band if sentiment cools.
Explore the SWS fair ratio for MatsukiyoCocokara.
Result: Price-to-Earnings of 18.1x (OVERVALUED)
Still, two pressure points could flip the MatsukiyoCocokara story quickly: weaker earnings than expected relative to its 18.1x P/E, or softer consumer demand hitting cash generation.
Find out about the key risks to this MatsukiyoCocokara narrative.
Another view on MatsukiyoCocokara’s value
The P/E premium makes MatsukiyoCocokara look expensive, yet the SWS DCF model points the other way. On that cash flow view, an estimated fair value of ¥4,112.29 sits well above the current ¥2,657 price, which frames today’s quote as undervalued. Which signal do you trust more: earnings multiple or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
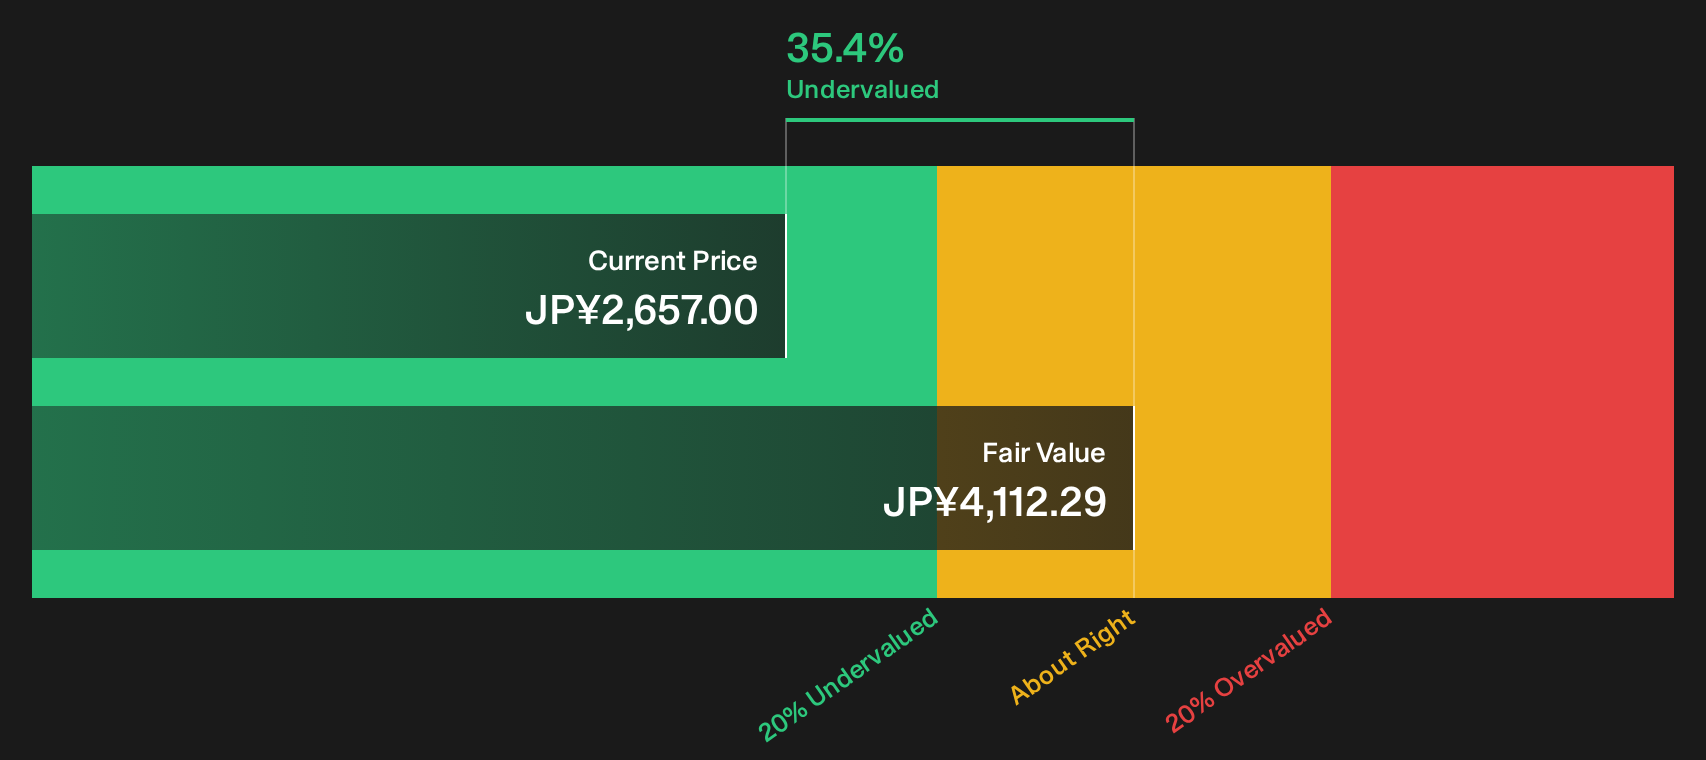
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MatsukiyoCocokara for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around MatsukiyoCocokara's valuation make this a judgment call rather than a headline takeaway. Consider moving quickly, reviewing the underlying metrics, and forming your own stance. To see what the optimistic crowd is focusing on, check the 4 key rewards.
Looking for more investment ideas beyond MatsukiyoCocokara?
If MatsukiyoCocokara has sharpened your focus on valuation and quality, do not stop here. Use targeted screeners to surface fresh opportunities that match your checklist.
- Spot potential mispricings early and review a curated 16 high quality undervalued stocks that already filter for quality alongside attractive pricing signals.
- Prioritise resilience by scanning a 22 resilient stocks with low risk scores that tilt toward steadier balance sheets and more consistent fundamentals.
- Hunt for future leaders before the crowd by using a 72 high quality undiscovered gems built around strong cash generation and solid financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com