


EN
Billerud (OM:BILL) Back In Profit On Q3 Earnings But Is The Recovery Fully Valued
Q3 earnings swing Billerud back to profit
Billerud (OM:BILL) is back in the black after its third quarter. The group reported SEK 10,166 million in sales and SEK 212 million in net income, supported by cost savings and stronger North American volumes.
Billerud’s earnings rebound arrives alongside a share price at SEK 86.6 and a 90 day share price return of 13.2%. However, the 1 year total shareholder return is roughly flat and the 5 year total shareholder return has declined 37.6%, which points to improving short term momentum after a tough longer stretch.
Compare Billerud’s turnaround with other packaging and materials players by scanning our hand picked 194 high quality undervalued stocks, which pair stronger balance sheets with more attractive valuations.
Billerud has returned to profit and the share price has already reacted. The key issue now is whether the current valuation still offers sufficient potential to compensate for the recent risks you have observed.
Most Popular Narrative: 10% Overvalued
Billerud’s most followed narrative places fair value at SEK 78.83, which sits below the latest close at SEK 86.6 and frames the recent rebound against a slightly richer share price.
The accelerating demand for sustainable packaging, driven by both consumer expectations and stricter regulations on single-use plastics, is positioning Billerud's expanding U.S. paperboard capacity (via its Evolution project and retooling of Verso assets) to capture new addressable markets and premium segments, supporting future revenue growth. Strong and growing customer interest in the North American market for domestically produced, high-quality fiber-based packaging is leading to long-term customer relationships and recurring contracts, which should improve both revenue visibility and margin stability over the coming years.
See why 10 investors see Billerud as 10% overvalued.
Result: Fair Value of SEK78.83 (OVERVALUED)
Still, persistent weak demand in Europe and execution risk around the Evolution program in North America could quickly challenge the current Billerud recovery narrative.
Find out about the key risks to this Billerud narrative.
Another View on Billerud’s Valuation
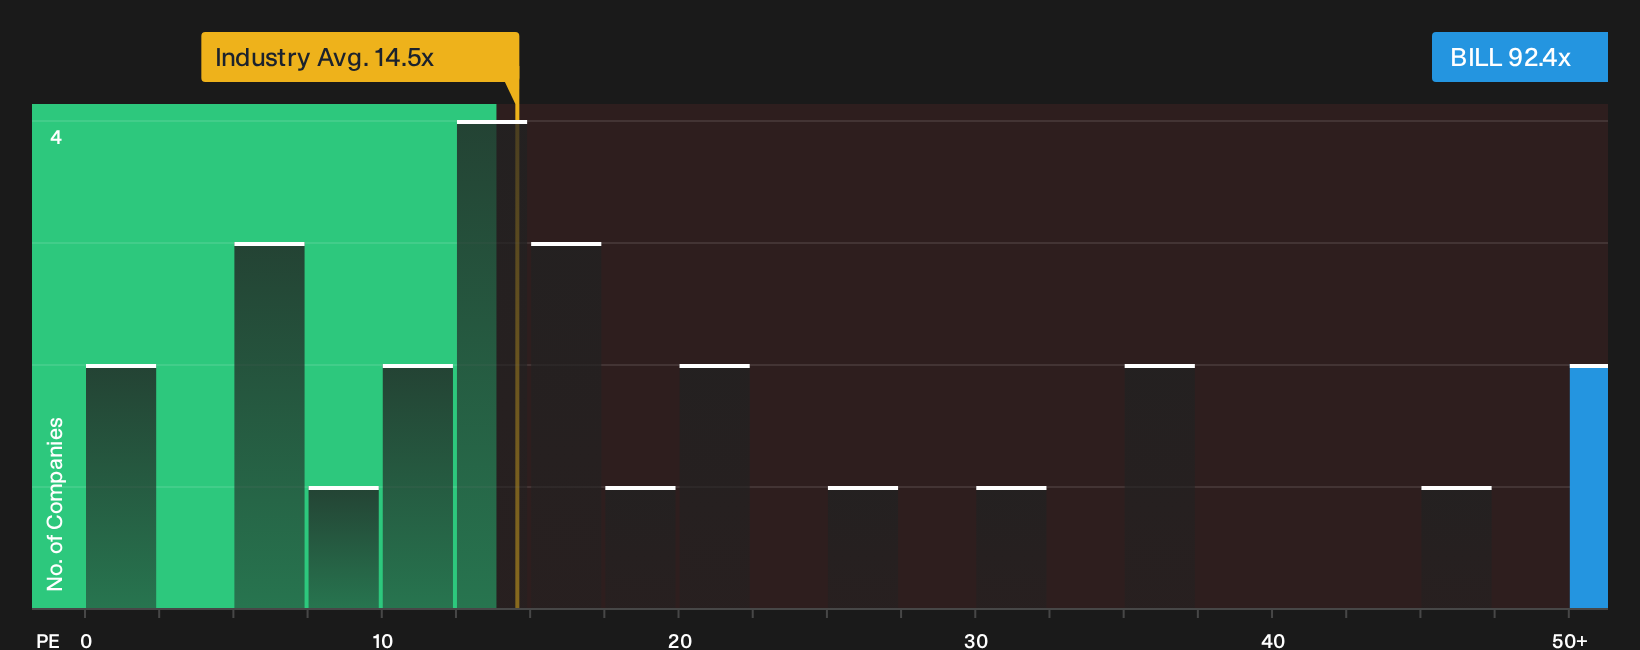
The market is treating Billerud very differently to that 10% overvalued fair value narrative. At SEK 86.6, the stock trades on a P/E of 92.4x, which is far above the 63.9x fair ratio, the 14.5x Global Packaging industry average, and the 21.6x peer group level.
Such a wide gap suggests investors are paying a heavy premium for future earnings, which raises the risk that even small setbacks could hit the share price harder than for rivals. Is that premium something you are comfortable underwriting based on your own expectations for Billerud?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Billerud for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Billerud’s valuation and sentiment can be hard to interpret, so move quickly from headline takes to your own judgment. Start with the 2 key rewards and 2 important warning signs.
Looking for more Billerud alternative ideas?
If Billerud has sharpened your focus on valuation and quality, do not stop here. Broader opportunities often sit just outside the obvious watchlist.
Use the Simply Wall Street Screener to stress test your thinking and spot ideas that fit your own risk, return, and income preferences before the crowd catches on.
- Target stability and capital preservation by reviewing a 223 resilient stocks with low risk scores that filters for businesses with more resilient profiles.
- Pursue quality at a fair price by scanning a 610 high quality undiscovered gems that surfaces underfollowed companies with stronger fundamentals.
- Strengthen capital protection by working through a list of solid balance sheet and fundamentals (207 results) that highlights businesses with healthier leverage and liquidity metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com