


EN
How Stronger Earnings Will Impact Lakeland Financial Stock Investors
- Lakeland Financial reported third quarter 2026 net interest income of US$60.72 million and net income of US$28.86 million, alongside US$2.97 million of net charge offs tied largely to one previously reserved commercial credit.
- The bank’s willingness to recognize a sizeable charge on a single nonperforming commercial loan, while still reporting higher earnings, gives you a clear view of how Lakeland Financial is balancing credit clean up with income generation.
- We will look at how Lakeland Financial's investment narrative is shaped by higher earnings alongside the spike in net charge offs.
Compare how Lakeland Financial handles credit clean up and earnings power with other regional banks by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that keep problem loans in check.
What Is Lakeland Financial's Investment Narrative?
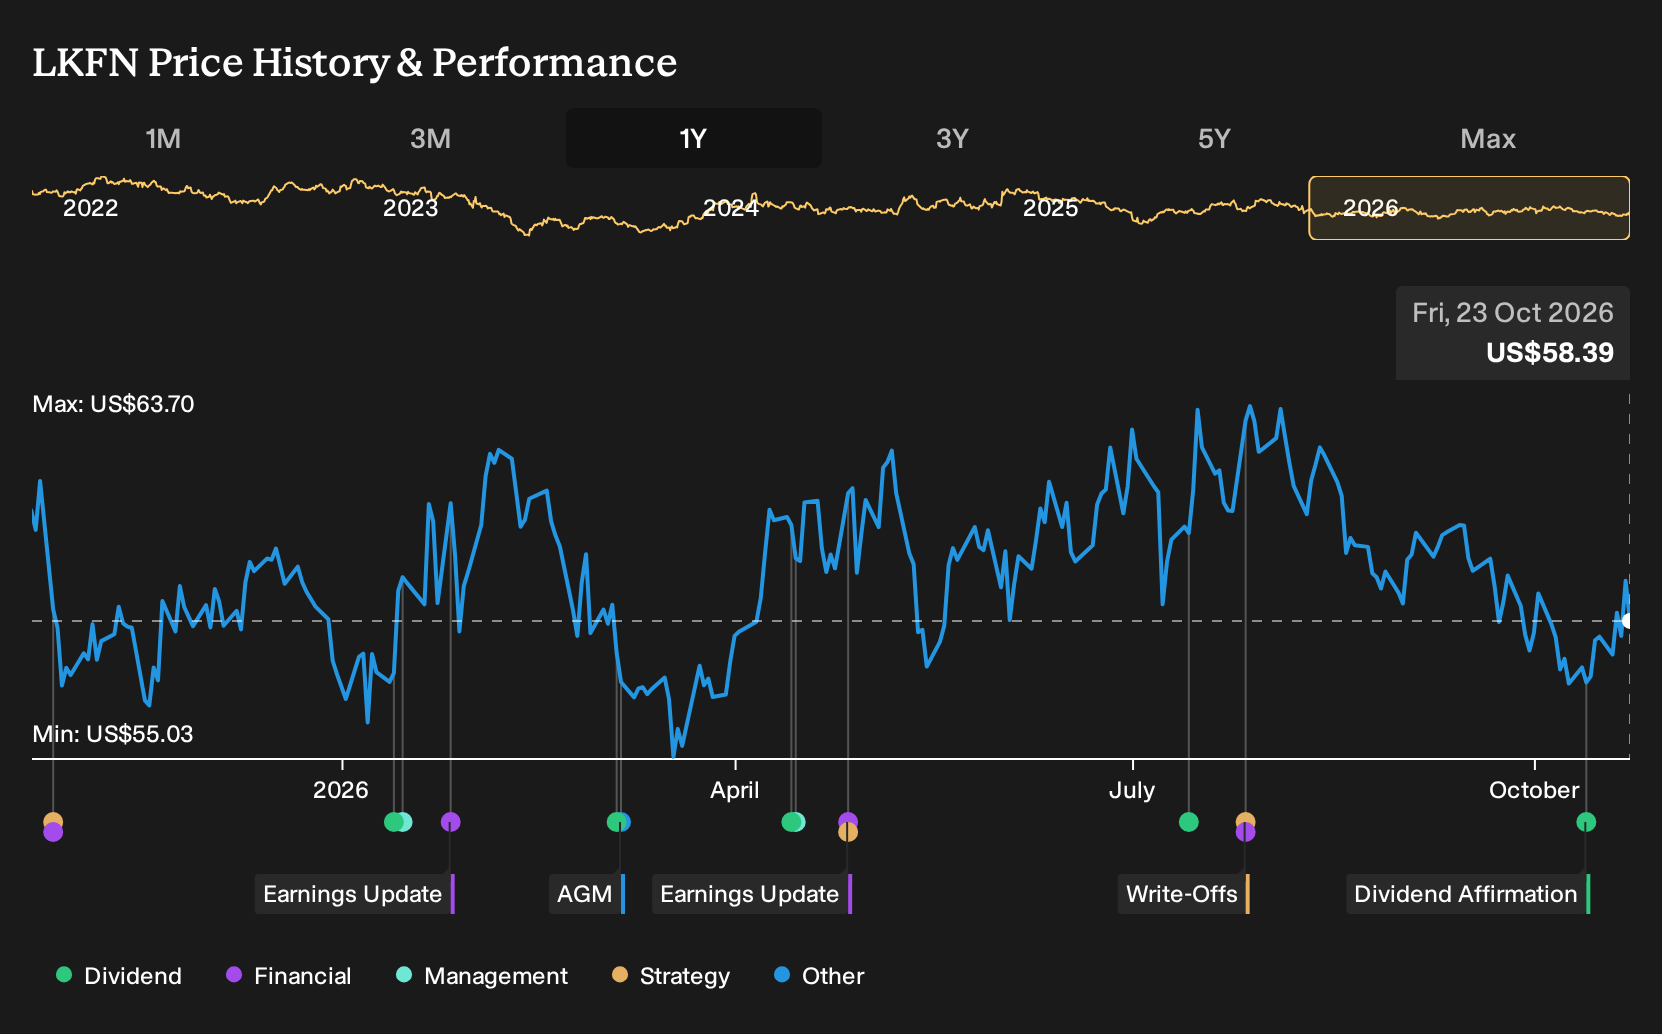
The basic belief behind Lakeland Financial is pretty simple. You are backing a regional bank that leans on steady net interest income, high quality earnings and a long operating history in one market. Recent results support that story. Net interest income of US$60.72 million and net income of US$28.86 million for the third quarter, along with full year to date profitability, point to a franchise that still earns solid returns without aggressive capital spending.
The twist this quarter is credit. Net charge offs climbed to US$2.97 million, with US$2.8 million tied to a single nonperforming commercial credit that had already been fully reserved. That kind of clean up affects reported results in the short term but does not fundamentally change the earnings drivers if new problem loans stay contained. For now, the bigger swing factors remain loan demand, deposit pricing pressure and management discipline on dividends and capital deployment.
Yet there is a less obvious pressure point around Lakeland Financial that could matter far more than this single charged off loan.
There's only one way to know the right time to buy, sell or hold Lakeland Financial. Head to Simply Wall St's company report for the latest analysis of Lakeland Financial's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lakeland Financial research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Lakeland Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lakeland Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lakeland Financial?
If you want to pressure test your thesis on Lakeland Financial, it can help to line it up against other opportunities that share similar qualities or offer something very different. The Simply Wall St Screener lets you do that side by side so you can see where this bank fits in your wider watchlist.
- If you prefer stronger balance sheets and cleaner credit profiles, compare Lakeland Financial with a 30 resilient stocks with low risk scores that may offer a smoother ride through different parts of the cycle.
- For investors hunting for quality at a reasonable price, line up Lakeland Financial next to a 28 high quality undervalued stocks that meet strict fundamental checks.
- If you want to broaden your universe beyond the usual tickers, scan a 21 high quality undiscovered gems that pair solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com