


EN
How Investors Are Reacting To Takashimaya (TSE:8233) Raised Dividend Forecast
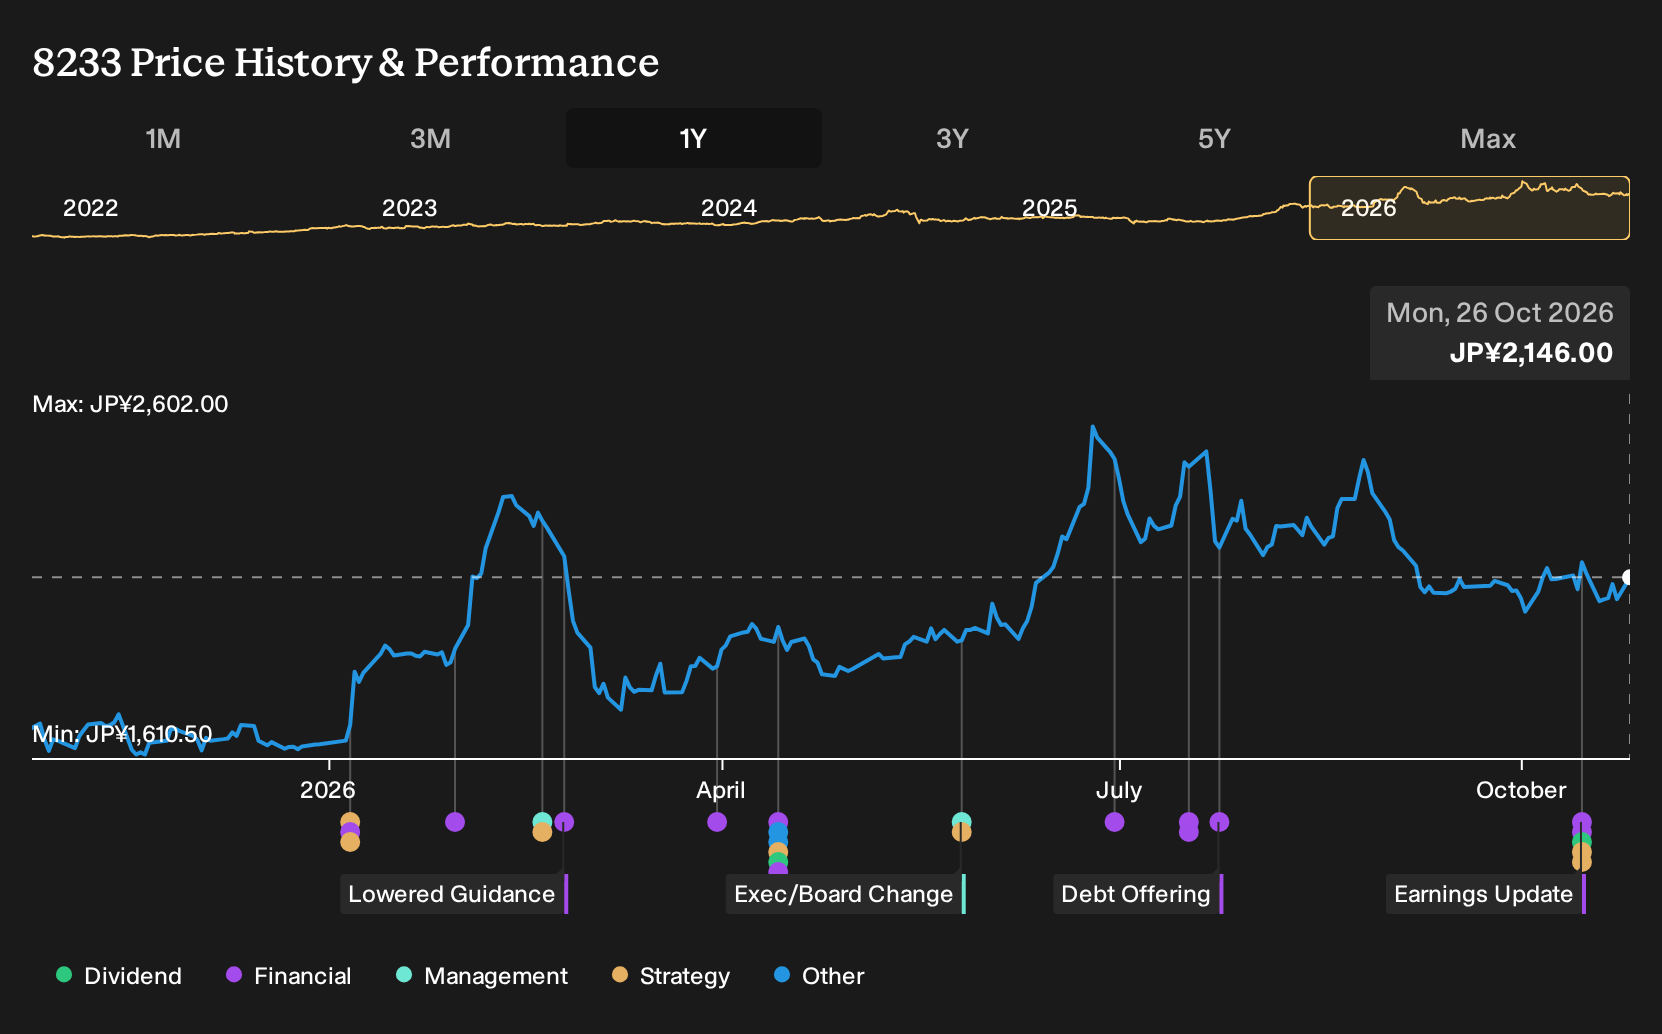
- Takashimaya Company reported September 2026 sales growth of 2.2% year on year and half year net income of JPY 16,014 million, alongside higher full year earnings and dividend guidance and plans to create Takashimaya Financial Holdings to oversee its Finance segment from March 2027.
- The mix of steady sales data, a larger planned dividend payout and a new financial holding structure indicates management focus on monetizing financial services and tightening risk control around that part of the business.
- This article will now look at how Takashimaya's investment narrative could be influenced by its higher dividend guidance and finance reorganization.
Scan how Takashimaya Company's dividend move and finance reshuffle compare with other income ideas by reviewing our hand-picked 29 dividend fortresses that are built around stronger yield profiles.
What Is Takashimaya Company's Investment Narrative?
To own Takashimaya Company, you have to believe this mix of traditional retail, property and finance can turn steady activity into cleaner profitability. September sales growth of 2.2% year on year and half year net income of ¥16,014 million point to a business that is at least keeping demand ticking, while the creation of Takashimaya Financial Holdings signals an attempt to tighten execution and governance around a more complex Finance segment.
In the short term, the key swing factors stay familiar. Department store traffic and pricing power, the capital demands of commercial development, and the cost of funding all still matter more than any single month of sales. The higher dividend guidance and interim payout of ¥22 per share indicate confidence, although past data show that dividends are not comfortably covered by earnings, so reinvestment capacity and loss making status remain central questions for the story.
There is one structural issue tied to how Takashimaya funds itself that could change the risk profile if...
There's only one way to know the right time to buy, sell or hold Takashimaya Company. Head to Simply Wall St's company report for the latest analysis of Takashimaya Company's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Takashimaya Company research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Takashimaya Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takashimaya Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Takashimaya Company?
If Takashimaya Company has put income, quality and risk on your radar, use that same checklist across a wider watchlist by running a few focused screeners before you make your next move.
- For investors who want income to feel more durable, weigh Takashimaya's payout against a curated set of potential 29 dividend fortresses that filter for stronger yield characteristics.
- If value is the priority, compare Takashimaya Company with a hand picked pool of 16 high quality undervalued stocks that pair solid fundamentals with a price that screens as cheap on multiple metrics.
- When capital preservation ranks higher than excitement, set Takashimaya alongside a universe of 22 resilient stocks with low risk scores where balance sheets and risk scores take center stage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com