


EN
Trinity Industries (TRN) Reshapes Railcar Financing, Is The Stock Cheap Now?
Trinity Industries (TRN) has revised a portion of its railcar leasing finances, as indirect subsidiary Trinity Rail Leasing 2026 LLC closed a US$349.8 million term loan secured by a dedicated railcar portfolio.
At a share price of US$25.54, Trinity Industries has seen the 90-day share price return fall 32.91%, even though the 3-year total shareholder return is up 38.54%. This suggests that recent weakness is following a stronger multi-year run.
Scan other rail and industrial leasing plays that are moving on balance sheet quality and capital structure, starting with our curated list of list of solid balance sheet and fundamentals (24 results)
Trinity Industries now pairs a reshaped railcar financing structure with a share price that has pulled back hard in recent months. Does that set up a reasonable entry today, or does patience still offer better odds?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Trinity Industries screens as undervalued, with a fair value of $31 against a last close of $25.54. That gap sits on top of a business where analysts are already factoring in falling earnings and slimmer margins.
Ongoing portfolio management actions such as railcar sales and partnership restructurings, including large non cash gains from recent transactions and management’s estimate that the owned fleet is worth 35% to 45% above carrying value, give Trinity Industries multiple ways to convert embedded asset value into gains, cash flow, and potentially higher earnings.
See why 2 investors see Trinity Industries as 18% undervalued.
Result: Fair Value of $31 (UNDERVALUED)
Still, the narrative around Trinity Industries can unravel quickly if cyclical customers pull back on orders or if portfolio gains dry up and leave earnings more exposed.
Find out about the key risks to this Trinity Industries narrative.
Another View on Trinity Industries’ Valuation
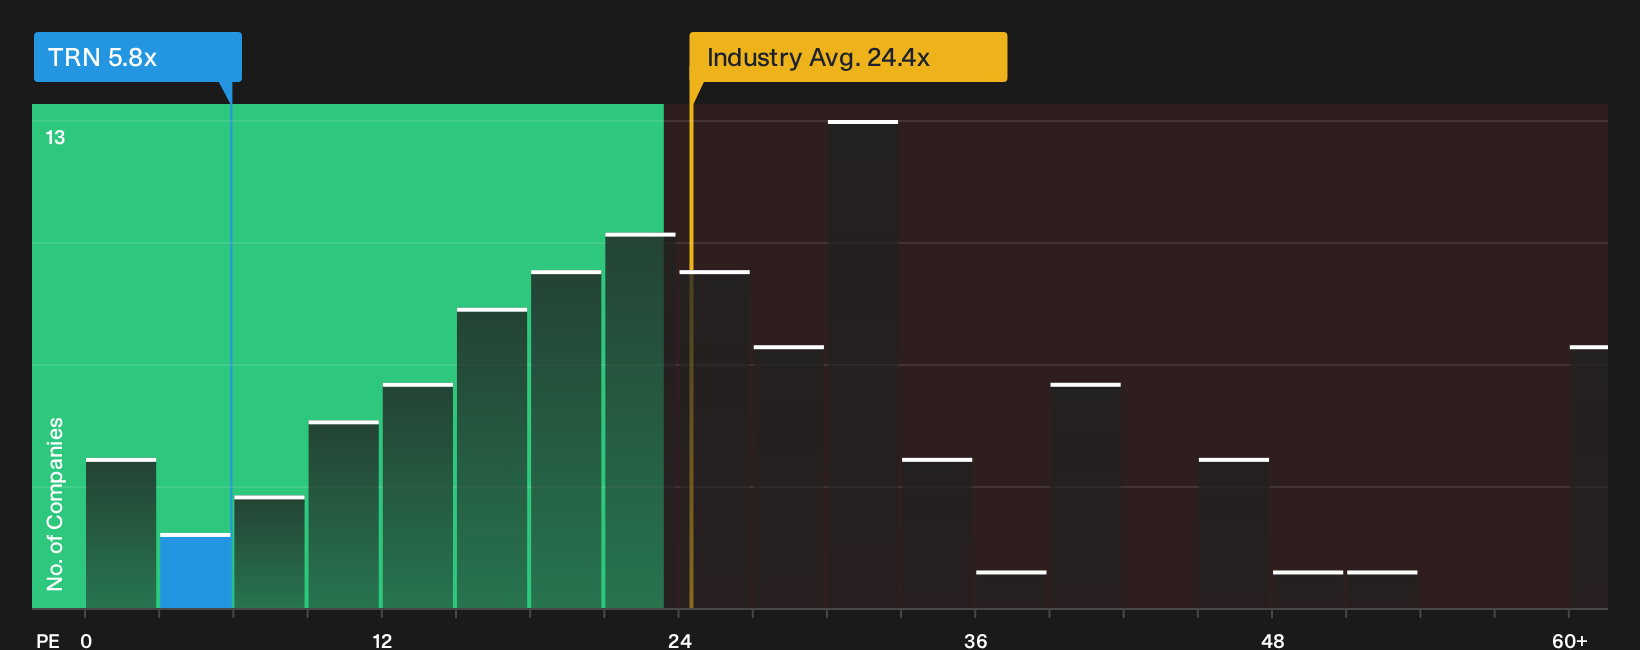
On a simple earnings multiple, Trinity Industries looks inexpensive. The P/E of 5.8x sits well below the US market at 18.4x and the US Machinery group at 24.4x. Yet it is slightly above the fair ratio of 5.1x, which points to some valuation risk if sentiment cools.
If you lean more on earnings multiples than on narrative fair value estimates, it is worth seeing what the numbers imply in detail through our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Trinity Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Trinity Industries is mixed, with clear risks on one side and genuine upside arguments on the other, so move fast and study the details yourself. To weigh that balance in a structured way, start with the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Trinity Industries?
Do not stop with Trinity Industries. Give yourself options by lining up a few more ideas that fit clear, disciplined criteria using the Simply Wall Street Screener.
- Target potential bargains early by scanning a curated pool of underpriced quality stocks with the 28 high quality undervalued stocks.
- Prioritise resilience by focusing on companies that pair sturdy finances with lower risk profiles through the 30 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd notices by working through a focused set of under-the-radar opportunities using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com