


EN
Did Full Year Earnings Just Shift Softcat's (LSE:SCT) Investment Narrative?
- Softcat reported full year 2026 results for the period to 31 July, with sales of £1,975.1m and net income of £150.3m, alongside higher basic and diluted earnings per share than a year earlier.
- The earnings update put extra focus on Softcat Intelligence and US expansion plans, as management highlighted AI driven services and overseas growth as key factors for future profitability and software margin mix.
- We will now look at how Softcat’s investment narrative is shaped by these AI focused earnings and the planned US expansion.
Compare Softcat's AI driven story with other potential beneficiaries of the same trend by scanning our hand picked 55 AI infrastructure stocks that could also be positioned for major enterprise demand shifts.
Softcat Investment Narrative Recap
To own Softcat, you need to buy into a simple idea. The group wants to turn its UK IT reseller base and Softcat Intelligence into an AI infrastructure and services specialist that can scale with larger enterprise budgets. The latest full year results back up that direction, with higher sales, net income and earnings per share giving management more room to keep funding AI tools and new systems.
The near term swing factor is whether AI related projects and US customers arrive quickly enough to offset pressure on software gross margins and higher system implementation spending. The biggest risk is that GDT’s hardware heavy mix and concentrated client base dilute profitability, while the new finance, sales and HR platforms keep costs high without the hoped for efficiency gains.
The most relevant recent development is Softcat’s full year report to 31 July 2026. Sales of £1,975.1m and net income of £150.3m show the group already operating at meaningful scale before GDT and deeper AI adoption fully come through. Higher basic and diluted earnings per share also give Softcat more financial flexibility to absorb integration and system expenses.
For catalysts, that earnings print connects directly to the GDT acquisition plan and the AI infrastructure push flagged on the earnings call and at events such as Microsoft’s Quarterly Tech Review. A revenue base close to £2.0b, plus existing AI consultancy from Oakland, means any US contribution or AI capable infrastructure demand has a larger operational platform to influence, but also raises the stakes if US customer concentration or softer software margins start to bite.
Softcat AI Growth Assumptions and Analyst Targets
Analysts are effectively treating Softcat as an AI infrastructure and services play that needs to grow into its US ambitions. Their models point to revenue rising at 17.1% per year over the next three years, with profit margins easing from 8.1% today toward 7.3% as system upgrades and GDT integration costs run through the income statement. On earnings, the consensus view looks for profit of £204.6m by 2029 compared with £141.1m today. This implies an increase of about £63.5m over that period.
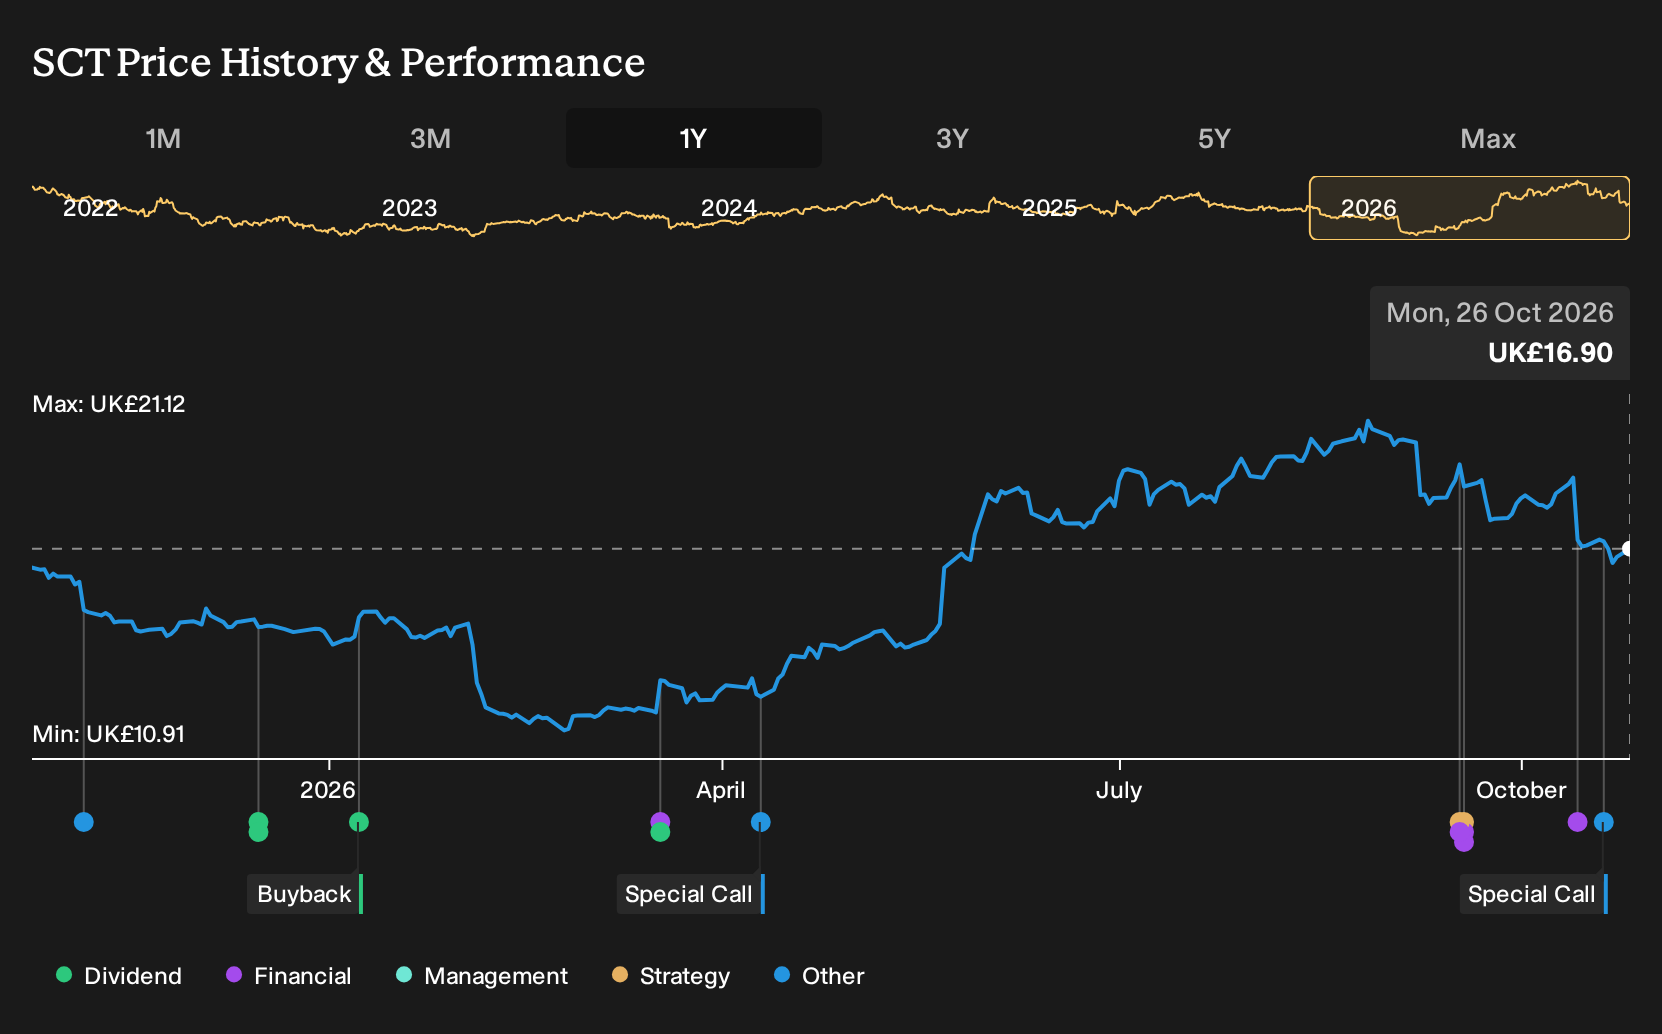
Those same forecasts sit behind a cluster of price targets. The current analyst range runs from £17.0 to £25.0, with a central target of £21.51 against a share price of £17.19 as of the latest report. To align with that central view, you would need to assume Softcat generates about £2.8b of revenue and £204.6m of earnings in 2029 and trades on a P/E of 27.9x, slightly below the 29.9x level cited for the wider UK IT sector. The focus then becomes whether AI related infrastructure demand and the GDT and Oakland contributions justify those revenue and profit levels, given the margin and customer concentration trade offs already flagged by management.
Softcat's current analyst narrative points to forecast revenue of about £2.8b and consensus earnings of £204.6m by 2029, built on an assumed 17.1% annual top line growth rate and an earnings uplift of roughly £63.5m from £141.1m today.
Uncover why Softcat's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view fixates on GDT’s concentrated U.S. client list as the key risk for Softcat, rather than the AI opportunity that dominated the recent earnings call and Microsoft tech review. The most cautious analysts once pencilled in 2029 revenue of about £3.6b and earnings of £189.8m. That supports a £17.0 price target and a 23.8x P/E, implying you should treat the latest updates as a fresh reason to compare several pre news forecasts rather than anchor to a single story.
Explore 3 other Softcat fair value estimates, including one that suggests it could be worth just £17.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Softcat research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Softcat. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Softcat's overall financial health at a glance.
Looking For More Ideas Beyond Softcat?
If Softcat has sharpened your view on AI infrastructure and earnings quality, it can be useful to set it alongside other businesses with very different risk and return profiles. The Simply Wall St Screener lets you do that quickly by filtering for traits that match how you like to invest.
- If capital preservation is high on your list, start with resilient companies that aim to limit downside risk through solid fundamentals by scanning 4 resilient stocks with low risk scores.
- If you prefer income on top of potential capital gains, check out reliable payers offering higher yields through the 5 dividend fortresses.
- If you want ideas that the market may not be paying close attention to yet, broaden your watchlist with under the radar opportunities using the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com