


EN
How Low P S Valuation Will Impact North Atlantic Energies Stock Investors
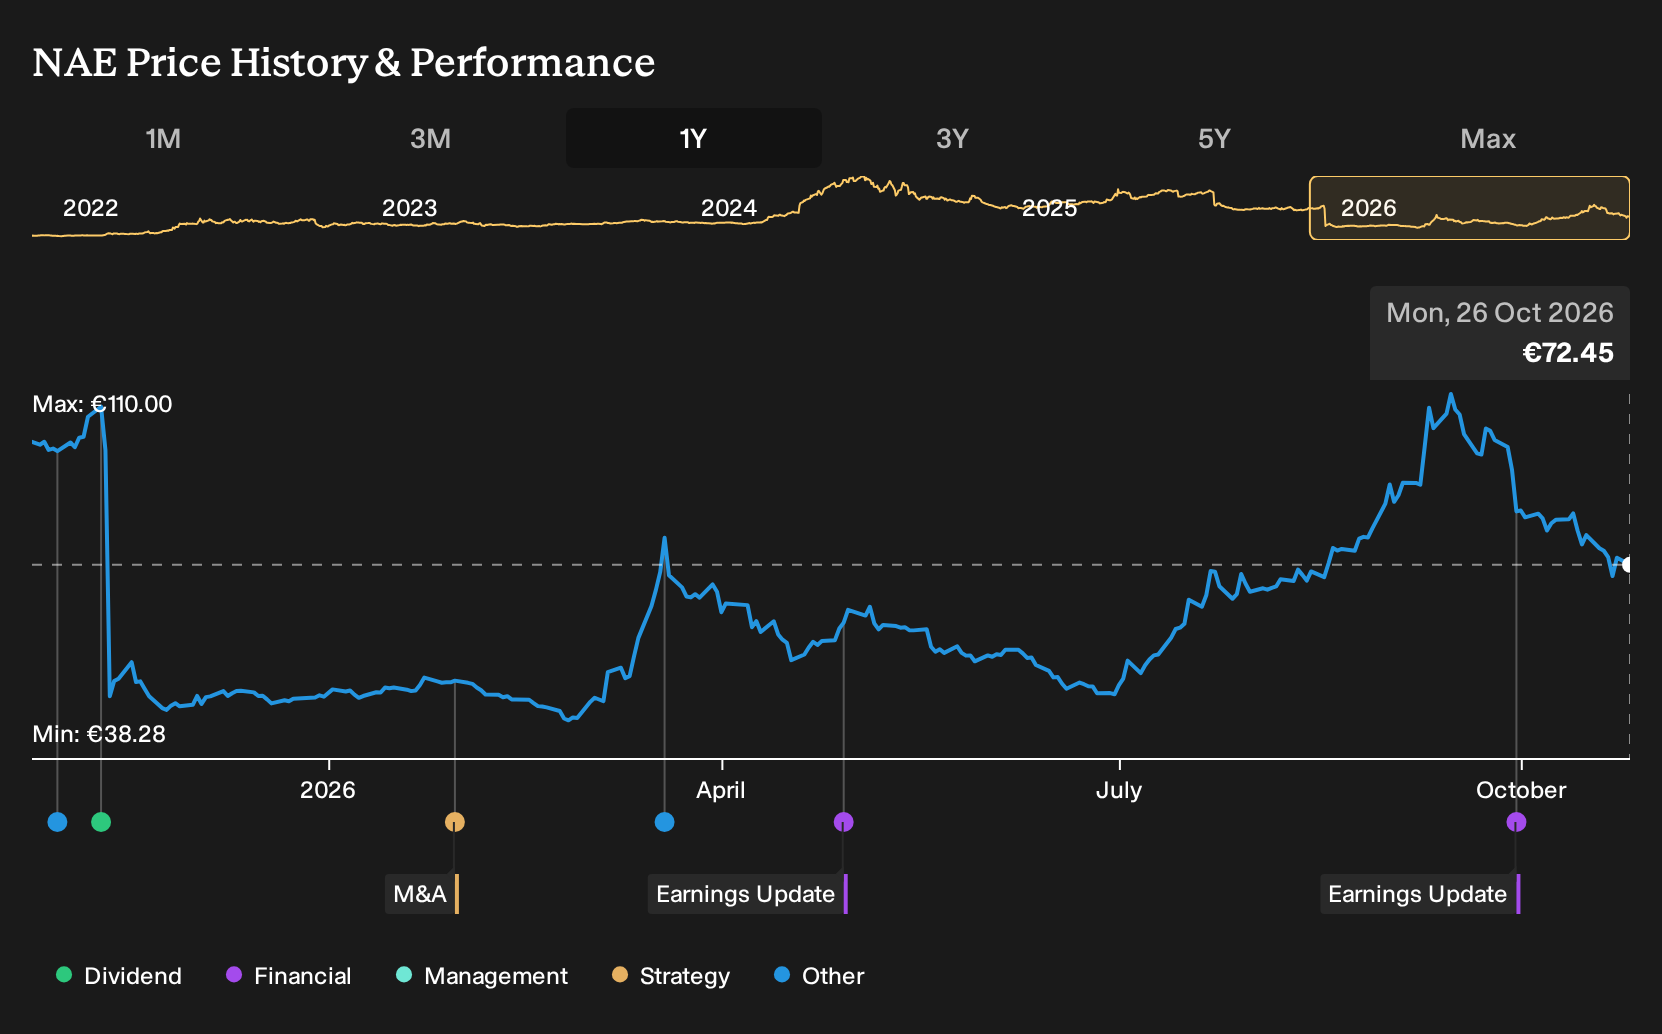
- North Atlantic Energies is drawing focus after a long run in its shares, with the company now trading on a P/S ratio of 0.1x compared with an Oil and Gas sector average of about 1.6x and a broader peer group around 3.9x.
- This unusually low P/S multiple highlights a wide gap between how the market prices North Atlantic Energies and the sales it currently generates, putting fresh attention on the durability and quality of its revenue base.
- We will look at how North Atlantic Energies' investment narrative is shaped by this sharp discount in its P/S valuation.
Scan 194 high quality undervalued stocks, which is hand-picked to highlight other businesses that, like North Atlantic Energies, currently trade on compressed valuation multiples relative to what their sales suggest.
What Is North Atlantic Energies' Investment Narrative?
To own North Atlantic Energies, you have to buy into a pretty specific story. This is a refining and distribution business in France with sizeable sales of €11,407.4m, yet a market value under €1b and a P/S of 0.1x. The recent spotlight on that discount does not change the near term reality. Refining remains capital intensive, earnings have been weak, and the group is currently loss making with net income of €38.4m in the red.
In the short term, the key swing factors are still operational. Utilisation of its refineries, crack spreads, and demand for diesel, marine fuels and specialty products drive cash generation, which already struggles to cover debt and an 83.11% payout ratio. Recent share moves and the focus on low multiples merely sharpen attention on whether management can improve cash flow faster than balance sheet and dividend pressures build, especially with volatile trading and a relatively new board still bedding in.
That said, there is a less comfortable angle to the North Atlantic Energies story that only really comes into focus once you look at ...
There's only one way to know the right time to buy, sell or hold North Atlantic Energies. Head to Simply Wall St's company report for the latest analysis of North Atlantic Energies's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your North Atlantic Energies research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for North Atlantic Energies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate North Atlantic Energies' overall financial health at a glance.
Looking For More Investment Ideas Beyond North Atlantic Energies?
If the valuation gap at North Atlantic Energies has you rethinking where you want to put fresh capital, it can help to line it up against other opportunities using a structured stock filter rather than headlines or hunches.
- If you want potential upside without paying up on traditional valuation metrics, scan a curated set of companies trading on compressed price levels through the 194 high quality undervalued stocks.
- For investors who care most about income strength and payout resilience, focus on steady payers by reviewing the 224 dividend fortresses.
- If capital preservation sits higher on your checklist than raw upside, narrow your watchlist to sturdier balance sheets using the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com