


EN
Yuexiu Property (SEHK:123) Could Be Deeply Undervalued As Mixed Sales Figures Test Sentiment
Yuexiu Property (SEHK:123) has released fresh unaudited sales figures for September and the year to date, giving investors new data on contracted value and selling volume.
These sales figures land against a tricky market backdrop for Yuexiu Property. The share price closed at HK$3.04 and, despite a 1-day share price return of 2.01%, the stock is still down 24.38% on a year to date share price basis and the 1-year total shareholder return has declined 35.56%, which may indicate fading momentum as investors weigh mixed contracted sales trends against existing risks.
Spot opportunities across Chinese real estate by scanning our hand picked list of solid balance sheet and fundamentals (207 results) together with Yuexiu Property's latest sales update.Yuexiu Property’s share slide against mixed contracted sales data leaves an awkward question. Is the price now echoing weaker fundamentals, or has sentiment simply swung too far as the valuation case gets tested next?
Preferred Price-to-Sales Multiple of 0.1x: Is It Justified?
Valuation for Yuexiu Property looks unusual at first glance. The shares closed at HK$3.04 while the business is flagged as trading at good value on several measures, including a P/S ratio of 0.1x.
The price to sales multiple compares the equity value the market is placing on the group to its annual revenue. For a developer and property manager such as Yuexiu Property, this ratio gives you a simple way to relate the HK$12.24b market value to reported revenue of HK$75,532.12m, without relying on earnings that are currently loss making.
On the numbers provided, the stock is described as good value using its preferred P/S ratio of 0.1x compared with peer averages of 0.2x and a Hong Kong real estate sector average of 0.6x. The same framework suggests a fair P/S closer to 0.4x, which indicates that the current market multiple is well below a level the regression-based fair ratio could support.
Explore the SWS fair ratio for Yuexiu Property.
Result: Price-to-sales of 0.1x (UNDERVALUED)
Still, pressure on Yuexiu Property’s annual revenue, which declined 5.22%, and a reported net loss of CN¥1,227.36m may keep sentiment fragile.
Find out about the key risks to this Yuexiu Property narrative.
Another View: Our DCF Model Paints a Very Different Picture
Yuexiu Property looks cheap on the simple P/S snapshot, yet the SWS DCF model goes much further. It values the stock at HK$95.07 per share versus the current HK$3.04, which points to a very large implied upside if those future cash flow assumptions hold.
That kind of gap can signal opportunity, but it also raises questions about how reliable the cash flow forecasts are in a sector facing pressure. Look into how the SWS DCF model arrives at its fair value.
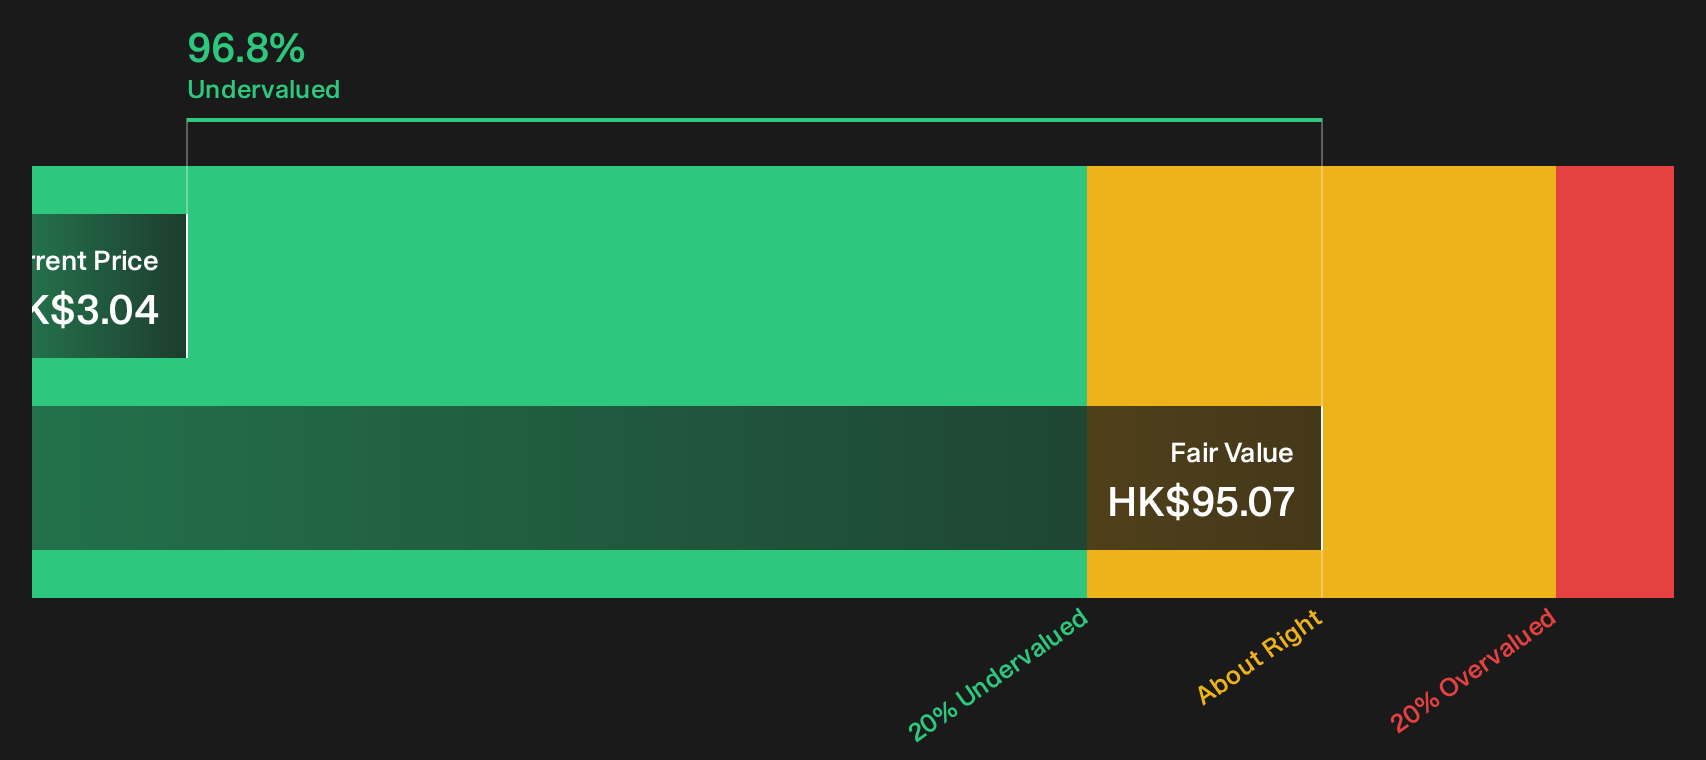
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yuexiu Property for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uneasy about whether sentiment around Yuexiu Property has swung too far in either direction? Consider promptly reviewing the mixed signals in the valuation, sales and balance sheet data, then weigh both sides by checking the 3 key rewards and 1 important warning sign.
Want more stock ideas beyond Yuexiu Property?
If Yuexiu Property has sharpened your focus on value and risk, you can use that momentum. Broaden your watchlist now so you are not reacting late tomorrow.
The Simply Wall St Screener can surface different types of opportunities that fit specific goals and risk levels.
- Target potential mispricing by scanning companies that score well on quality checks yet still trade as 194 high quality undervalued stocks.
- Build a steadier income stream by hunting for payout-focused businesses filtered through our 224 dividend fortresses.
- Sleep easier at night by concentrating on financially resilient businesses identified in the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com