


EN
ASX Growth Companies With High Insider Ownership For October 2026
As the Australian market grapples with inflation concerns and sectoral shifts, highlighted by a recent preference for financials over resources, investors are keenly observing how these trends might influence growth opportunities. In such a climate, companies with high insider ownership can offer unique insights into potential resilience and strategic direction, making them noteworthy considerations for those navigating the current economic landscape.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 15.7% | 97.8% |
| Starpharma Holdings (ASX:SPL) | 17.3% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 14.7% | 28.3% |
| PDI Gold (ASX:PDI) | 11.1% | 62.3% |
| Innovaero Technologies (ASX:INN) | 37.9% | 66.2% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Barton Gold Holdings (ASX:BGD) | 20.8% | 86.7% |
| Austral Resources Australia (ASX:AR1) | 22.6% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
We're going to check out a few of the best picks from our screener tool.
Duratec (ASX:DUR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Duratec Limited, with a market cap of A$500.83 million, provides assessment, protection, remediation, and refurbishment services for steel and concrete infrastructure assets in Australia.
Operations: The company's revenue is derived from several segments, including Energy (A$91.56 million), Defence (A$157.75 million), Buildings & Facades (A$138.84 million), and Mining & Industrial (A$114.34 million).
Insider Ownership: 28.0%
Earnings Growth Forecast: 15.4% p.a.
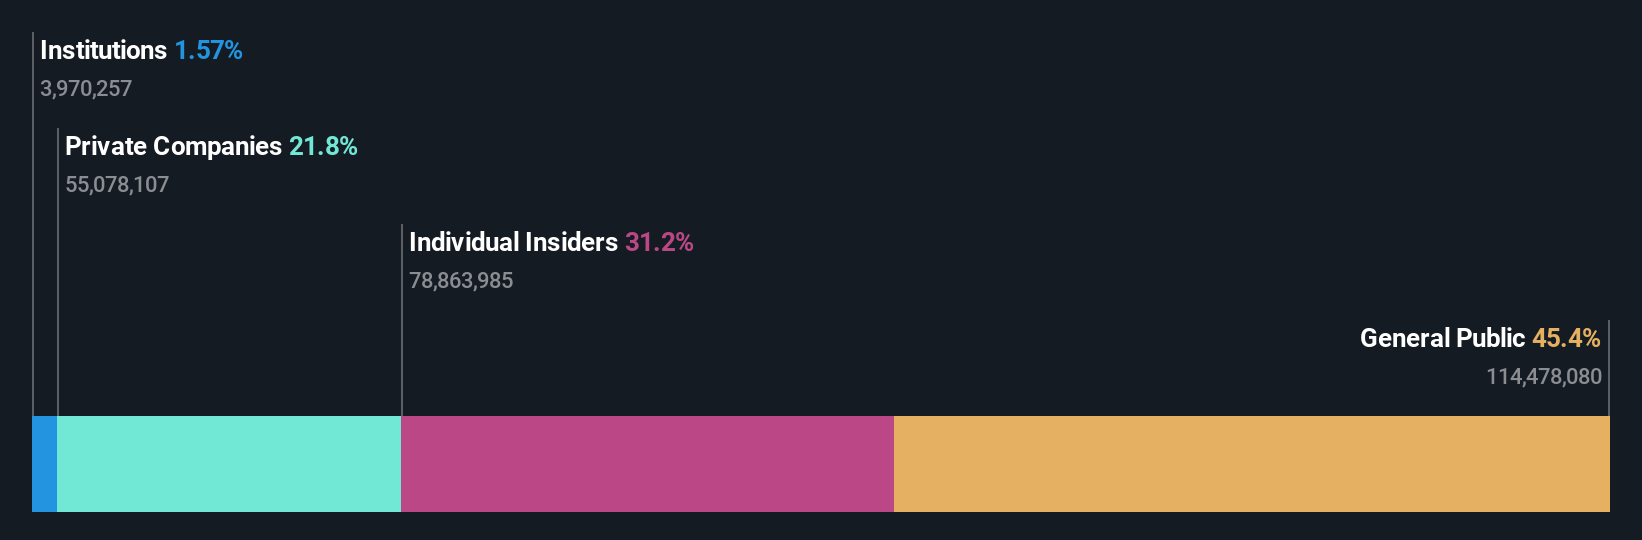
Duratec, with a robust insider ownership structure, is positioned for growth with earnings projected to rise 15.4% annually, outpacing the Australian market. Recent strategic moves include seeking acquisitions to enhance capabilities and expand its portfolio, supported by a strong cash balance of A$78.8 million. The company's revenue growth forecast at 9.6% per year exceeds the market average, while analysts anticipate a potential stock price increase of nearly 49%.
- Delve into the full analysis future growth report here for a deeper understanding of Duratec.
- According our valuation report, there's an indication that Duratec's share price might be on the expensive side.
Emerald Resources (ASX:EMR)
Simply Wall St Growth Rating: ★★★★★★
Overview: Emerald Resources NL is involved in the exploration, operation, and evaluation of mineral reserves in Cambodia and Australia, with a market cap of A$3.93 billion.
Operations: The company generates revenue primarily from its mine operations, amounting to A$601.79 million.
Insider Ownership: 18.6%
Earnings Growth Forecast: 23.9% p.a.
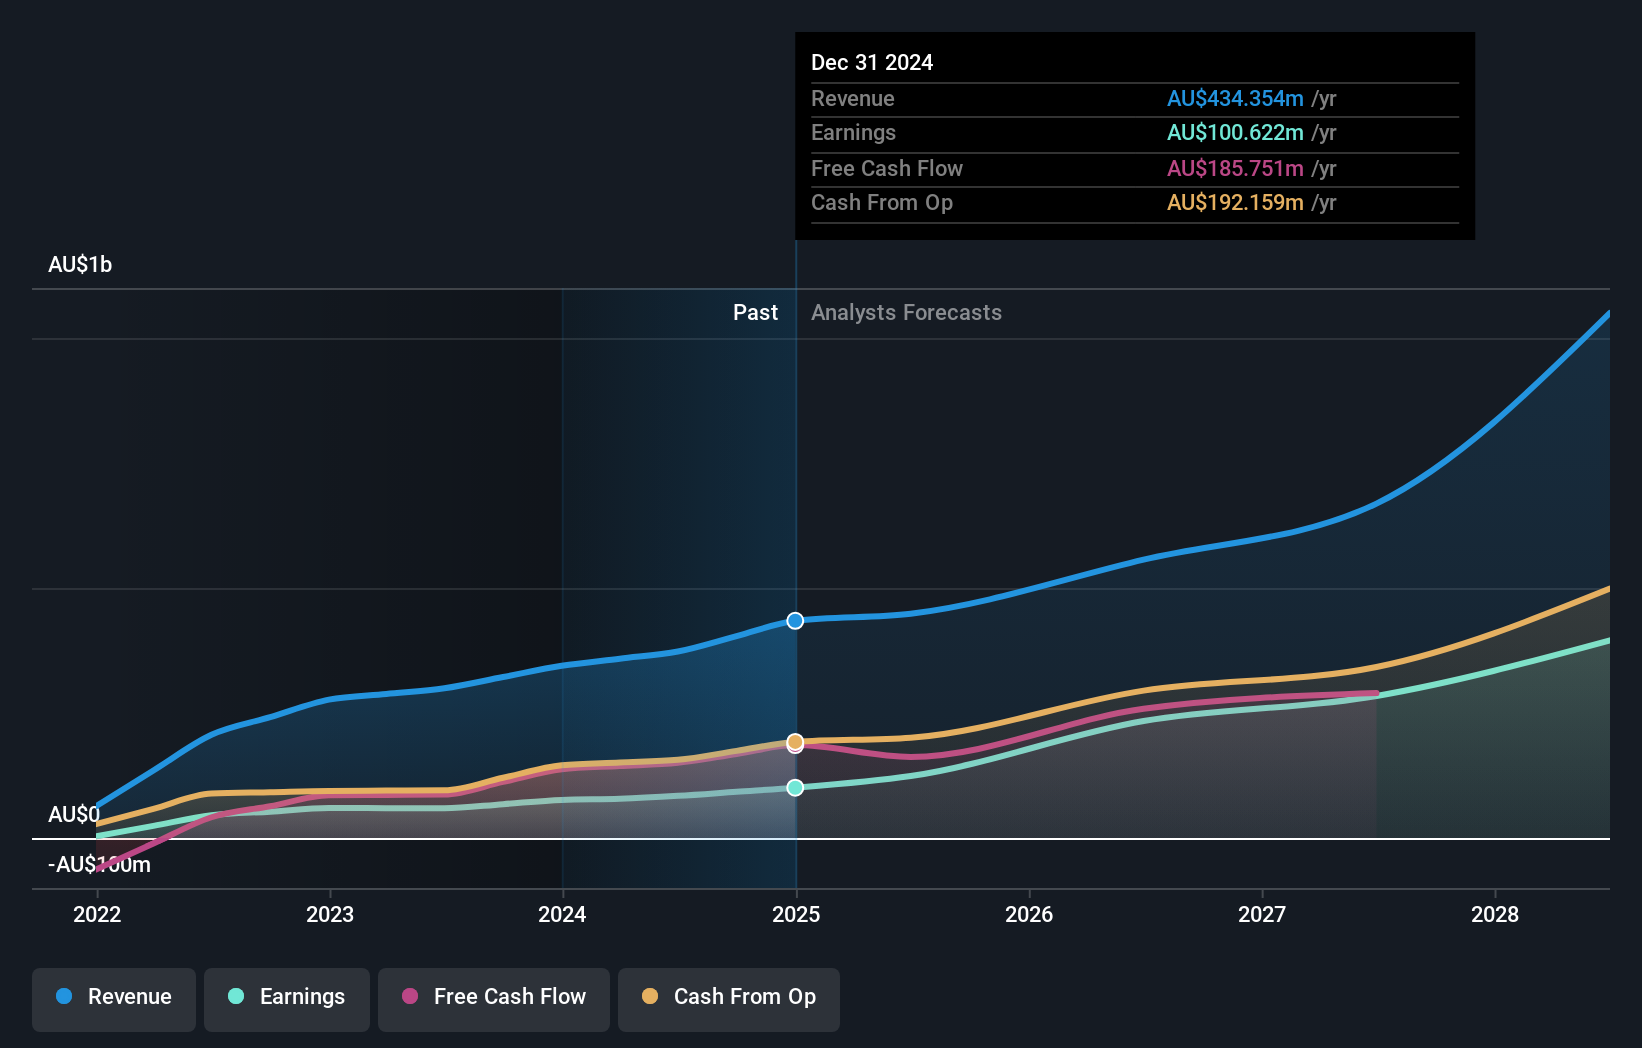
Emerald Resources demonstrates strong growth potential with earnings projected to rise 23.9% annually, surpassing the Australian market's pace. Revenue is set to grow at 33.1% per year, significantly above market expectations. The company reported A$612.32 million in sales for FY2026, up from A$437.79 million the previous year, and net income increased to A$259.59 million from A$87.61 million a year ago, reflecting substantial financial growth without insider trading activity over recent months.
- Unlock comprehensive insights into our analysis of Emerald Resources stock in this growth report.
- The valuation report we've compiled suggests that Emerald Resources' current price could be quite moderate.
Magellan Financial Group (ASX:MFG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Magellan Financial Group Limited is a publicly owned investment manager with a market cap of A$2.23 billion.
Operations: The company's revenue segments include A$5.02 million from Corporate, A$40.10 million from Partnerships & Investments, and A$205.69 million from Investment Management Services.
Insider Ownership: 15.5%
Earnings Growth Forecast: 14.6% p.a.
Magellan Financial Group, now Barrenjoey Group Limited, shows promising revenue growth forecasts of 20.1% annually, outpacing the Australian market's 4.8%. Despite this, its dividend yield of 8.53% is unsustainable from earnings or cash flows. Insider activity indicates more buying than selling recently, though not in large volumes. The company trades at a significant discount to fair value but has experienced shareholder dilution and was removed from the FTSE All-World Index recently.
- Click here and access our complete growth analysis report to understand the dynamics of Magellan Financial Group.
- Our valuation report unveils the possibility Magellan Financial Group's shares may be trading at a premium.

Turning Ideas Into Actions
- Discover the full array of 120 Fast Growing ASX Companies With High Insider Ownership right here.
- Ready To Venture Into Other Investment Styles? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com