


EN
Is Raised Earnings Guidance Altering The Investment Case For Kawasaki Kisen Kaisha Stock (TSE:9107)?
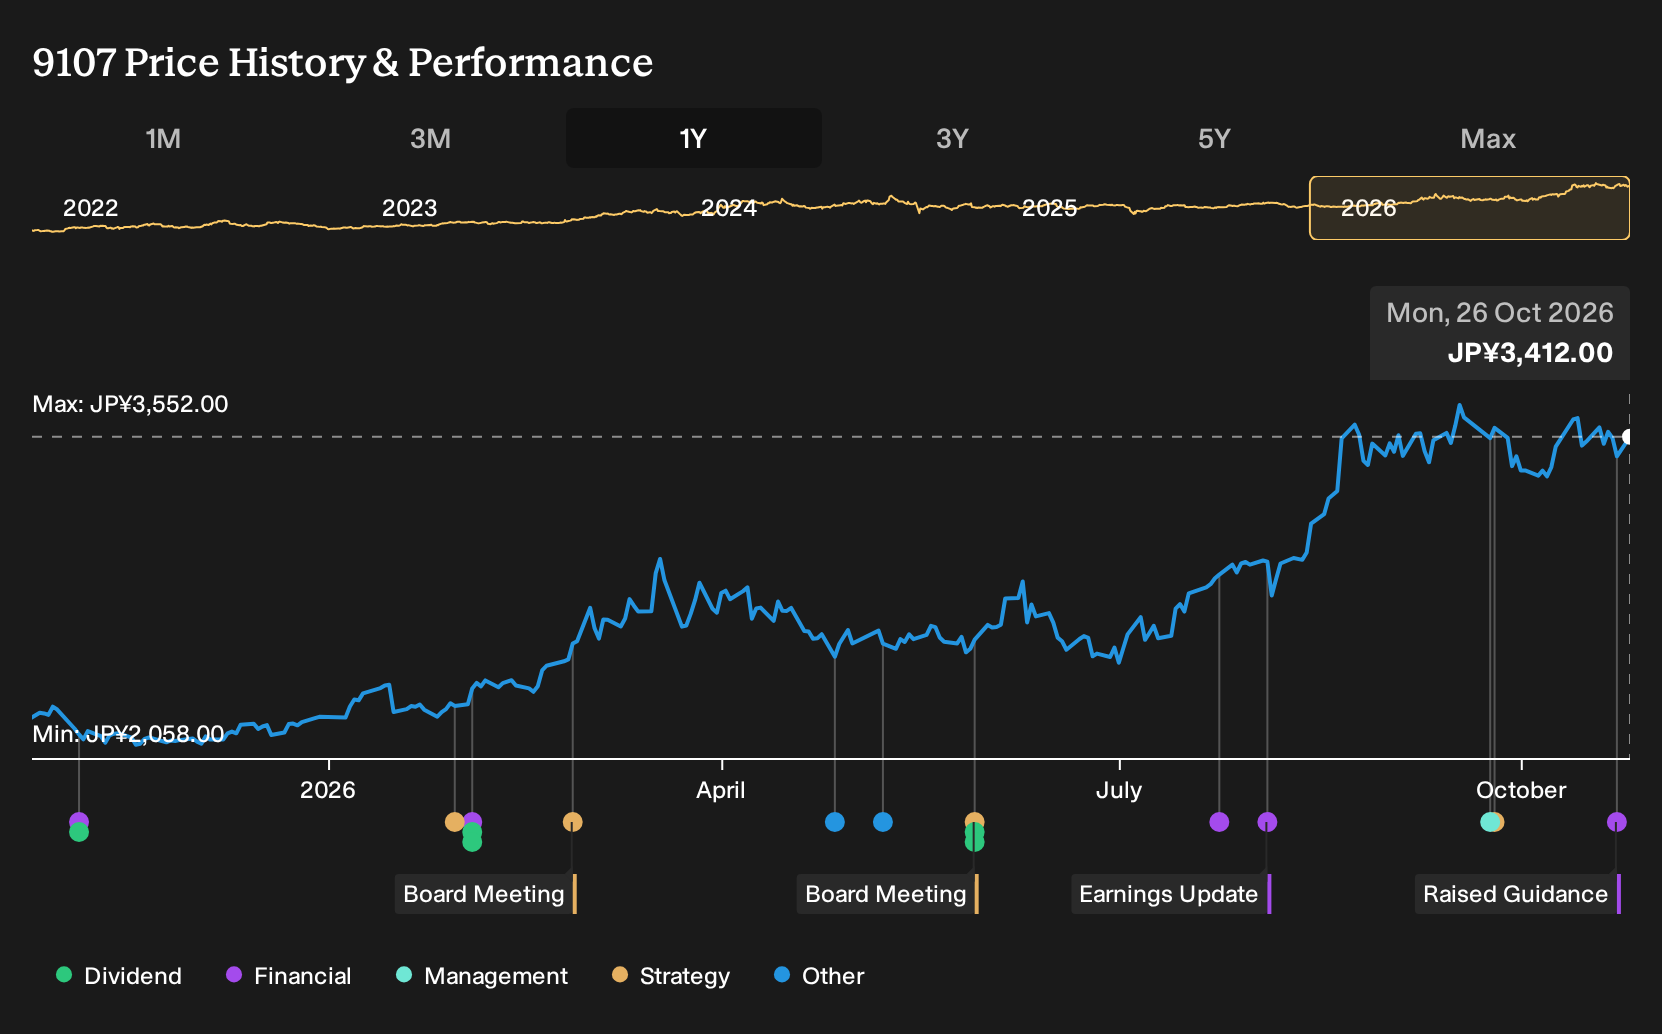
- Kawasaki Kisen Kaisha raised its consolidated guidance for the second quarter of fiscal 2026 and for the year to March 2027, lifting projected operating revenue to ¥602,000 million and ¥1,170,000 million, and profit attributable to owners of the parent to ¥124,500 million and ¥190,000 million respectively.
- Management linked the revised outlook to a stable Drybulk market and stronger than expected cargo demand and spot freight rates at affiliate OCEAN NETWORK EXPRESS. This development sharpens focus on how sensitive Kawasaki Kisen Kaisha’s earnings remain to shipping cycle conditions.
- We will now look at how Kawasaki Kisen Kaisha’s investment narrative interacts with this upgraded guidance driven by Drybulk and container demand.
Kawasaki Kisen Kaisha Investment Narrative Recap
To own Kawasaki Kisen Kaisha, you need to be comfortable with a shipping group whose fortunes are tied to dry bulk and container cycles, with a partial cushion from long term energy transport contracts. The upgraded guidance leans on a stable Drybulk backdrop and a firmer OCEAN NETWORK EXPRESS contribution, which supports the near term earnings story but does not remove cyclicality.
The main short term swing factor remains freight rate and volume resilience across bulk and container routes, especially if trade flows or tariff policy shift. The key risk stays the same. Sector overcapacity, soft pricing or weaker demand could squeeze margins again, in a backdrop where consensus expects flat to slightly declining earnings.
There are no fresh announcements beyond this guidance, so the revision itself is the clearest reference point for Kawasaki Kisen Kaisha right now. The step up in projected profit attributable to owners of the parent for both the first half and full year directly affects how you think about the earnings base that consensus models use.
Forward looking risks flagged before the update still matter. Analysts had expected modest revenue expansion, margin pressure and flat earnings over the next few years. The higher forecast for operating income and profit in fiscal 2027 tests those assumptions and places more emphasis on how well management handles freight volatility, decarbonisation capex and potential overcapacity in container shipping.
Kawasaki Kisen Kaisha is framed around analyst expectations that revenues reach ¥1,174.4b and earnings land at ¥143.6b by 2029, based on an assumed 3.5% yearly revenue growth rate and an earnings increase of about ¥17.2b from the current ¥126.4b base.
Uncover why Kawasaki Kisen Kaisha's fair value indicates a 13% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle on Kawasaki Kisen Kaisha centers on containership overcapacity. The most bearish analysts were pencilling in flat revenue near ¥1,066.0b and only ¥124.4b in earnings by 2029, with a P/E near 8.1x. That is a far harsher freight market story. The new guidance could prompt those assumptions to shift. Explore both sides before you decide how to frame the stock in your portfolio.
Explore 2 other Kawasaki Kisen Kaisha fair value estimates, including one that suggests as much as 100% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A useful starting point for your Kawasaki Kisen Kaisha research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kawasaki Kisen Kaisha. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review Kawasaki Kisen Kaisha's overall financial position at a glance.
Looking for more investment ideas beyond Kawasaki Kisen Kaisha?
If you want to put Kawasaki Kisen Kaisha into context and see how it stacks up against other opportunities, the Simply Wall St Screener can help you quickly filter for businesses that better match your risk tolerance and income or growth goals.
- For investors who like backing potential turnarounds with smaller market values, scan a carefully filtered group of 1 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical speculative play.
- If capital preservation matters just as much as returns, focus on a curated set of 22 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- For readers who prefer quality and fundamentals first, work through a 72 high quality undiscovered gems that combines financial resilience with cleaner balance sheets than the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com