


EN
Crane (CR) Earnings Loom As Investors Revisit The Case For A Cheap Stock
Crane earnings in focus as investors weigh recent track record
Crane (CR) heads into its upcoming earnings release with attention firmly on whether it can continue its streak of positive surprises after several quarters of outperforming market expectations.
Recent trading tells a different story from Crane's earnings track record. The share price has fallen 3.3% in the past day and is down about 11% over the past month. The 90 day share price return is weaker at roughly 19% lower, even though the 3 year total shareholder return is close to 98% and the 5 year total shareholder return is about 180%. This suggests longer term holders have still seen strong compounding despite the recent loss of momentum heading into this earnings release.
Scan how Crane compares with other industrials on earnings momentum by reviewing the hand picked 28 high quality undervalued stocks, which also pair solid cash generation with support from the balance sheet.
The share price slide into this earnings report gives Crane a very different entry point than a few months ago. Does that reset offer a reasonable entry window now, or argue for patience until valuation cools further?
Most Popular Narrative: 23% Undervalued
Crane closed at $182.89, while the most followed narrative anchors fair value around $237.20. The debate now is whether the earnings story can justify that gap as the next quarterly numbers land.
Crane’s recent acquisition of PSI, which includes Druck, Panametrics and Reuter-Stokes, continues to expand the company’s presence in higher margin sensing and fluid control applications. 2026 EPS accretion is now guided at about US$0.20 compared with the original US$0.08 expectation, supporting further earnings and margin growth.
See why 5 investors see Crane as 23% undervalued.
Result: Fair Value of $237.20 (UNDERVALUED)
Still, the Crane narrative can be knocked off course if weakness in chemicals drags on Process Flow Technologies, or if premium P/E expectations unwind in response to any margin slip.
Find out about the key risks to this Crane narrative.
Another View: Crane valuation through the earnings lens
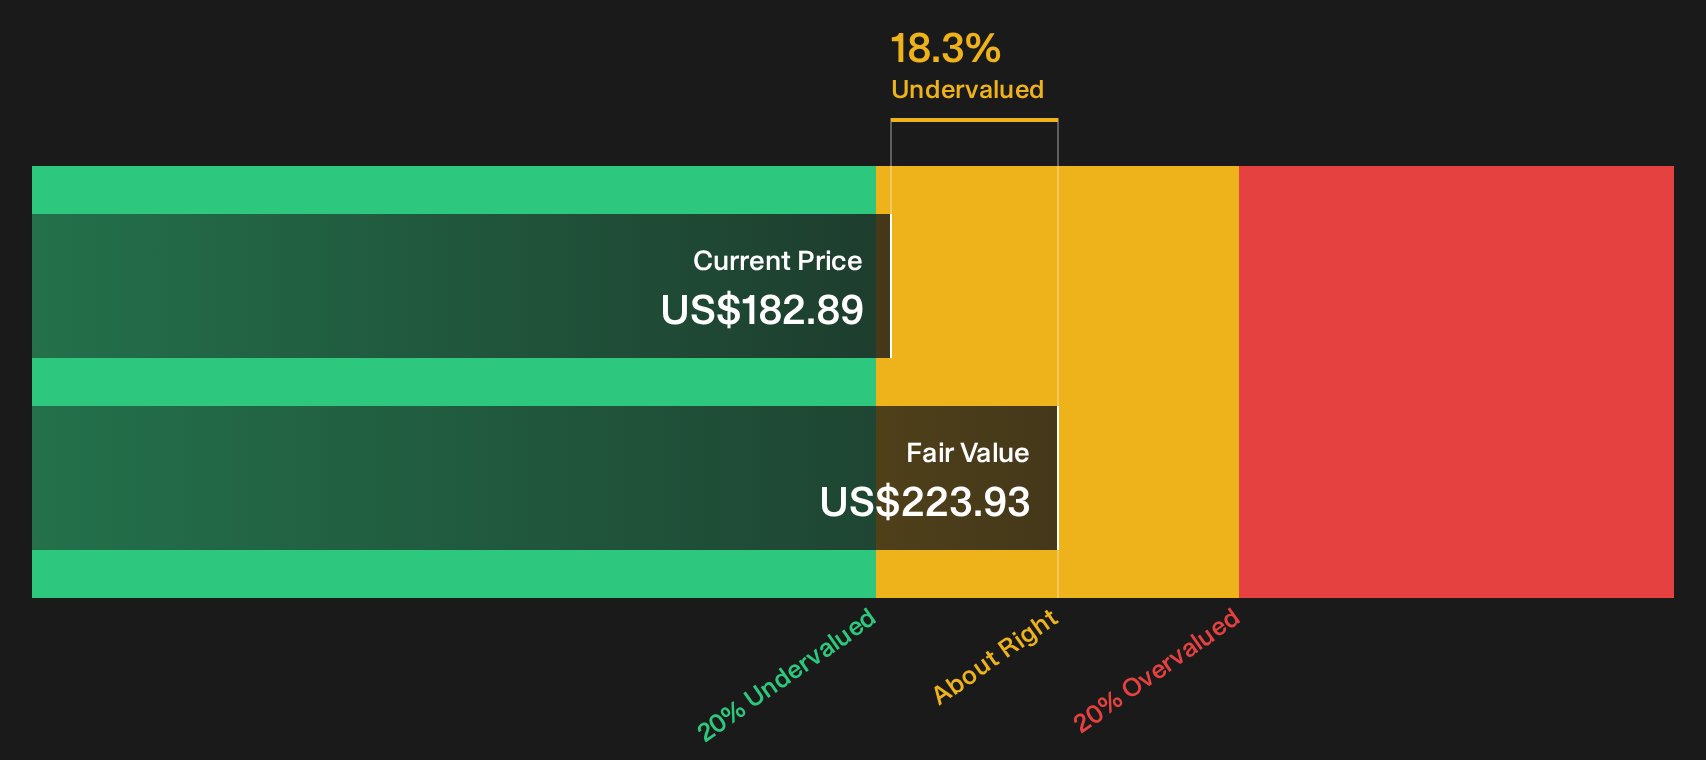
Crane looks cheap on cash flows, with our DCF model suggesting fair value around $223.93 versus a $182.89 share price. However, its 31.5x P/E is richer than the Machinery industry on 24.4x and a fair ratio of 23.8x. Which signal do you trust more when earnings land?
Investors who want to see how that cash flow result is built line by line can go deeper with the SWS DCF model and stress test their own assumptions against it Look into how the SWS DCF model arrives at its fair value..
Next Steps
Sentiment on Crane is split, with both caution and optimism in the mix. Move quickly to test the data yourself and pressure check the thesis from every angle by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Crane?
Do not stop at a single stock. Use the Simply Wall Street Screener to test fresh angles, compare opportunities quickly, and spot ideas others might overlook.
- Zero in on financially resilient businesses by running the list of solid balance sheet and fundamentals (24 results) to keep balance sheets and fundamentals front and center.
- Hunt for mispriced quality by scanning the 21 high quality undiscovered gems to pair strong fundamentals with limited market attention.
- Prioritize sleep-at-night positions by focusing on the 30 resilient stocks with low risk scores to aim to keep risk scores in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com