


EN
How Stronger Earnings At Dime Community Bancshares Stock Has Changed Its Investment Story
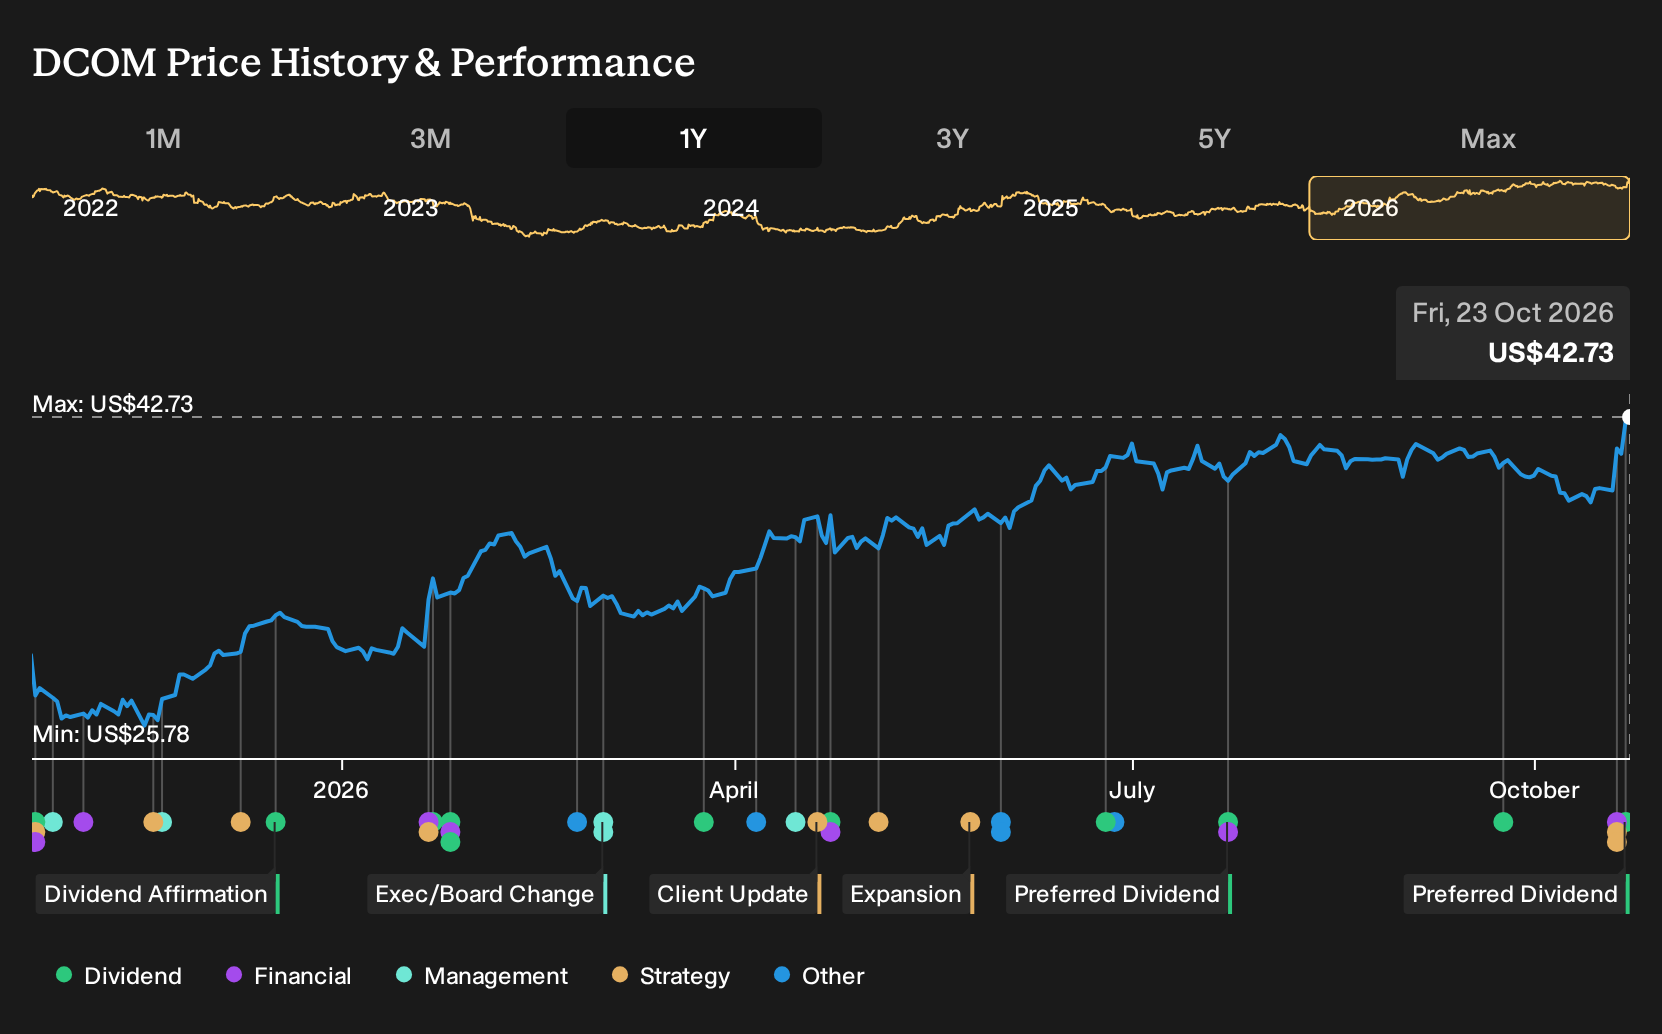
- Dime Commercial Bancshares reported third quarter 2026 net interest income of US$121.22 million and net income of US$41.56 million, and declared a quarterly cash dividend of US$0.34375 per share on its 5.50% Fixed Rate Non Cumulative Perpetual Preferred Stock, Series A, payable on November 16, 2026.
- The bank also reported net loan charge offs of US$9.749 million for the quarter ended September 30, 2026, which was lower than the prior year period and provides context for the reporting period’s earnings profile.
- This analysis will assess how Dime Commercial Bancshares’ third quarter 2026 earnings relate to the existing investment narrative around its commercial transformation.
Scan how Dime Commercial Bancshares’ earnings and preferred dividend compare with peers by reviewing a curated set of list of solid balance sheet and fundamentals (24 results)
Dime Commercial Bancshares Investment Narrative Recap
Dime Commercial Bancshares still hinges on a simple belief for common shareholders. The commercial pivot needs to turn low cost deposits and the loan repricing pipeline into a more resilient net interest margin without credit issues or higher operating costs eating into that progress. The latest quarter shows higher net interest income and earnings, which supports that story but does not remove execution risk.
The short term swing factor remains how quickly new commercial teams and verticals translate into sustainable fee and interest income. Expense creep and credit quality in commercial real estate and multifamily remain the biggest pressure points. Third quarter net loan charge offs were lower than a year ago, which helps near term sentiment but does not settle the longer term credit question.
The most relevant recent development for that thesis is the third quarter 2026 earnings update. Net interest income of US$121.22 million and net income of US$41.56 million, alongside basic EPS from continuing operations of US$0.90, provide a clearer view of how the commercial transformation is flowing through the income statement at this stage.
Those numbers sit next to net loan charge offs of US$9.749 million for the period, which were lower than the prior year quarter and offer some breathing room on the credit side. For investors tracking catalysts, the combination of higher reported earnings, ongoing loan repricing and currently manageable credit costs is where the near term debate on Dime Commercial Bancshares is likely to remain focused.
What The Current Consensus Implies For Dime Commercial Bancshares
Dime Commercial Bancshares' narrative projects US$662.6 million revenue and US$220.6 million earnings by 2029. This assumes 14.7% yearly revenue growth and an earnings increase of about US$101 million from current earnings of US$119.3 million.
Uncover how Dime Commercial Bancshares' fair value indicates an 8% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$46 to about US$88.66, which shows how far apart retail views on Dime Commercial Bancshares can be. When you set that against rising expenses, credit risk in commercial real estate and multifamily, and the loan repricing pipeline, you can arrive at very different conclusions about future performance. You should expect opinion to vary widely and use these contrasting takes as a prompt to explore several alternative viewpoints before forming your own stance.
Explore 2 other Dime Commercial Bancshares fair value estimates, including one that suggests potential upside of up to 107% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Dime Commercial Bancshares research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Dime Commercial Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dime Commercial Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dime Commercial Bancshares?
If Dime Commercial Bancshares has put commercial banking back on your radar, it can pay to widen the search and compare it with other businesses that share similar strengths or offer very different risk profiles. A focused screener trims the noise so you spend time assessing a smaller group of candidates that already match the broad traits you care about.
- Chasing value with quality in mind can sharpen your watchlist. Use the Simply Wall St screener to explore 28 high quality undervalued stocks that pair pricing support with fundamental strength.
- If income is your priority, filter for payouts that aim to combine size and resilience. The dividend focused screener highlights 5 dividend fortresses that might suit a yield oriented approach.
- If you prefer sturdier balance sheets and cleaner fundamentals, start with a curated list of solid balance sheet and fundamentals (24 results) and compare how each business holds up against your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com