


EN
Nicolet Bankshares (NIC) Could Be 38% Undervalued As Q3 Earnings And Dividend Land
Nicolet Bankshares (NIC) moved into focus after reporting third quarter 2026 results that showed higher net interest income and net income, along with a fresh quarterly dividend and slightly larger net loan charge-offs.
At a share price of US$171.41 as of 23 October 2026, Nicolet Bankshares has seen a 1-day share price return of 1.04% and a 7-day share price return of 5.43%, with third quarter earnings and the fresh US$0.36 dividend declaration likely reinforcing recent momentum. Over a longer horizon the picture is still strong, with a year to date share price return of 42.26% and a 3-year total shareholder return of 144.28%. However, the 90-day share price return declined 1.01%, which hints that the pace of gains has cooled slightly after a very strong multi year run.
Spot similar stories of strong earnings and dividend momentum by scanning our hand picked 5 dividend fortresses, which may interest income focused investors watching Nicolet Bankshares.Nicolet Bankshares now combines strong recent earnings, a richer dividend and a powerful multi year share run. The open question for investors is whether that mix is already fully reflected in today’s price.
Preferred P/E of 20.3x for Nicolet Bankshares: Is it justified?
Nicolet Bankshares trades on a P/E of 20.3x, which sits well above both the wider US banks sector and its closest peer group, even after the strong share price run to $171.41.
The P/E ratio compares what investors pay for each dollar of earnings to what the company currently generates in profit. For a lender like Nicolet Bankshares, this metric often reflects how the market views the durability of its profit stream, the quality of its loan book and how management is expected to steer returns through the cycle.
Here, the gap is wide. The business carries a 20.3x P/E against an 11.5x average for US banks and a 10.9x mark for its peer set, which signals that the market is willing to pay a clear premium for Nicolet Bankshares earnings. Compared to an estimated fair P/E of 15.3x, the current valuation also sits meaningfully higher. This is a level investors sometimes watch if they think pricing could drift back toward that reference point over time.
Explore the SWS fair ratio for Nicolet Bankshares.Result: Price-to-earnings of 20.3x (OVERVALUED)
Still, the premium on Nicolet Bankshares could come under pressure if credit losses climb from here or if revenue growth of 3.47% reflects slower underlying momentum.
Find out about the key risks to this Nicolet Bankshares narrative.
Another View on Nicolet Bankshares Valuation
That rich 20.3x P/E hints at a full price, yet the SWS DCF model points a different way. With Nicolet Bankshares trading at $171.41 against an estimated future cash flow value of $275.41, the shares screen as materially undervalued. Which signal should investors trust more?
Look into how the SWS DCF model arrives at its fair value.
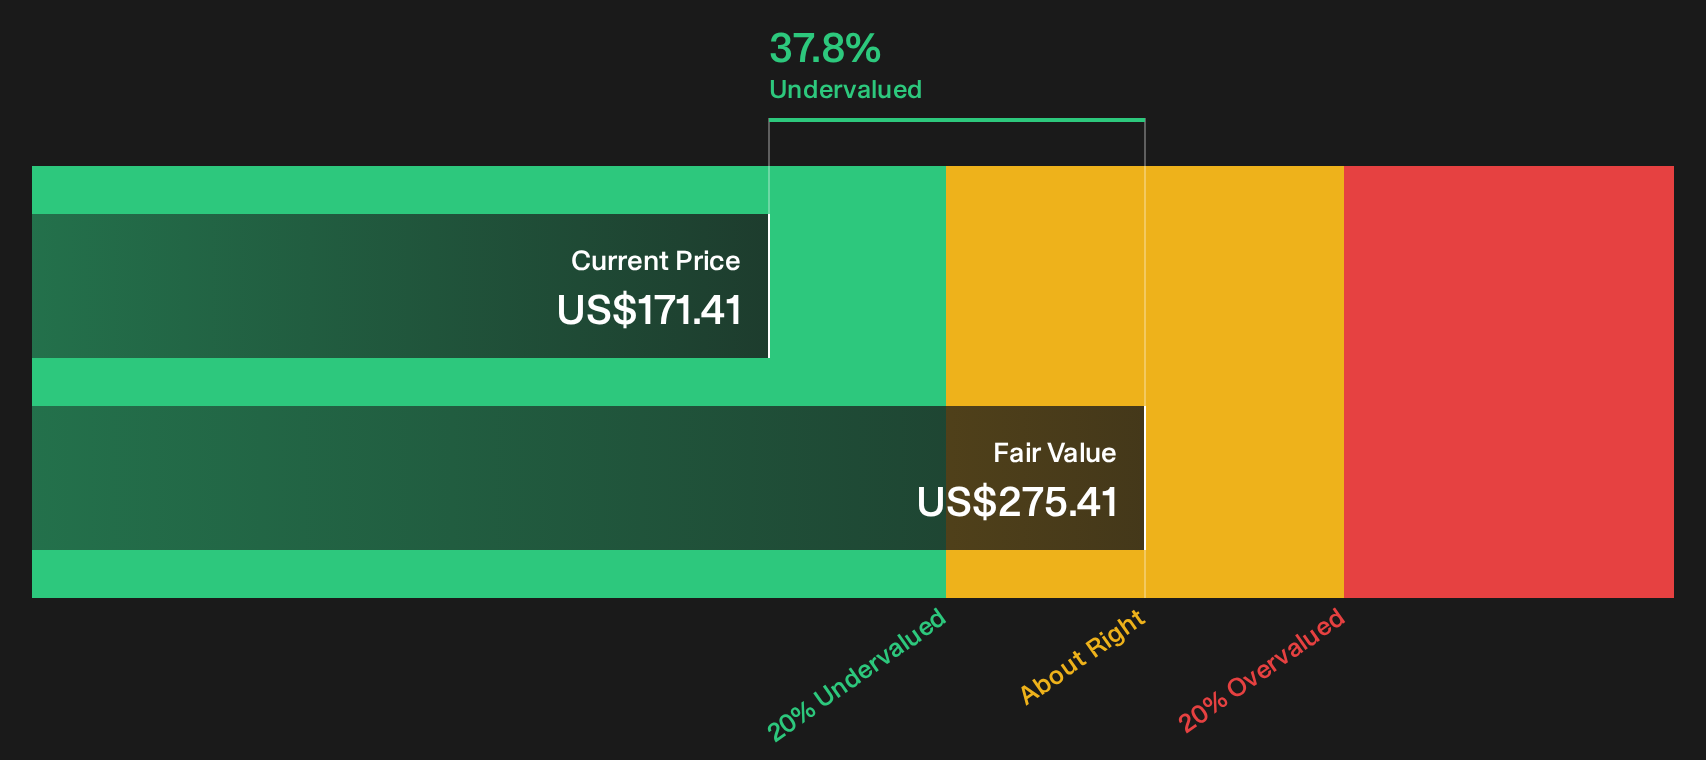
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nicolet Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nicolet Bankshares valuation and risks can feel messy, so move fast, test the assumptions against the data, and then own your decision with the full breakdown of 3 key rewards and 1 important warning sign.
Looking for more Nicolet Bankshares style ideas?
If Nicolet Bankshares has sharpened your focus, do not stop here. Fresh ideas often come from scanning beyond your watchlist and testing new angles.
- Target resilient candidates that emphasise capital strength and disciplined funding profiles by reviewing our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value opportunities where price and fundamentals may be misaligned by running the 28 high quality undervalued stocks.
- Boost your shortlist with companies that pair income potential with disciplined payout metrics using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com