


EN
How Deer Park Terminal Opening At Saia (SAIA) Has Changed Its Investment Story
- Saia has opened a new terminal in Deer Park, New York, adding Long Island coverage to its Northeast less than truckload network and increasing capacity to handle shipping demand across the greater New York metropolitan area.
- This Deer Park facility gives Saia closer proximity to one of the most densely populated and economically important regions in the US, which can reshape freight density, route efficiency and service options across its nationwide network.
- We will now look at how Saia's investment narrative could be influenced by the new Deer Park terminal and the expansion of its Northeast density.
Saia Investment Narrative Recap
To own Saia, you need to believe its expanding terminal grid can turn higher density into better efficiency and pricing, even as costs stay elevated. The Deer Park opening fits that thesis because it deepens coverage in a complex, high volume region rather than stretching the network thin. The key near term swing factor remains how quickly newer facilities move toward mature operating ratios.
The biggest operational risk still sits on the cost side. Wages, benefits, fuel, and insurance have all pressured margins recently, and a larger footprint adds more fixed expense. If the Long Island site ramps slowly or freight mix is weaker than expected, the added capacity could weigh on profitability instead of supporting it.
The Deer Park move connects cleanly to Saia's broader push to expand and densify its terminal network, with more than 218 facilities added or upgraded since 2022. Investors are watching whether those newer locations, including Long Island, can progress from start up efficiency levels toward the rest of the system while keeping service quality tight.
Execution around this build out ties directly into the main catalysts. Management is leaning on Saia REV technology, transit time improvements, and guaranteed deliveries to support pricing and mix as the grid fills in. If those tools help offset wage, fuel, and insurance pressure at a larger scale, the case for future margin improvement across the network becomes stronger.
Saia's narrative projects US$4.4b revenue and US$510.4m earnings by 2029. This assumes 8.8% yearly revenue growth and an earnings increase of about US$232.4m from US$278.0m today.
Uncover how Saia's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
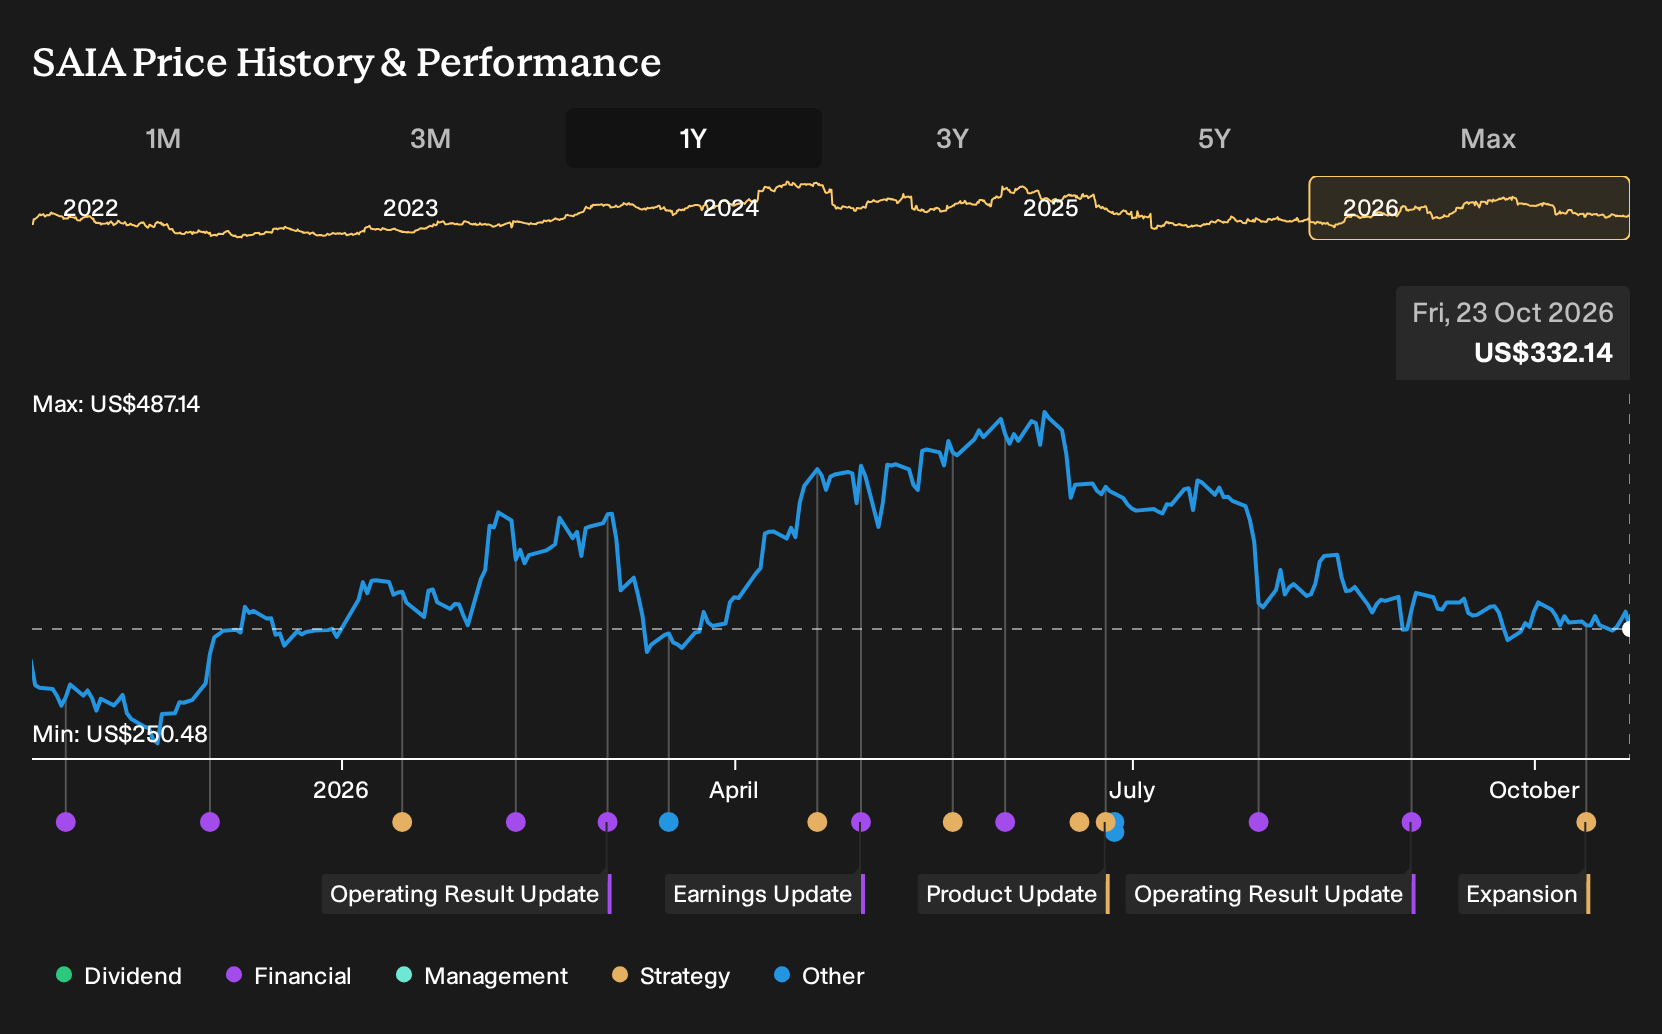
Exploring Other Perspectives
One alternate view around Saia focuses less on terminal wins and more on cost creep. The most cautious analysts were penciling in revenue of about US$4.2b and earnings of roughly US$472.0m by 2029 before this Deer Park news. That is a more muted path, and it reminds you that opinions can differ widely and may shift as this Long Island terminal beds in.
Explore 4 other Saia fair value estimates, including one that suggests as much as 56% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Saia research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Saia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saia's overall financial health at a glance.
Looking for more Saia style investment ideas?
If Saia's Long Island expansion has you thinking about how to position your portfolio, it can help to line it up against other businesses with different strengths, balance sheets and income profiles.
- For investors who want potential mispricing with financial resilience, compare Saia to a curated set of companies in the 28 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than headline growth, scan the 30 resilient stocks with low risk scores to see which businesses score well on resilience.
- When you want to focus on quality first and avoid fragile finances, weigh Saia alongside a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com