


EN
Addus HomeCare And Two Other Stocks Trading Below Estimated Intrinsic Value
The United States market has remained flat over the past week but is up 8.1% over the past year, with earnings projected to grow by 17% annually. In this context, identifying stocks trading below their estimated intrinsic value can present opportunities for investors seeking potential growth and value in an otherwise stable market environment.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| WESCO International (WCC) | $318.02 | $594.62 | 46.5% |
| Textron (TXT) | $76.83 | $148.32 | 48.2% |
| Northeast Bank (NBN) | $128.74 | $241.03 | 46.6% |
| Noah Holdings (NOAH) | $6.82 | $13.29 | 48.7% |
| Halliburton (HAL) | $34.92 | $66.27 | 47.3% |
| ConnectOne Bancorp (CNOB) | $32.69 | $65.37 | 50% |
| Civista Bancshares (CIVB) | $28.29 | $56.56 | 50% |
| Atlantic Union Bankshares (AUB) | $39.89 | $78.92 | 49.5% |
| Artisan Partners Asset Management (APAM) | $33.57 | $64.88 | 48.3% |
| Amazon.com (AMZN) | $248.00 | $471.74 | 47.4% |
Let's take a closer look at a couple of our picks from the screened companies.
Addus HomeCare (ADUS)
Overview: Addus HomeCare Corporation offers personal care services to elderly, chronically ill, and disabled individuals in the United States and has a market cap of $2.23 billion.
Operations: The company's revenue segments include Hospice services generating $268.93 million, Home Health services contributing $68.65 million, and Personal Care services accounting for $1.14 billion.
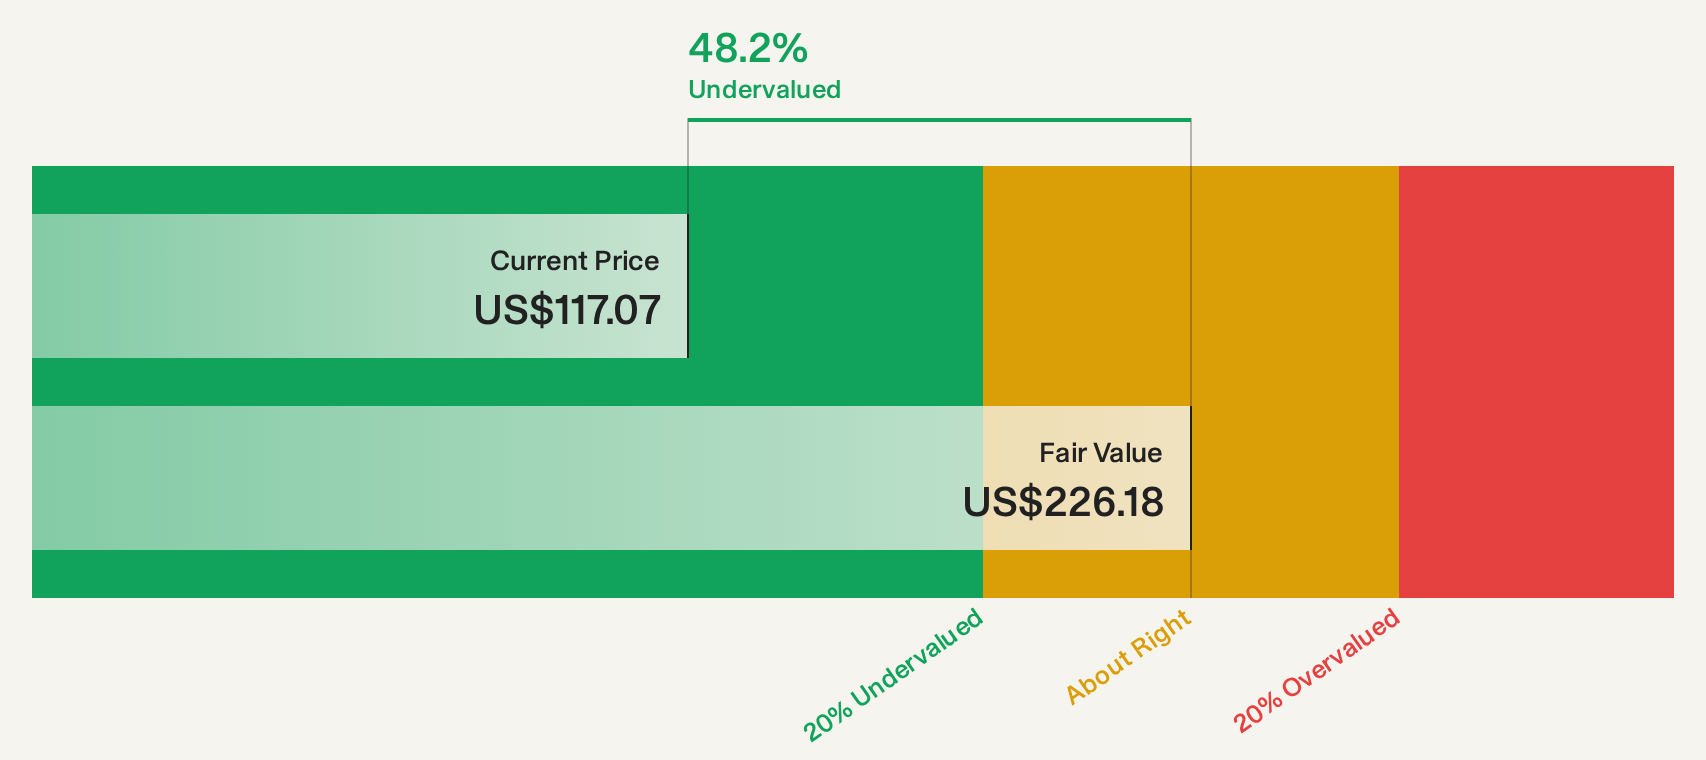
Estimated Discount To Fair Value: 46.1%
Addus HomeCare appears undervalued based on discounted cash flow analysis, trading at US$121.81 against an estimated value of US$226.18, a 46.1% discount. The company has strong cash flows, enabling debt reduction to US$64.3 million and potential acquisitions to expand market reach. Recent executive changes with Brad Bickham returning as interim COO may influence strategic direction positively, though revenue growth forecasts of 4.9% lag behind the broader market's 13.3%.
- Our earnings growth report unveils the potential for significant increases in Addus HomeCare's future results.
- Dive into the specifics of Addus HomeCare here with our thorough financial health report.
Daktronics (DAKT)
Overview: Daktronics, Inc. designs, manufactures, and sells electronic display systems for sports, commercial, and transportation applications globally, with a market cap of approximately $990.71 million.
Operations: The company's revenue segments include Commercial at $178.31 million, Live Events at $327.65 million, International at $88.22 million, Transportation at $81.50 million, and High School Park and Recreation at $178.61 million.
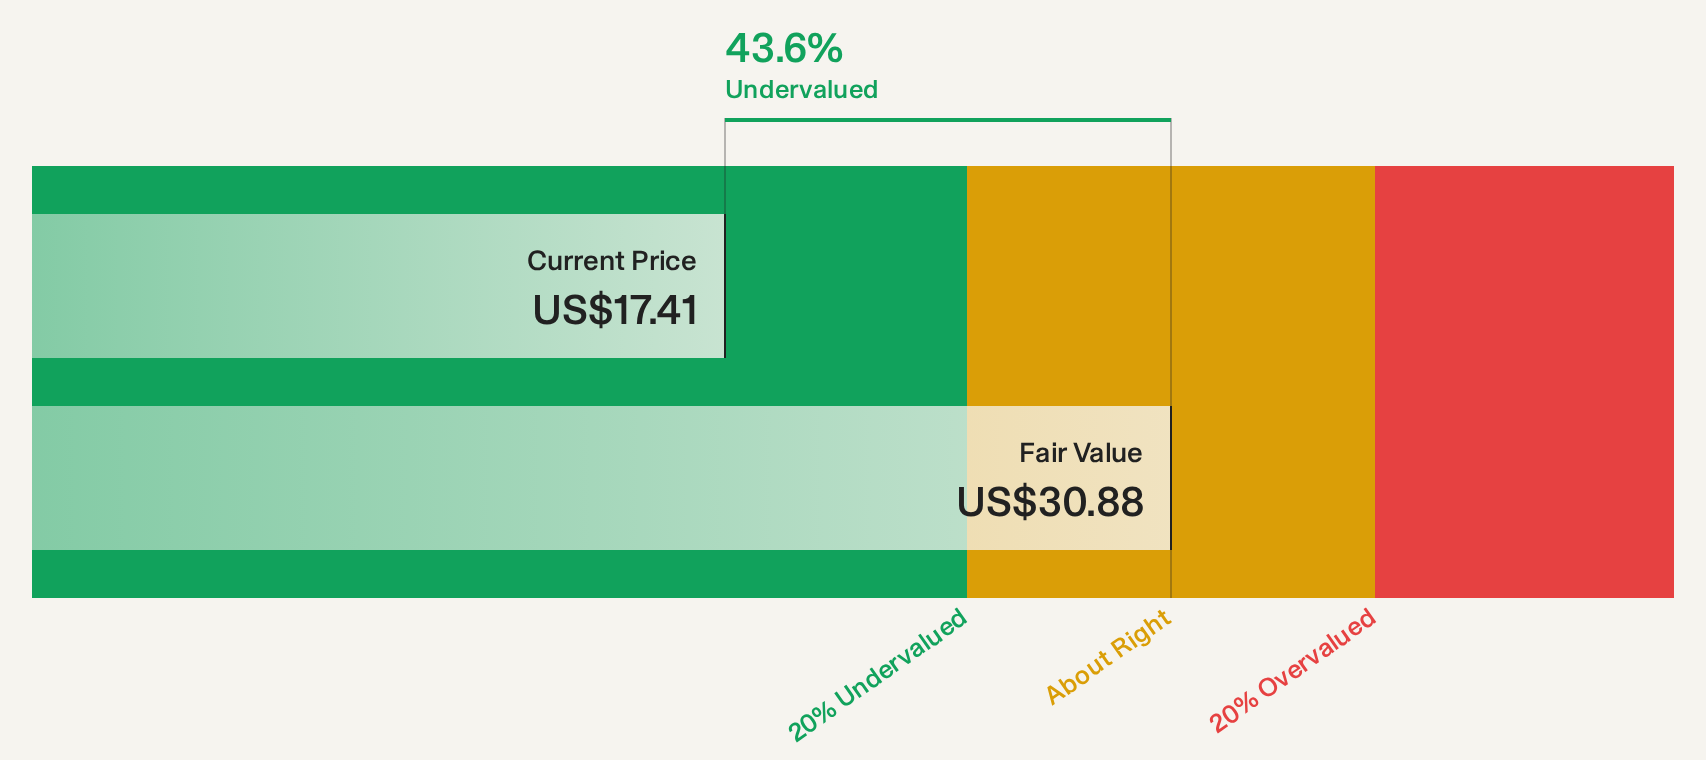
Estimated Discount To Fair Value: 41.5%
Daktronics, trading at US$20.6, is undervalued with a future cash flow value estimated at US$35.24. Despite slower revenue growth forecasts of 7.3% annually compared to the market's 13.3%, its earnings are expected to grow significantly by 23.6% per year, outpacing the broader market's growth rate of 17%. Recent strategic realignments in manufacturing aim for efficiency and cost savings, potentially enhancing profitability and supporting long-term cash flow improvements.
- The analysis detailed in our Daktronics growth report hints at robust future financial performance.
- Get an in-depth perspective on Daktronics' balance sheet by reading our health report here.
Hanmi Financial (HAFC)
Overview: Hanmi Financial Corporation, with a market cap of $945.84 million, operates as the holding company for Hanmi Bank, offering business banking products and services in the United States.
Operations: The company generates revenue of $277.92 million from its banking segment, which includes business banking products and services in the United States.
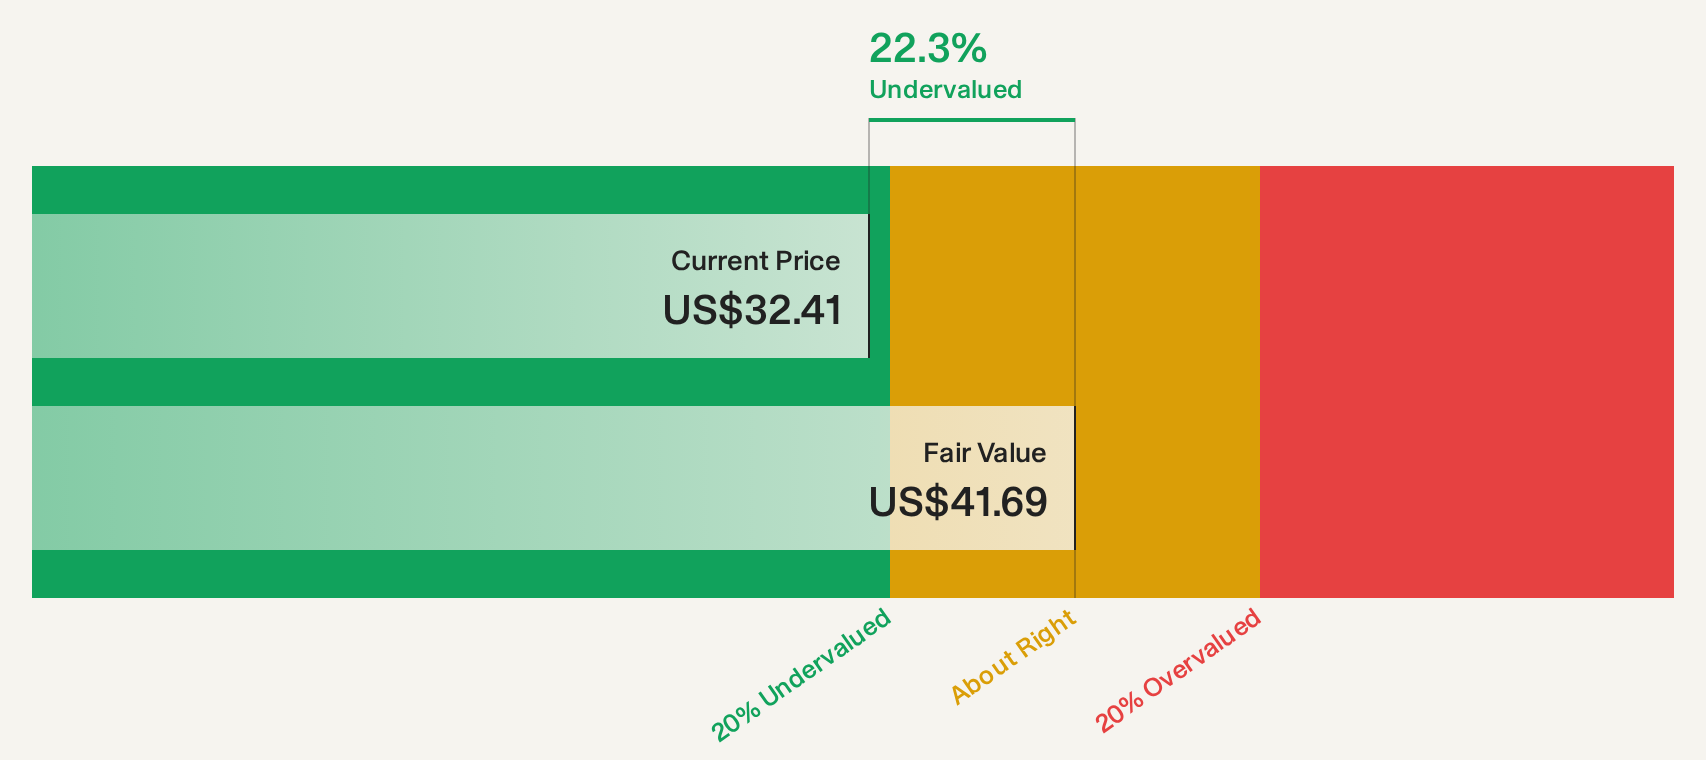
Estimated Discount To Fair Value: 22.9%
Hanmi Financial, priced at US$32.15, is undervalued with a future cash flow value of US$41.72. While its earnings grew by 36.8% last year, future growth is forecast at 7.4% annually, slower than the market's 17%. Despite this, it trades at a good relative value compared to peers and industry standards. The company recently closed a US$55 million private placement for debt refinancing and general purposes, potentially strengthening its financial position.
- The growth report we've compiled suggests that Hanmi Financial's future prospects could be on the up.
- Take a closer look at Hanmi Financial's balance sheet health here in our report.
Where To Now?
- Take a closer look at our Undervalued US Stocks Based On Cash Flows list of 89 companies by clicking here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com