


EN
Will Crude Rebound Change Inpex Shares Narrative
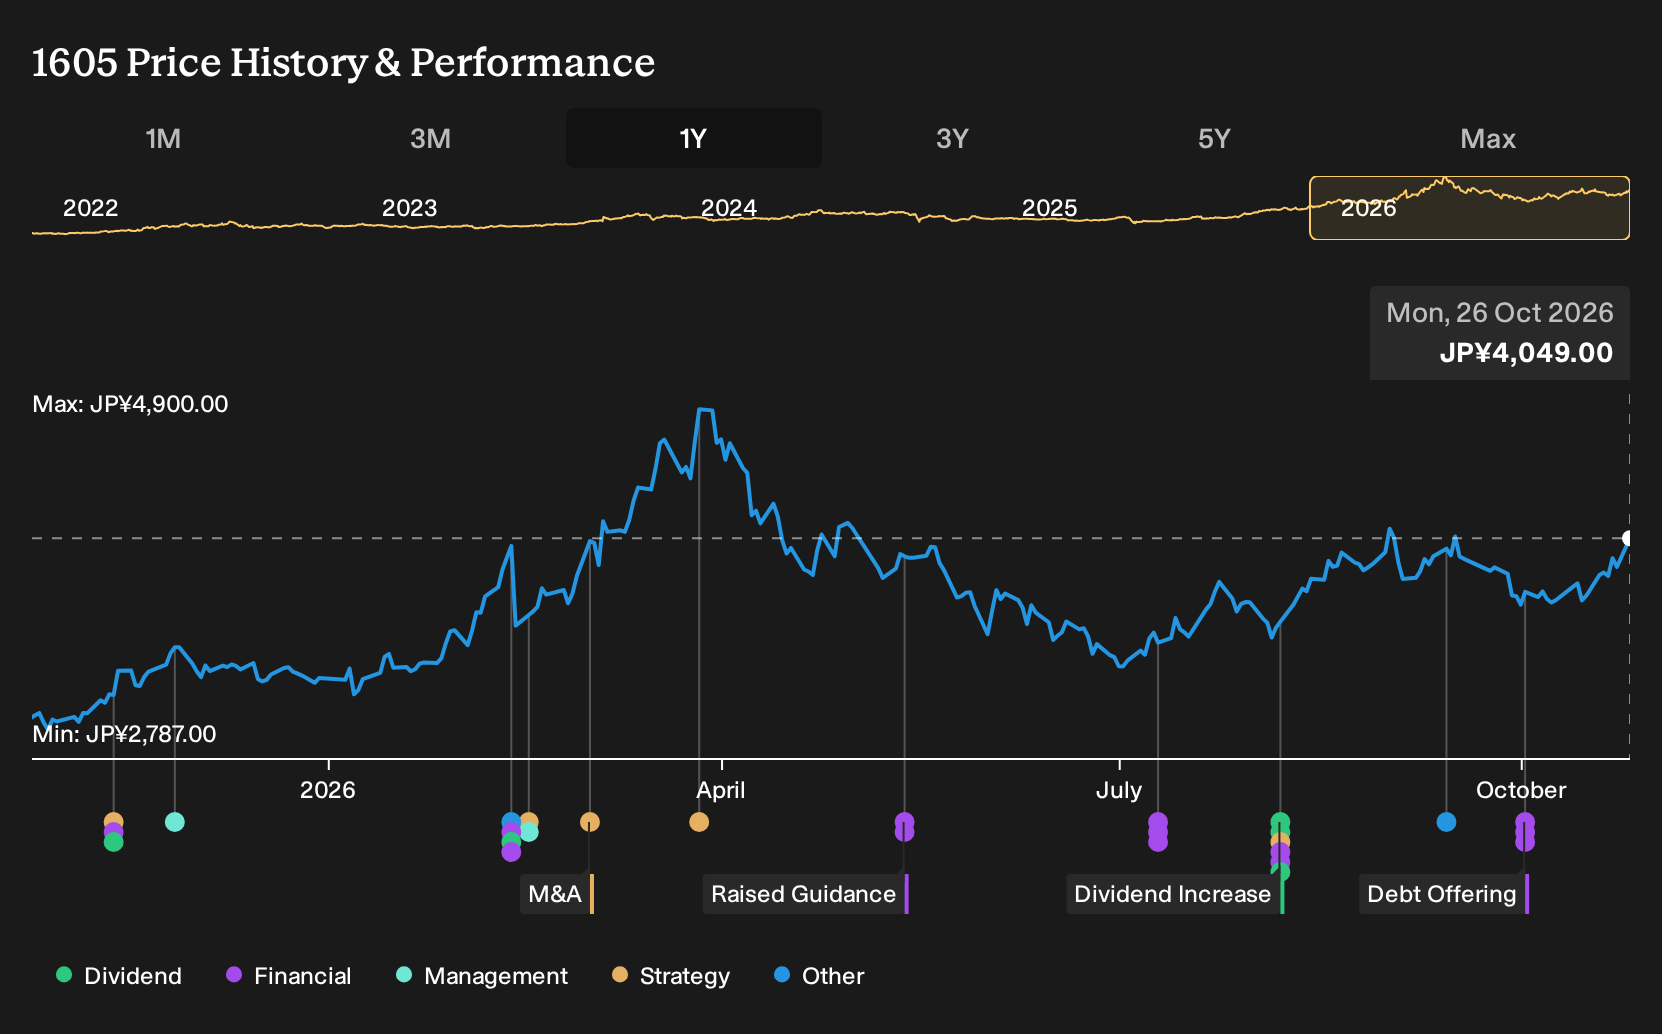
- Inpex participated in a broad upswing for oil drillers after crude prices strengthened and Asian equity markets reassessed energy-related valuations.
- The move coincided with an uptick in Japan's leading economic index, which points to a more supportive backdrop for Inpex's domestic energy demand.
- We will now look at how Inpex's investment narrative could be influenced by the stronger crude backdrop and improving Japanese indicators.
Scan how other energy plays are reacting to the same crude rebound by comparing Inpex with a hand picked group in the 42 power grid technology and infrastructure stocks
Inpex Investment Narrative Recap
To own Inpex, you need to be comfortable with an upstream producer whose fortunes are tightly linked to LNG and crude pricing, as well as to large project execution. The crude rebound and stronger Japanese leading index mainly reinforce the near term demand picture rather than rewrite it. The key short term swing factor remains commodity prices, while the largest risk is execution or cost pressure on major LNG developments and low carbon projects.
Short term earnings expectations currently point to a decline of about 3.1% a year over the next three years, which keeps the focus on efficiency and capital discipline. In that context, today’s move in the share price looks more like a sentiment shift than a clear change in fundamentals, at least until investors see firmer evidence on volumes, project timing and returns from new energy initiatives.
There have been no fresh company specific announcements tied directly to this crude move. The most relevant context is Inpex’s existing guidance and analyst expectations on its long life LNG and upstream portfolio. Those projects, including Ichthys and Abadi, are already embedded in how the market thinks about cash flow, and the recent news primarily affects assumptions on pricing rather than project scope.
Against that backdrop, the main operational question for you is whether current energy prices and Japan’s improving indicator support the case that Inpex can offset forecast earnings pressure while funding low carbon investments and dividends. The stock’s P/E of 10.9x, below the broader JP market but above some peers and an internal fair multiple, underlines how closely investors are watching execution and future cash generation rather than today’s price move alone.
Inpex's current analyst narrative points to revenues of ¥2,226.5b and earnings of ¥432.7b by 2029, based on forecast top line growth of 4.1% a year and an earnings increase of about ¥55.7b from ¥377.0b today.
Uncover why Inpex's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing one clear risk today around Ichthys labour and policy flare ups, yet the most optimistic Inpex analysts were focused on growth instead. Before this crude driven jump, they were modelling revenue of about ¥2,586.8b and earnings near ¥509.7b by 2029, so their pre news optimism may shift as views update.
Explore 2 other Inpex fair value estimates, including one that suggests as much as 23% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Inpex research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Inpex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Inpex's overall financial health at a glance.
Looking for more investment ideas beyond Inpex?
Once you have a view on Inpex, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. That way you are not relying on a single stock to carry your whole energy or income view.
- For investors who care most about valuation support and quality, consider scanning a 14 high quality undervalued stocks that scores well on both fundamentals and pricing.
- If capital preservation sits high on your list, filter for 22 resilient stocks with low risk scores that combine healthier balance sheets with more stable business profiles.
- When you want to widen your watchlist with fresh ideas, run a search across 72 high quality undiscovered gems that might sit off the usual broker radar yet still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com