


EN
Why Sobha Bears Were Right Before The Drop
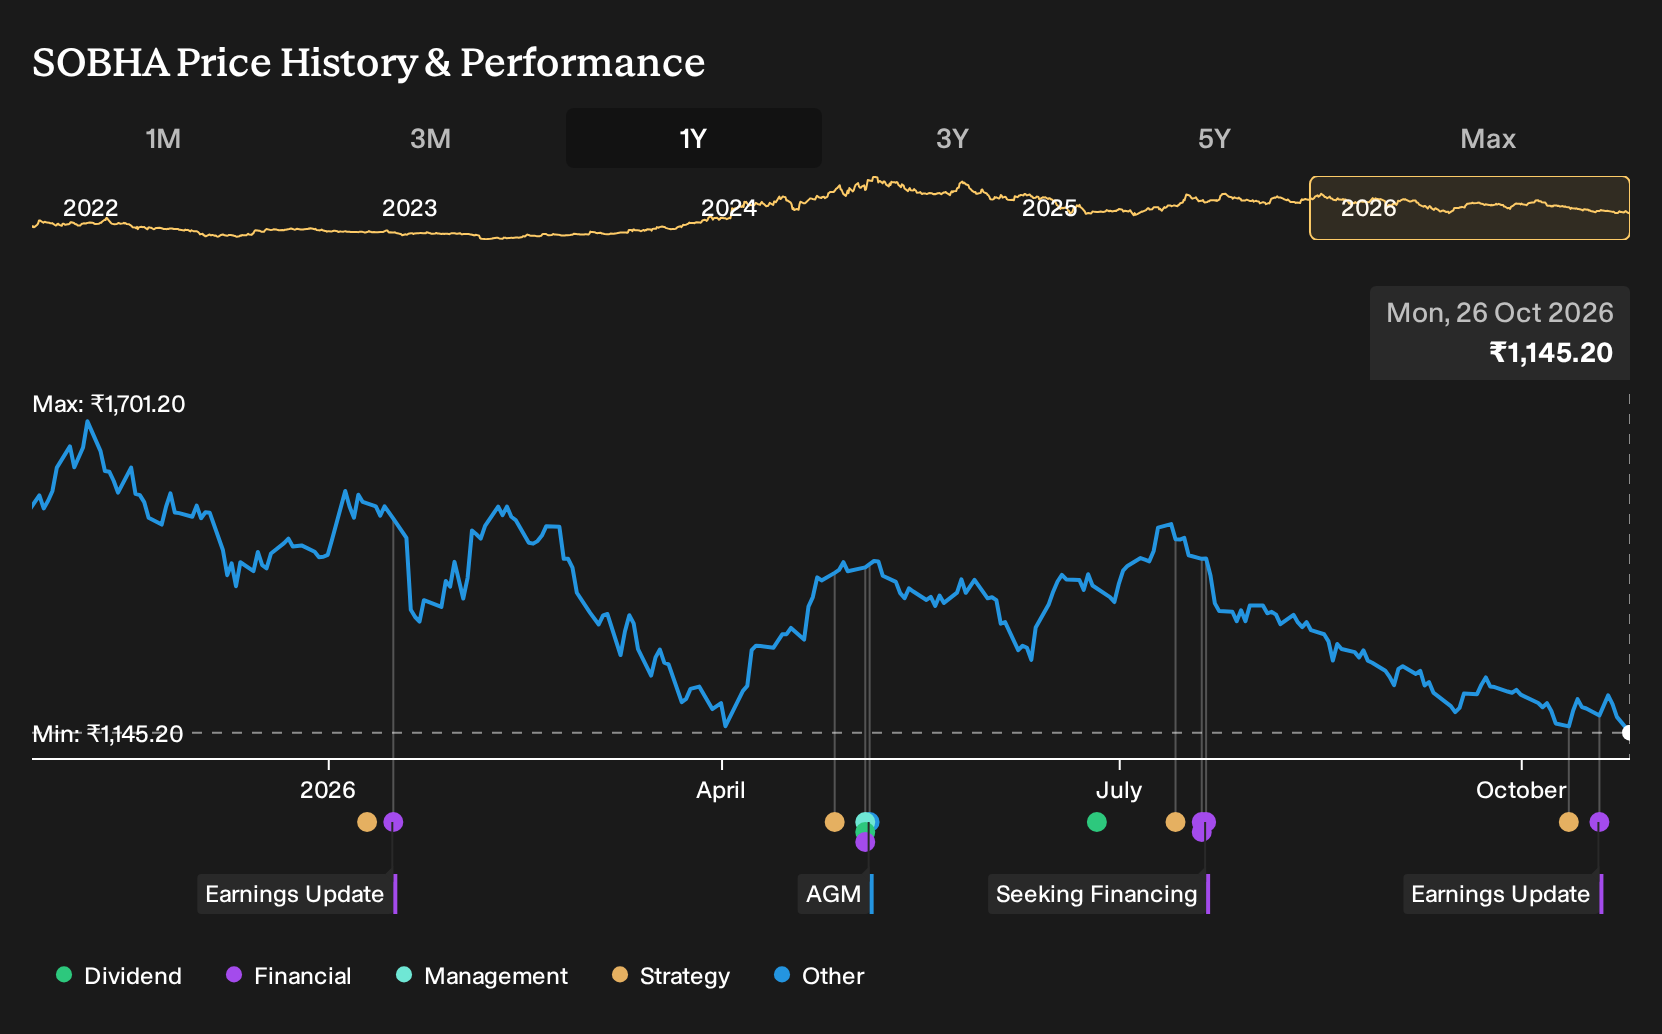
If you only glanced at headline expectations for Sobha in late 2025, with talk of premium launches and margin expansion, the later outcome might feel jarring. Investors who held Sobha over the past year are down 26.7%, including dividends. Then came a new twist. Total revenue of ₹14,076.16m and net income of ₹329.59m in Q2 2027 sat alongside a lower 3.4% net margin. If those were the end points, what clues were visible at the start?
Sobha has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
The Two Sobha Stories Investors Had To Weigh
The shares cost ₹1,535 at the start of the period, and anyone looking at Sobha then had to choose between two very different stories about what might come next.
The bullish view pointed to rapid execution and premium launches and said the stock could justify a Fair Value of ₹2,459. That price would only make sense if faster project rollouts and strong presales kept lifting margins.
The cautious camp argued for a Fair Value of ₹1,200, implying heavier weight on risks such as saturated metro markets, high leverage, and rising compliance and financing costs pressuring profitability.
What The Results Changed For Sobha
The clearest hard fact was the compression in Sobha’s profitability. Net income moved from ₹725.27m in Q2 2026 to ₹329.59m in Q2 2027, and net margin slipped from 5.2% to 3.4%. That challenged the bullish view that premium launches and execution would quickly widen margins.
The lesson for your next property stock is simple. When the upbeat case leans on margin expansion, track net margin and profit side by side against that narrative, and not just revenue or headline project wins.
What You Would Be Paying For In Sobha Today
Sobha now trades at ₹1,145, well below where it started one year ago. The selected Narrative’s Fair Value sits above that price, built on a view that current execution, launch volumes, and cash generation support more than the market is willing to pay today.
That story leans on locked in presales, unrecognized revenue and net cash. For the recent fall to look like an opportunity rather than a warning, a buyer would have to believe Sobha can keep launching projects on time while holding project margins near the levels highlighted in the Narrative.
"The current narrative that Sobha is undervalued implies that the share price does not fully reflect the net cash balance sheet, the large unrecognized revenue book of around INR 20,553 crores with at least 30% expected EBITDA margins, and management’s target of around INR 2,000 crores in annual operating cash flow."
The price and this Narrative do not agree. → Uncover what this Narrative says Sobha is actually worth
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 30% below our estimate - sells work, gaming and collaboration gear that folds AI tools into everyday workflows.
- Company 2 - 46% below our estimate - leans into heavier marketing and staffing so new stores and digital channels carry more weight.
- Company 3 - 23% below our estimate - adds more salespeople to win maintenance contracts that deepen density and support modernization work.
Those are three of them. See the full list of 207 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com