


EN
How Investors May Respond To Viridian Therapeutics (VRDN) FDA Approval For TED Treatment
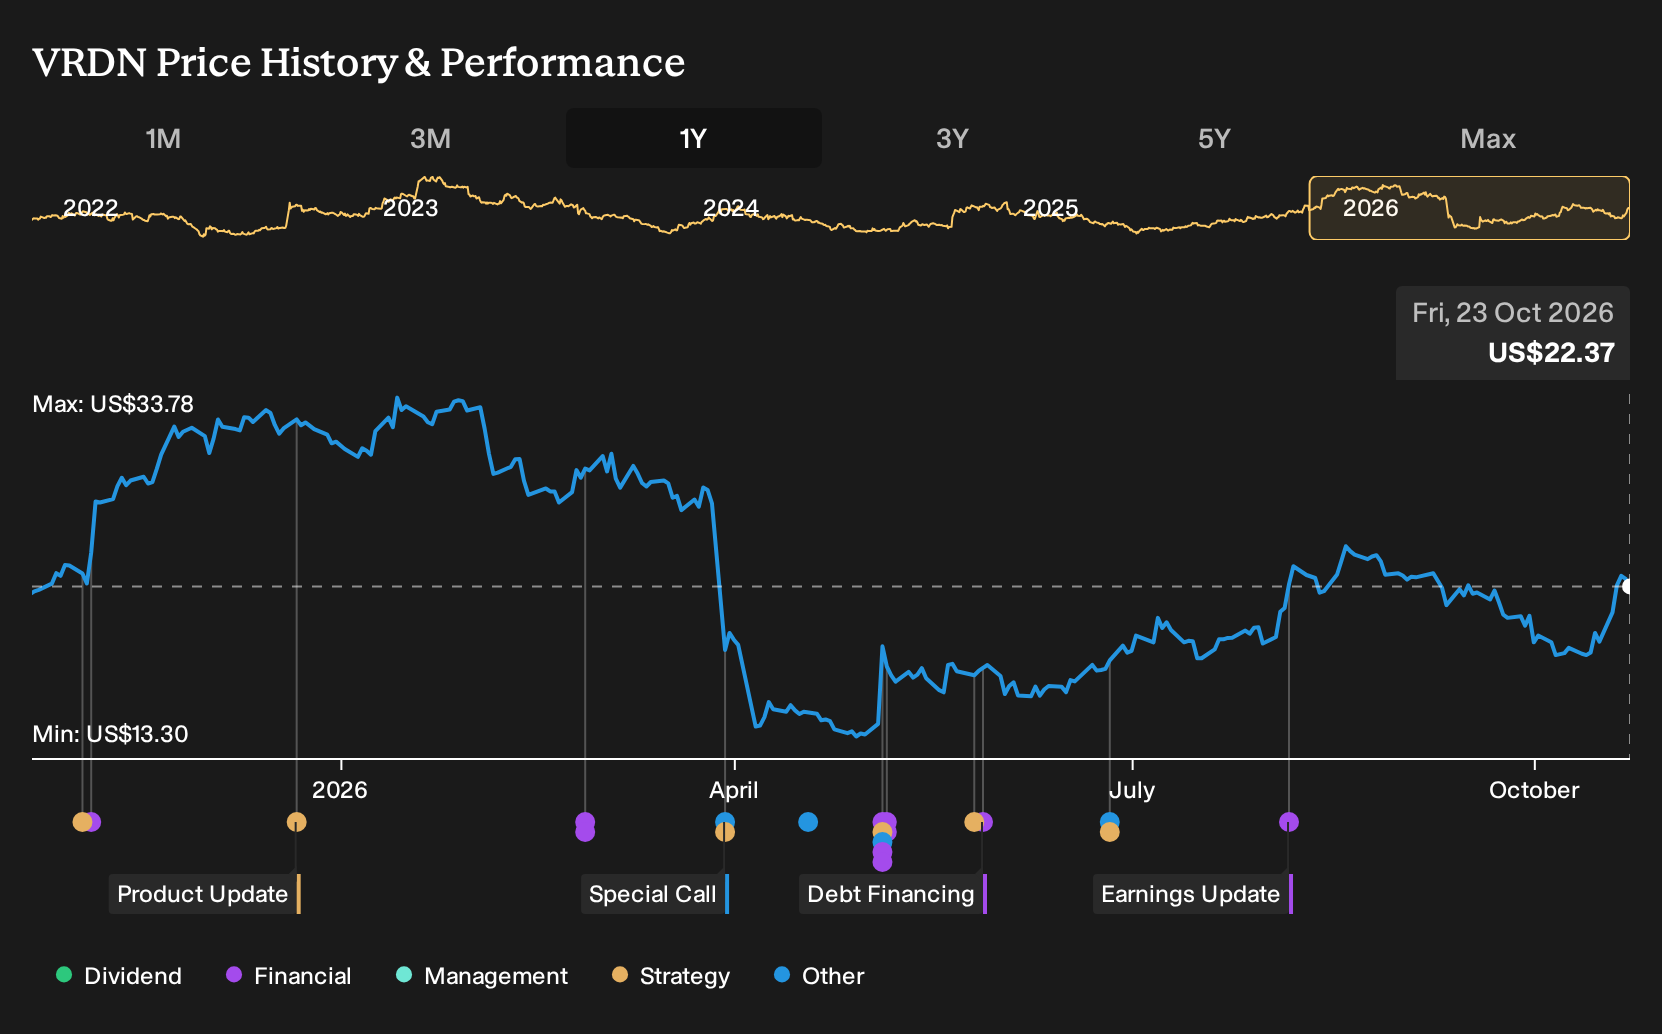
- Viridian Therapeutics received FDA approval in June 2026 for Lumvoa as a treatment for Thyroid Eye Disease, supported by Phase III trial data and a 12 week, 5 infusion IV regimen.
- The approval gives Viridian Therapeutics its first commercial product in an underpenetrated IGF 1R TED market currently estimated at about US$2b, with 6,000 to 7,000 treated patients each year.
- We will now explore how Viridian Therapeutics' investment narrative could shift as Lumvoa's FDA approval becomes the backbone of its TED franchise.
Scan how Viridian Therapeutics fits into the wider opportunity in Thyroid Eye Disease by comparing it with 34 healthcare AI stocks that are riding similar specialty-treatment catalysts.
Viridian Therapeutics Investment Narrative Recap
For an investor to own Viridian Therapeutics, the core belief is that Lumvoa can anchor a focused Thyroid Eye Disease franchise and, over time, turn a currently loss making biotech into a commercial rare disease player. The recent FDA approval is central to that view. It creates the first meaningful revenue stream but also tests how well the commercial model, payer access and prescriber adoption actually work in practice.
In the near term, the key swing factor is execution around Lumvoa uptake in an underpenetrated US$2b IGF 1R TED market, with only 6,000 to 7,000 treated patients each year. The biggest risk is that operating expenses tied to the commercial footprint and pipeline keep margins weak for longer, which could cause investors to question the path from heavy losses to the 11.4% profit margin analysts currently expect within three years.
The Lumvoa approval in June 2026 is the recent milestone that ties closest to Viridian Therapeutics' broader catalyst path. It is not only a green light on the Phase III data and 12 week, 5 infusion IV regimen. It is also the proof point the market uses when thinking about future IGF 1R assets in TED and beyond. That includes the planned BLA for elegrobart, which management has guided for Q1 2027 based on the REVEAL 2 program.
As a shareholder, your attention probably goes to two questions. First, can Lumvoa coverage, buy and bill logistics and a roughly 100 person field force support recurring revenue without costs running away. Second, can elegrobart and other autoimmune programs funded by the recent US$350m plus raises broaden the revenue base before dilution and ongoing losses weigh further on sentiment.
Viridian Therapeutics' narrative projects US$741.1 million revenue and US$84.9 million earnings by 2029. This is in line with analysts assuming 118.4% yearly revenue growth and an earnings swing of about US$418.9 million, moving from a loss of US$334.0 million today to forecast earnings of US$84.9 million.
Uncover why Viridian Therapeutics' fair value indicates a 64% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Viridian Therapeutics focuses on margins rather than just Lumvoa uptake. The most optimistic analysts were modelling revenue rising to about US$1.9b and earnings of roughly US$698.5m by 2029, far above consensus. Those forecasts were set before this FDA approval, so expect opinions to evolve.
Explore 3 other Viridian Therapeutics fair value estimates, including one that suggests as much as 580% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your Viridian Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viridian Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viridian Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Viridian Therapeutics?
Once you have a handle on Viridian Therapeutics, it can help to set it alongside other opportunities and see how it compares on quality, valuation and risk. The Simply Wall St Screener is built for that kind of side by side work, letting you filter for the specific traits you care about rather than just chasing headlines.
- If you want potential upside with tighter downside risk, start with companies that score well on resilience through a 30 resilient stocks with low risk scores screen.
- If balance sheet strength matters most to you, focus on businesses with cleaner debt profiles and healthier cash positions via a list of solid balance sheet and fundamentals (24 results).
- If you are hunting for opportunities the market may not be paying full attention to yet, look through a curated 21 high quality undiscovered gems and see which ones fit your process.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com