


EN
What Embla Medical hf Bears Spotted Before The Slide
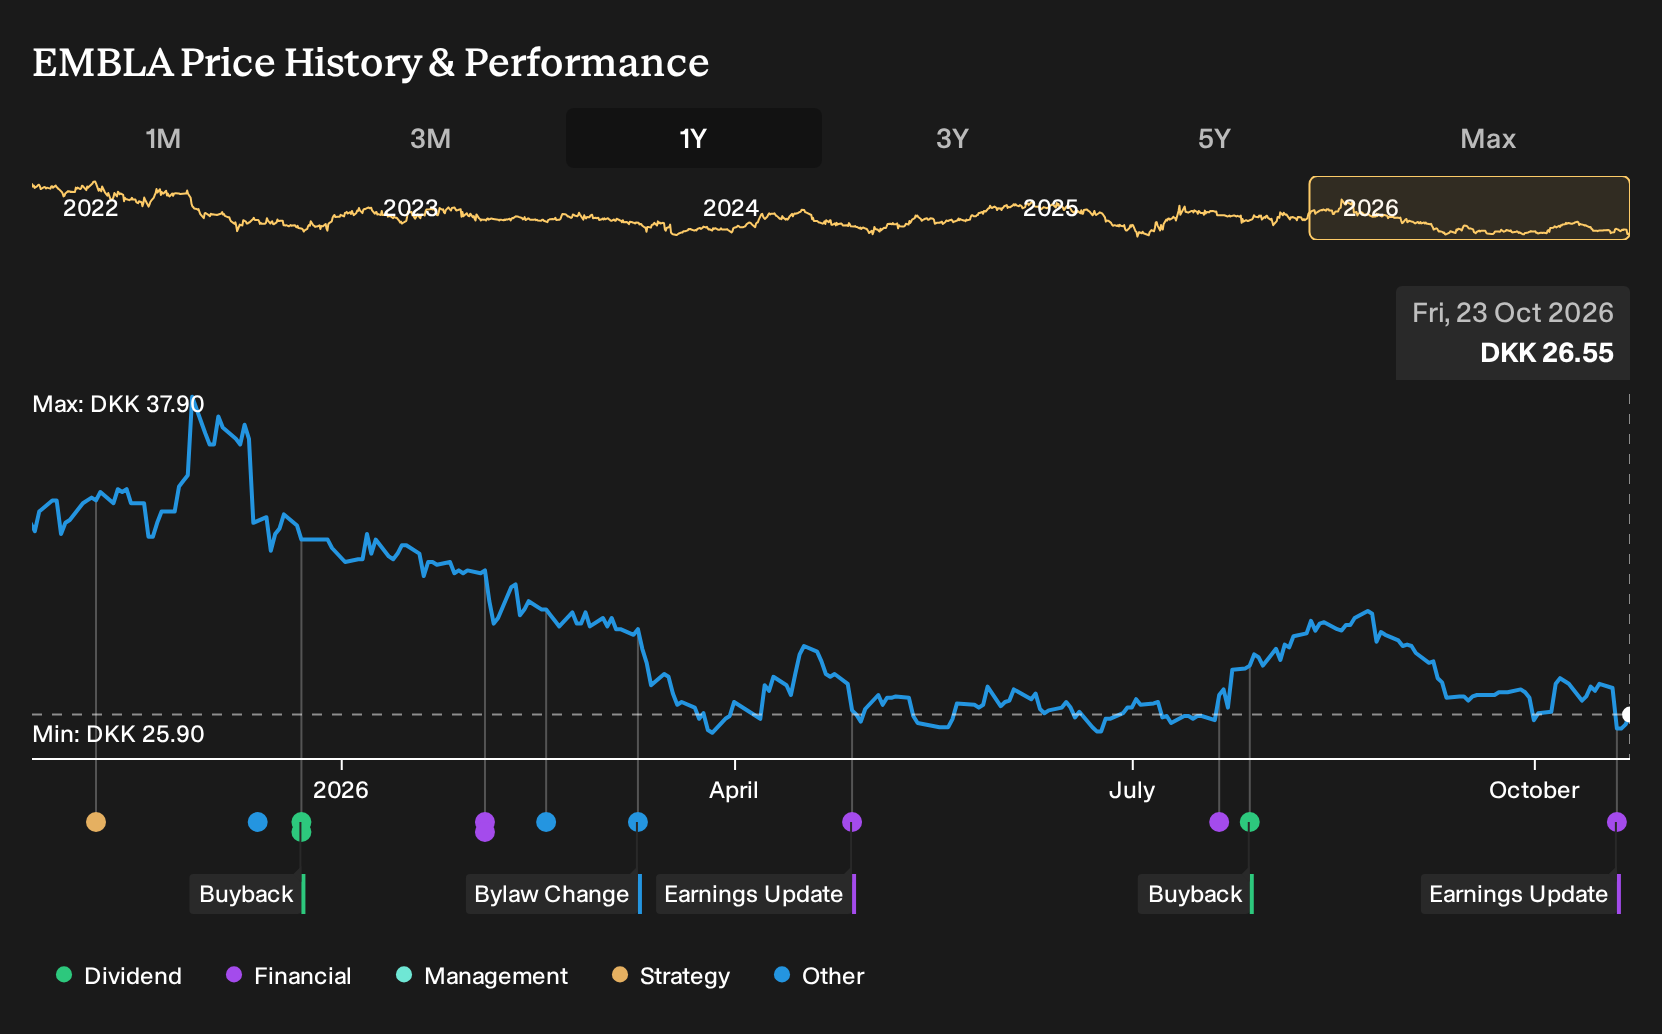
If you had paused on Embla Medical hf in late October 2025, weighing upbeat growth arguments against tariff and regulatory worries, the decision probably felt finely balanced rather than obvious. For Embla Medical hf shareholders, the loss over the past year was 22.4%, including dividends. With that outcome now on the table, which assumption on regulation, tariffs or earnings resilience would you revisit in light of what was already on record back then?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Embla Medical hf has already moved. Pinpoint other ways to investigate the theme among 123 healthcare AI stocks.
The Two Stories Investors Were Weighing On Embla Medical hf
The shares cost DKK33.1 at the start, and Embla Medical hf sat between two sharply different stories about what might come next.
On the bullish side, analysts saw fair value near DKK35.65, based on revenue growth of about 9.2% and profit margins around 10.1% over a 3-year span.
The more cautious view put fair value closer to DKK28, based on 9.3% revenue growth but pressure on margins and a lower future P/E assumption of 20.8x.
What The Results Changed For Embla Medical hf
The key new fact for Embla Medical hf was Q3 2026 trading. Revenue reached US$249.578m and net income came in at US$26.13m, which supported the optimistic case that earnings could hold up. Net margin slipped from 10.9% to 10.5%, which leaned toward the cautious view on profitability. Overall, the evidence cut both ways.
The lesson is simple. When a thesis hangs on margin resilience, do not just watch sales or profit. Track net margin quarter by quarter against the story you were told.
What Embla Medical hf’s Lower Price Now Asks You To Believe
Embla Medical hf trades at DKK26.55 today, and the selected Narrative’s Fair Value sits above that level on its own modelling of the business.
The argument leans on Prosthetics, Neuro Orthotics and clinic execution, so a buyer now would need to believe Patient Care and manufacturing changes can support margins without stalling growth.
"The numbers imply that Embla Medical’s current share price does not fully reflect the cash flow potential suggested by its 5% organic sales growth, roughly 21% EBITDA margin and the external DCF analysis indicating the stock may be significantly undervalued."
One Narrative disagrees with today's price. → See where this Narrative says Embla Medical hf should trade
Another Way To Read Embla
Looking at Embla Medical, you are really asking how aging and chronic disease shape healthcare demand.
One step away, a different group focuses on tools that help doctors spot and manage those conditions earlier.
It leans heavily on tests for blood, tissue and infections, along with sensors that track ongoing treatment in real time.
When hospitals and clinics rely more on those systems, the importance of accurate diagnostics and monitoring quietly grows in the background.
If you are mapping the Embla theme, that expanding toolkit might deserve a closer look next.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com