


EN
Carrier Global (CARR) Commits $600 Million In Fort Worth As Undervalued Narrative Holds
Carrier Global (CARR) just put a big marker down in Fort Worth, committing more than US$600 million to a new advanced manufacturing and engineering hub aimed at supporting increased demand for thermal management and intelligent climate solutions.
Carrier Global shares change hands at US$56.24, with the stock up 5.08% on a year to date share price basis but down 10.96% over the past 90 days. The 3 year total shareholder return of 23.18% and 5 year total shareholder return of 15.45% point to steadier longer run progress than the recent pullback suggests, as investors weigh fresh capital commitments like the Fort Worth expansion against evolving expectations for future risk and reward.
Scan beyond Carrier Global and compare this expansion story with other capital-goods players by reviewing the hand picked 42 power grid technology and infrastructure stocks.
Bulls point to Carrier Global’s US$600 million Fort Worth build and its steady multi year returns. Bears flag the recent share price slide. Which side does the valuation math lean toward next?
Most Popular Narrative: 23% Undervalued
Carrier Global’s most followed narrative pegs fair value at $73.44, comfortably above the recent $56.24 close, which puts the Fort Worth spend into a wider earnings and backlog story.
Carrier Global is building a larger presence in AI and data center cooling, with about $2 billion of 2026 data center revenue already in backlog, an over $8 billion company backlog that is heavily tied to commercial and data center projects, and a dedicated U.S. manufacturing site planned to roughly double Americas data center capacity, which can support future revenue and earnings.
See why 31 investors see Carrier Global as 23% undervalued.
Result: Fair Value of $73.44 (UNDERVALUED)
Still, the Carrier Global story can be knocked off course if margin pressure from tariffs and input costs persists, or if uneven regional demand keeps weighing on mix.
Find out about the key risks to this Carrier Global narrative.
Another View: Carrier Global Looks Expensive On Earnings
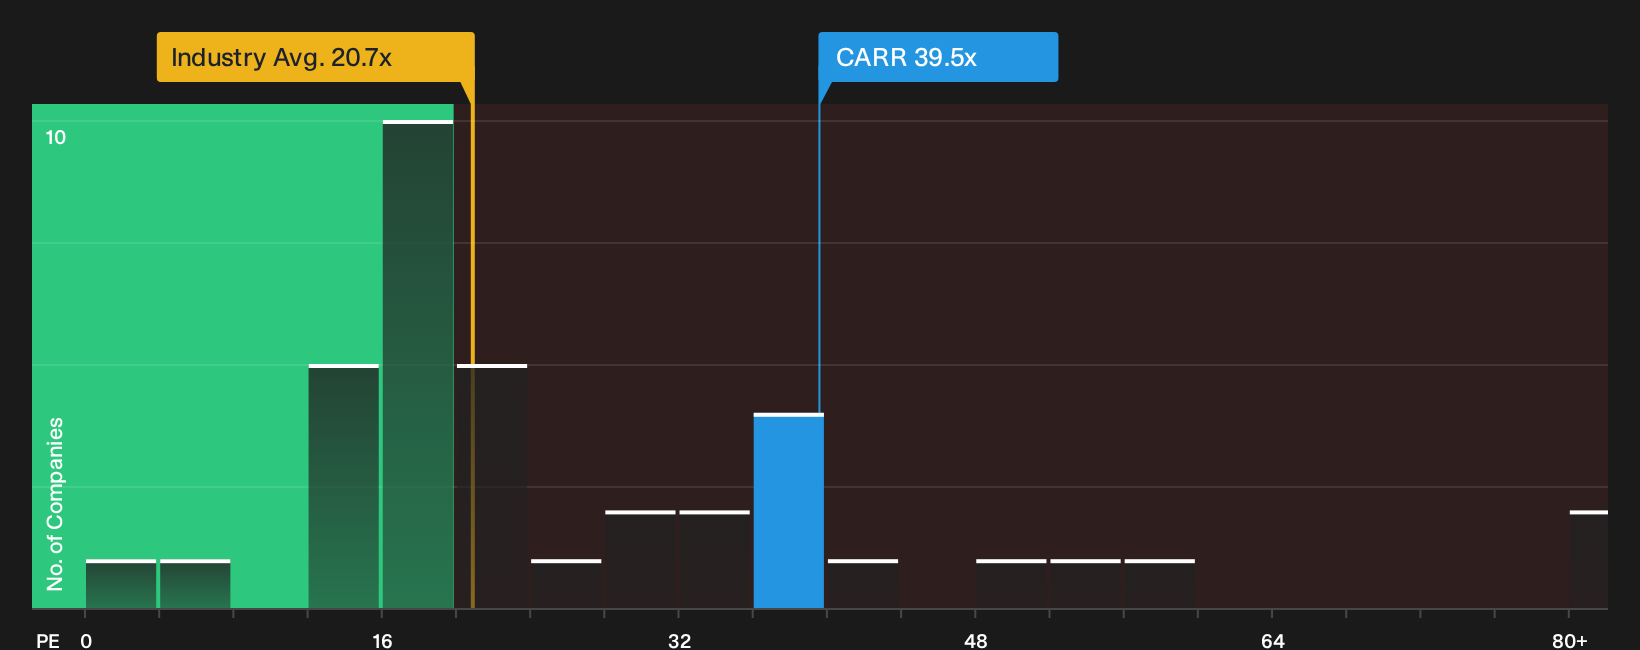
The first story around Carrier Global focuses on a fair value of $73.44 that points to upside. A different lens looks at the current P/E of 39.5x versus a fair ratio of 33.2x and a US Building industry average of 20.7x, which suggests investors are already paying a premium and taking valuation risk if growth or margins disappoint.
Compared with peers on 28.3x, that premium means any slip in the earnings path could compress the multiple faster than the business can grow its way out. The question for you is simple: does the potential upside justify paying well above both the industry and that fair ratio today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Carrier Global so far. If you want to move from headline impressions to your own conviction, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carrier Global?
If Carrier Global has your attention today, do not stop there. Broaden your watchlist now so you are not reacting after the next move is obvious.
- Target steadier compounding by reviewing companies with durable cash flows and pricing power through the 28 high quality undervalued stocks.
- Prioritise resilience by scanning businesses with strong finances and clean balance sheets via the list of solid balance sheet and fundamentals (24 results).
- Spot tomorrow's potential leaders early by checking the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com