


EN
Will Restaurant Expansion Change Macerich (MAC) Narrative
- Macerich reported in October 2026 that it is accelerating restaurant leasing across its Class A shopping centers, bringing first-to-market and experience-focused dining concepts like Eataly, Din Tai Fung, Seafood City and Telefèric Barcelona to high-traffic properties in major U.S. markets.
- The push to turn assets such as Scottsdale Fashion Square, Tysons Corner Center and HiFi at FlatIron Crossing into destination dining hubs signals a heavier tilt toward food, beverage and entertainment tenants that can support occupancy, broaden rent sources and deepen customer dwell times.
- The next area of attention is how Macerich's investment narrative could be affected by this faster rollout of destination and experiential dining.
Scan for other retail REITs leaning into experience-driven traffic by jumping into our handpicked list of 21 high quality undiscovered gems while Macerich pushes deeper into destination dining.
Macerich Investment Narrative Recap
For Macerich, the core belief as a shareholder is that high quality malls in dense markets can stay relevant by leaning into experience led retail, even while e commerce chips away at some traditional spending. The rapid build out of destination dining and entertainment could support leasing momentum and help keep traffic resilient across key assets if execution remains tight.
The key near term swing factor is whether leasing spreads and occupancy hold up as older tenants roll and anchors are reworked. The biggest risk is still the balance sheet. High leverage and interest costs mean that if redevelopment or restaurant openings slip, the financial strain can feel sharper.
The most relevant piece of the recent update is the extensive restaurant and entertainment plan at HiFi at FlatIron Crossing. Management is turning that property into a 25 acre open air district attached to the existing mall, with concepts like Memoir, Blue Sushi Sake Grill, Shake Shack and the Pindustry eatertainment venue.
For you as an investor, this is a clear test case. If HiFi opens in phases from 2027 with strong tenant uptake and solid rent economics, it can reinforce the thesis that Macerich’s experiential focus supports long term net operating income. If leasing or construction costs disappoint, it would underline how capex heavy projects can strain an already leveraged REIT.
Macerich's current analyst narrative points to forecast revenue of US$1.1b and consensus earnings of US$78.8 million by 2029, based on revenue growth assumptions of 3.1% per year and a swing in earnings of about US$249 million from a loss of US$170.4 million today.
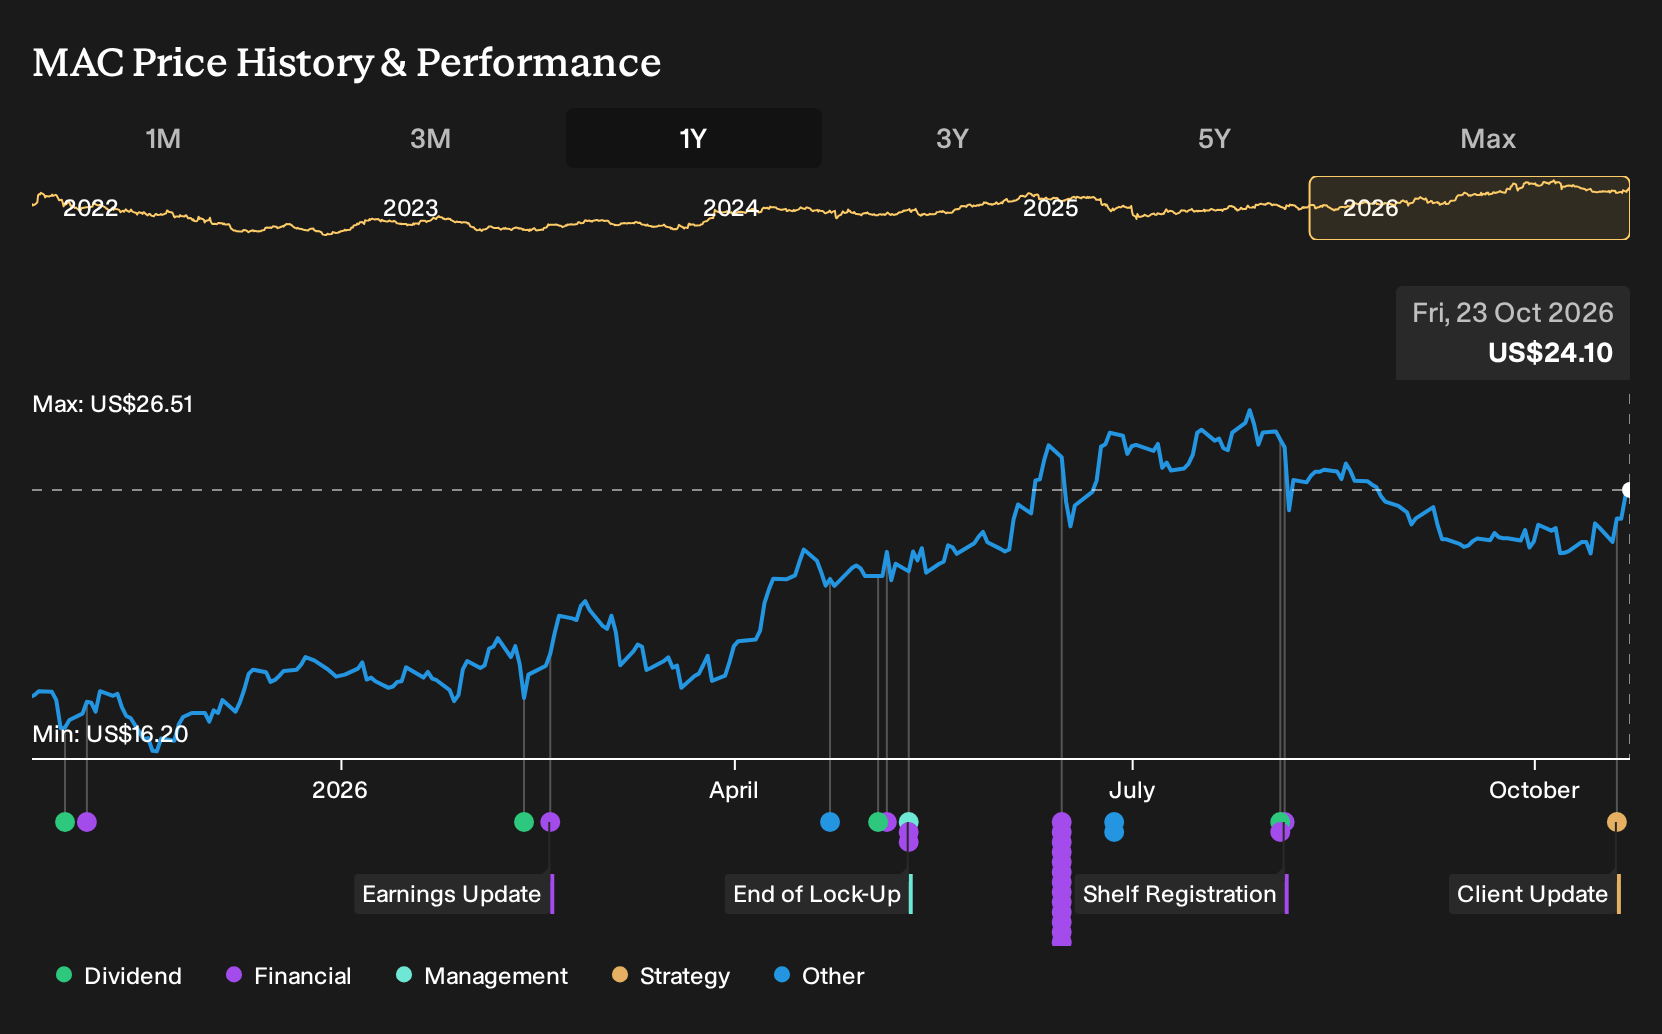
Uncover why Macerich's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Macerich focuses squarely on e commerce pressure. The most bearish analysts see digital spending chipping away at mall traffic and keep forecasts cautious, with revenue expectations closer to US$1.0b and earnings of about US$90.7 million by 2029. Those projections came before this restaurant leasing surge, so their views may shift.
Explore 2 other Macerich fair value estimates, including one that suggests it could be worth just $26.56.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Macerich research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Macerich. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macerich's overall financial health at a glance.
Looking for more Macerich sized investment ideas?
Once you have a view on Macerich, it can help to widen the lens and line it up against other opportunities using the Simply Wall St Screener.
- If you care most about valuation, compare Macerich with companies that score well on both quality and price by reviewing 28 high quality undervalued stocks.
- If resilience matters more than excitement, balance your Macerich view with a 30 resilient stocks with low risk scores that prioritises steadier risk profiles.
- If balance sheet strength is a key filter for you, round out your watchlist with a list of solid balance sheet and fundamentals (24 results) that can sit alongside higher leverage REITs like Macerich.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com