


EN
What to Expect From CF Industries’ Next Quarterly Earnings Report
CF Industries Holdings, Inc. (CF) is a major producer of ammonia and nitrogen-based products used in agriculture, energy, and industrial applications. The company operates manufacturing facilities across the United States, Canada, and the United Kingdom, supported by an extensive storage, transportation, and distribution network in North America and international logistics capabilities. Its operations focus on maintaining safety, reliability, and environmental responsibility while managing capital efficiently.
CF Industries is also working to reduce the carbon intensity of its ammonia production network and expand its role in low-carbon hydrogen and nitrogen products, which serve applications ranging from fertilizer production to emissions reduction and clean energy. Currently valued at a market capitalization of about $18.26 billion, CF Industries is gearing up to reveal its fiscal 2026 third-quarter results after market close on Wednesday, Nov. 4.
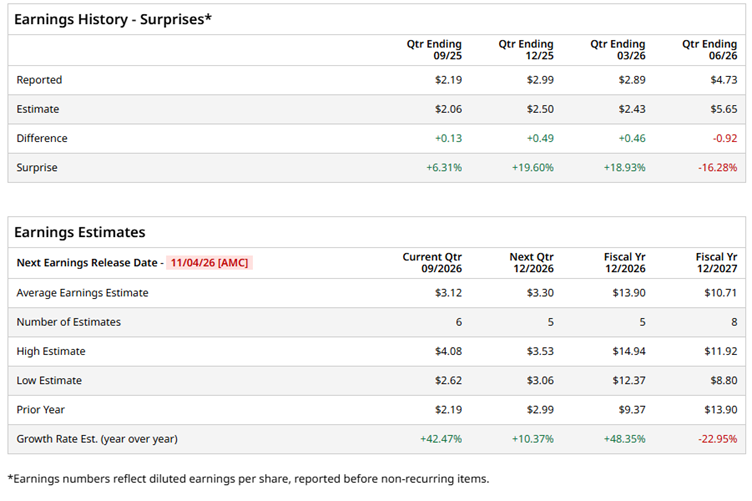
Wall Street expects CF Industries to deliver strong year-over-year earnings growth in its upcoming quarterly report, with EPS forecast to reach $3.12, up 42.5% from the year-ago quarter. However, the company’s recent track record has been somewhat uneven, beating analysts’ estimates in three of the past four quarters and missing expectations once. Looking further ahead, analysts project fiscal 2026 EPS to surge 48.4% year over year to $13.90. However, this momentum is expected to moderate in fiscal 2027, with earnings projected to decline 23% to $10.71 per share.
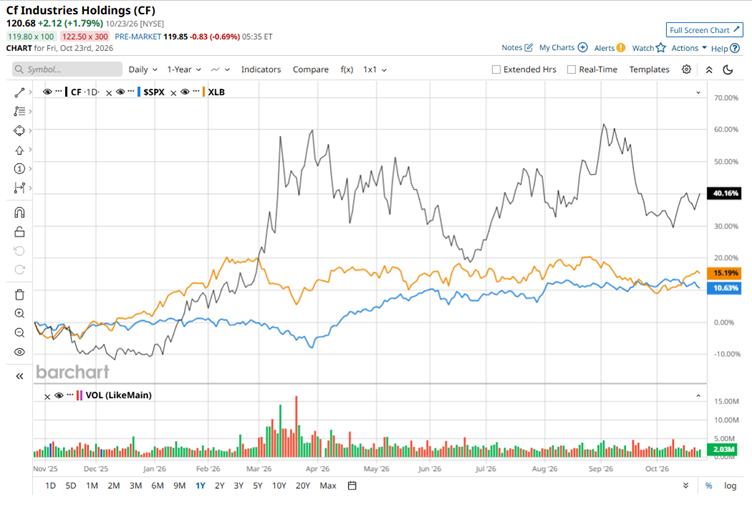
CF Industries has delivered an impressive performance over the past year, with its shares climbing 38.8% and comfortably outpacing the broader market and its materials-sector peers. In comparison, the S&P 500 Index ($SPX) gained 13.4%, while the State Street Materials Select Sector SPDR ETF (XLB) advanced 16.1% over the same period, highlighting CF Industries’ strong relative performance.
CF Industries delivered solid year-over-year growth in its fiscal 2026 second-quarter results, reported on Aug. 5, 2026, with revenue climbing 17.6% to $2.22 billion and diluted EPS nearly doubling, surging 99.6% to $4.73. However, earnings fell short of Wall Street’s expectations of $5.65 per share, tempering an otherwise strong performance. Despite the earnings miss, the company maintained robust momentum through the first half of the year, generating approximately $2.2 billion in adjusted EBITDA. Continued shareholder returns and a favorable outlook for global nitrogen demand further supported its financial position.
Despite CF Industries’ strong stock performance, Wall Street remains divided on its outlook, with analysts maintaining a consensus “Hold” rating. Of the 20 analysts covering the stock, four recommend a “Strong Buy,” 13 favor a “Hold,” one assigns a “Moderate Sell,” and two issue a “Strong Sell.” The average price target of $121.90 suggests limited upside from current levels. However, the most bullish analyst sees considerably greater potential, with a Street-high target of $162 implying a possible gain of up to 34.2%.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.