


EN
Dow Futures Stall Below 53000 as Oil Hits a Six Month High: Breakout or Breakdown?
Crude Climbs, Yields Bite: The Forces Pulling on the Dow
YM futures are trading as a macro driven market, and oil has been the dominant force. As of October 23, Brent crude settled at $116.72 per barrel and WTI settled at $103.27, with Brent posting its third consecutive weekly gain as investors priced in the risk of renewed U.S. strikes on Iran. President Trump said on October 21 that the U.S. was not negotiating with Iran and that something would happen fairly soon, while U.S. officials told The New York Times that the U.S. and Israel have plans for fresh strikes after the midterm elections. Shipping risk has added fuel, with at least 18 ships reported hit in the Strait of Hormuz over a two-week period as of October 23.
Rates are the second pressure point. As of October 23, the 10-year Treasury yield stood at 4.99%, up from 4.96% the prior day, and U.S. inflation remains well above 3%. The Fed raised rates at its last meeting. Markets expect a hold next week but lean toward another hike in December. September PCE inflation, expected at 3.7%, is also due next week.
Equity flows reinforced the pressure. As of the October 23 close, the Dow fell 1.2% to 52,215.16, underperforming the S&P 500 (down 0.5%) and the Nasdaq (down 0.2%). AI related names such as Micron and Microsoft held up, while Dow heavyweights tied to growth and credit led the decline, including Caterpillar (down 2.4%), American Express (down 3.7% after announcing its first major job cuts in roughly a decade) and JPMorgan (down 1.5%). Chevron gained 2.9% on higher crude. Alphabet, Microsoft and Amazon report next week, so AI spending concerns remain a swing factor for index direction.
What the Market Has Done
- At the start of August, the market made new ATHs; however, it failed to accept higher and fell back into the range between 53650 (Daily level 1) and 51630 (Daily level 2).
- Subsequently, at the end of September, the market breached below 51630 (Daily level 2), and sellers attempted to follow through to the downside. However, they were unable to, which resulted in prices reclaiming back into the range.
- As of October 23, the market has reclaimed up to 53000 (Minor level 1), where some responsive selling is seen. Consequently, this level is the immediate decision point.
What to Expect in the Coming Weeks
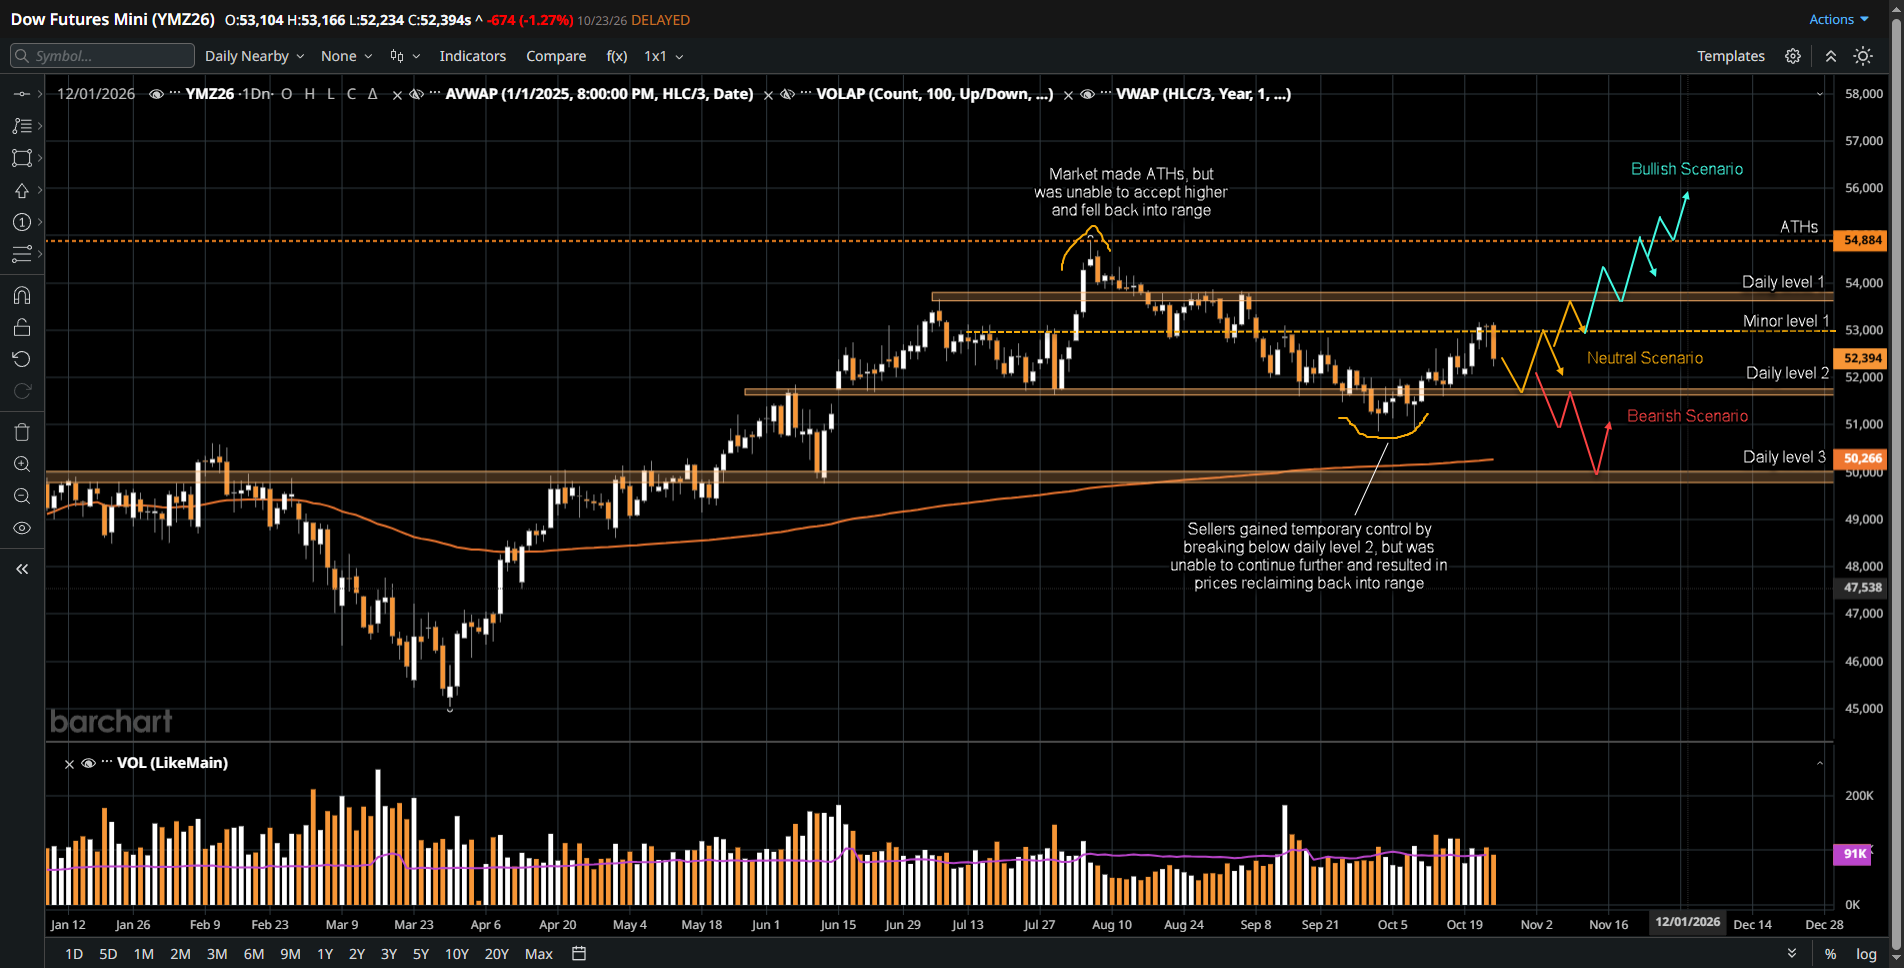
The key levels to watch are 53000 (Minor level 1) and 51630 (Daily level 2). The scenarios below are framed for the next few weeks to a month.
Neutral Scenario
- If sellers hold offers at 53000, and buyers defend 51630, expect a balanced rotation in both directions to build value before a subsequent directional resolution.
- A possible supporting condition for this scenario is oil holding in a choppy, elevated range while the Fed holds rates next week without committing to a December path, leaving neither inflation fears nor growth optimism in control.
Bullish Scenario
- An initial clue that the bullish scenario might be in play is buyers holding bids at 53000 after a move up to 53650 (Daily level 1) and a pullback.
- If buyers break and accept above 53650, expect a possible move up to revisit 54884 (ATHs), and possibly a move beyond that to make new ATHs.
- A possible trigger is a diplomatic step back from the brink on Iran that eases Hormuz shipping risk and pulls crude lower, alongside a softer than expected PCE reading and mega-cap earnings that calm AI spending concerns.
Bearish Scenario
- If buyers fail to defend 51630, expect a possible move down to 51000 (prior swing low, where sellers failed to follow through to the downside), where responsive buyers can be expected.
- If sellers step down offers to 51630 and buyers fail to respond at 51000, expect a possible move down to 50000 (Daily level 3).
- A possible trigger is renewed U.S. and Israeli strikes on Iran that send Brent sharply higher, combined with a hot PCE print that cements a December rate hike and pushes the 10-year yield higher.
Conclusion
Technically, YM remains inside the range between 53650 (Daily level 1) and 51630 (Daily level 2), with 53000 (Minor level 1) as the pivot that will likely set the tone. Fundamentally, as of October 23, oil near a six-month high, a 10-year yield near 4.99%, next week’s Fed meeting and PCE data, and mega-cap earnings are all converging on that same pivot. Which force will win the tug of war, geopolitics or the Fed? Share your thoughts in the comments.
EdgeClear is designed for traders who refuse to guess. We deliver unfiltered tick data via Rithmic, competitive pricing starting at $0.22 per side, and performance analytics that transform your trade log into a roadmap. The serious trader’s next move is clear. Open an Account today.
Disclaimer:
This article is provided for informational and educational purposes only and does not constitute financial, investment, or trading advice. The analysis presented reflects the author’s market observations and opinions at the time of writing and is not a recommendation to buy or sell any futures contract, security, or financial instrument. Futures trading involves significant risk and is not suitable for all market participants. Losses may exceed initial margin deposits, and market conditions can change rapidly.
Any scenarios, levels, or market expectations discussed are hypothetical in nature and are intended solely to illustrate potential market behavior. They do not represent actual trading results and should not be interpreted as guarantees of future performance. Past performance, market behavior, or historical price action are not indicative of future outcomes.
Readers are solely responsible for their own trading decisions and risk management. Always conduct independent research, consider your financial situation and risk tolerance, and consult with a qualified financial professional, if necessary, before engaging in futures or derivatives trading.