


EN
Sandisk Earnings Preview: What to Expect
Sandisk Corporation (SNDK), headquartered in Milpitas, California, is a data storage technology company specializing in NAND flash memory and solid-state drives (SSDs), with a market capitalization of approximately $178.9 billion. The company develops products that provide high-capacity, energy-efficient data storage for smartphones, PCs, cloud infrastructure, and AI systems, supporting modern computing and data-intensive workloads.
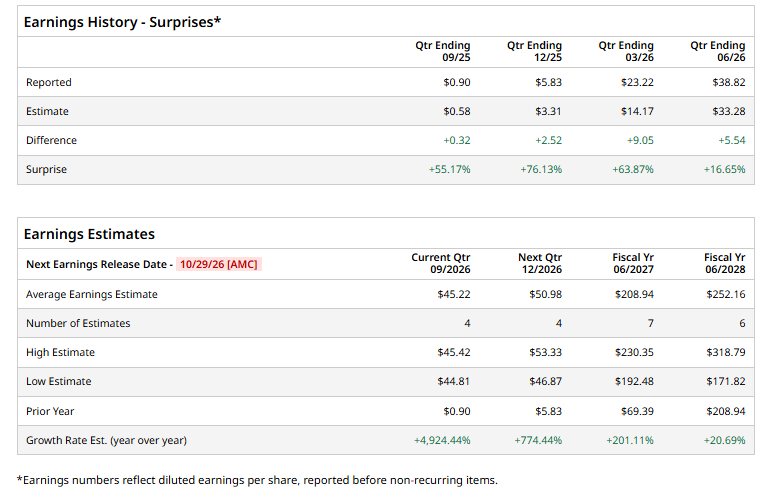
SNDK is set to report its fiscal 2027 Q1 earnings on Thursday, October 29, 2026, after the market closes. Ahead of the release, analysts expect the company to report diluted EPS of $45.22, up a staggering 4,924.4% from $0.90 in the year-ago quarter. Moreover, SNDK has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
For fiscal 2027, analysts expect SNDK to report EPS of $208.94, reflecting a substantial 201.1% increase from $69.39 in fiscal 2025. Furthermore, its EPS is projected to increase by another 20.7% year over year to $252.16 in fiscal 2028.
SNDK stock has surged 641.1% over the past 52 weeks, significantly outperforming the S&P 500 Index ($SPX), which returned 13.1%, and the State Street Technology Select Sector SPDR ETF (XLK), which gained 26.8% over the same period.
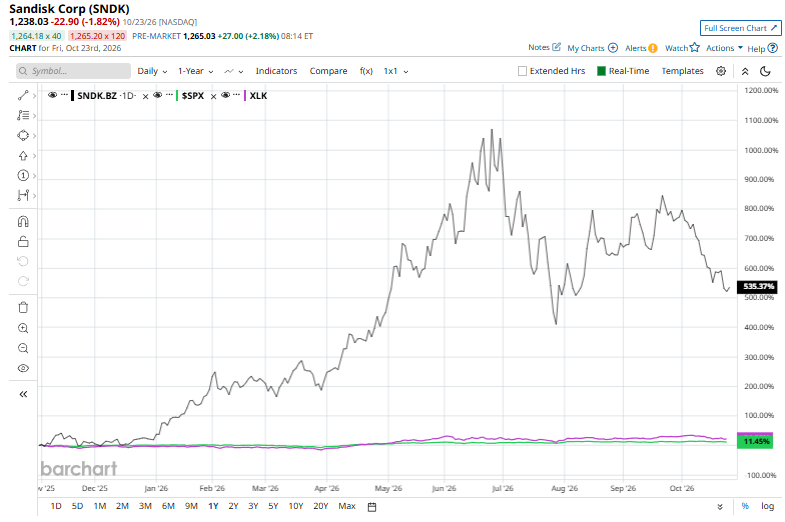
Sandisk’s outperformance has been driven by the AI infrastructure boom, which is fueling demand for NAND flash memory used in enterprise solid-state drives (SSDs). The company’s fiscal Q4 revenue surged 372% year over year to $8.97 billion, with higher pricing accounting for about two-thirds of the sequential increase. Growing data center demand, higher-value storage sales, improved visibility from longer-term customer contracts, and disciplined supply expansion have strengthened investor confidence that SanDisk’s revenue growth and pricing power could prove more durable than in previous memory cycles.
Analysts remain strongly bullish on SNDK, with a consensus “Strong Buy” rating. Of the 25 analysts covering the stock, 21 recommend a “Strong Buy,” one rates it a “Moderate Buy,” and three suggest a “Hold.” Meanwhile, the average analyst price target of $2,154.17 implies potential upside of 74% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.