


EN
3 European Energy Stocks To Watch As Gas Prices Stay High
Energy prices are back in the spotlight as European gas benchmarks hit four year highs, oil remains supported by Middle East risks, and storage levels sit below seasonal norms. That combination can squeeze households and energy heavy businesses, yet it can also shift the earnings power of companies tied to supply, trading and production. This article examines three European energy stocks exposed to these moves and explains how that exposure could affect investors this winter.
The three stocks covered below are only a small sample of the idea, and the full screen surfaced 24 more European integrated oil, gas and diversified energy producers with similarly rich storylines that are not covered in this article. To see the broader opportunity set in one place, head straight into the European Integrated Oil & Gas and Diversified Energy Producers screener to identify, compare and analyze potential high conviction ideas across the group.
Gas Plus (BIT:GSP)
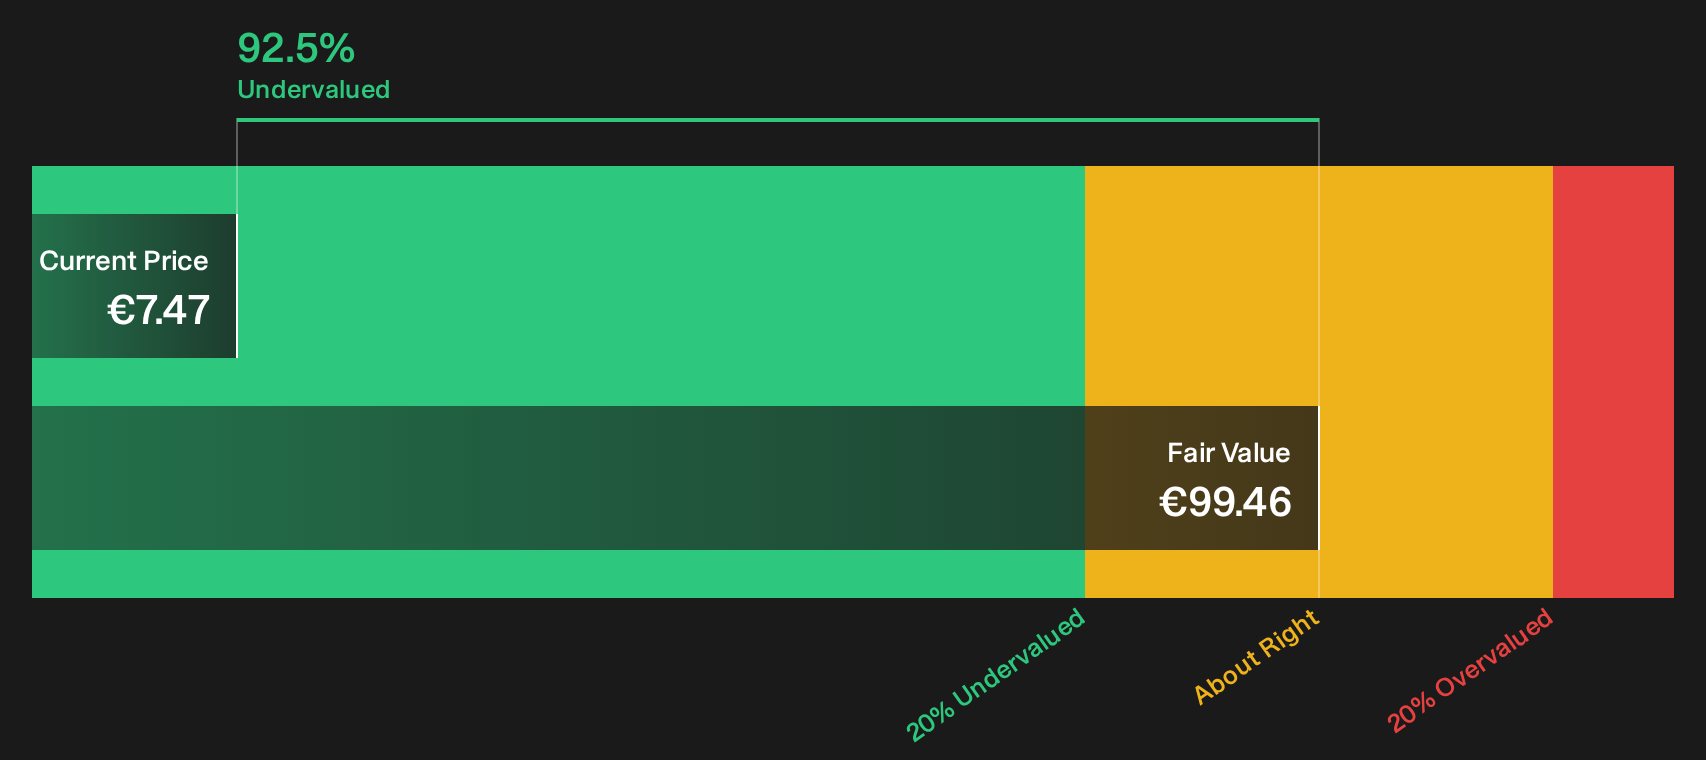
Gas Plus is an Italian natural gas extractor, distributor and seller that fits the screener’s focus on European upstream and midstream gas exposure. Most revenue comes from segment adjustments of about €150 million, with retail at roughly €38 million and network and transportation near €17 million. The stock has a market value of about €325 million.
Gas Plus links investors directly to Italian wholesale gas pricing, with upstream extraction, transport, storage and retail activities all tied to European supply and demand. Recent revenue of €90.46 million and net income of €15.88 million describe earnings power that could change if a single pressure on gas pricing and margins moves even slightly.
If you want to see how that earnings sensitivity could play out across different scenarios, review the DCF valuation analysis for Gas Plus to see what the market might be missing.
Ithaca Energy (LSE:ITH)
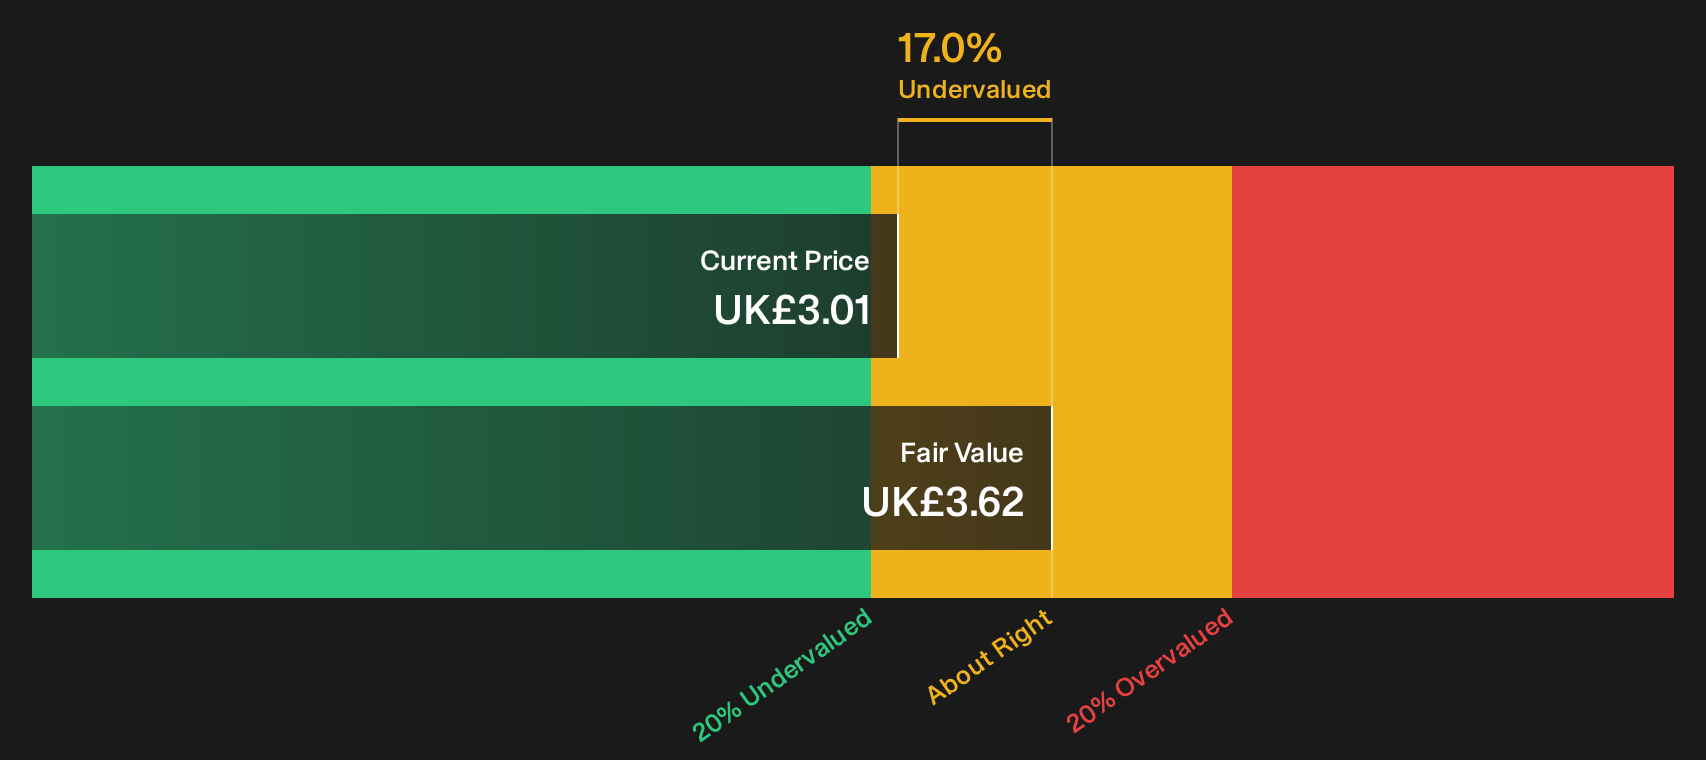
Ithaca Energy gives this screener direct North Sea production exposure, with all of its $3.19b in oil and gas revenue coming from exploration, development and production activities and a footprint concentrated offshore the UK, backed by a market value of about £5.0b.
Ithaca Energy sits right in the sweet spot of this screen. It ties sizeable North Sea production volumes to European oil and gas pricing while using its listing and balance sheet to fund new basins that could reshape future cash generation.
"The acquisition of Terra Nova and White Rose in Eastern Canada introduces Ithaca Energy to a new operated hub with 103 mmboe of 2P reserves and a 17 year reserve to production ratio."
The real tension for Ithaca Energy is how one shifting policy and tax backdrop will ultimately feed through to margins and dividend headroom.
That policy overhang is exactly why reading the full narrative for Ithaca Energy can help you see how Ithaca Energy’s tax profile, cash returns and basin mix could be decoupling.
Harbour Energy (LSE:HBR)
Harbour Energy plugs directly into the European Integrated Oil & Gas and Diversified Energy Producers theme, with a broad upstream portfolio that ties cash generation to European oil and gas benchmarks across Norway, the UK and beyond.
Harbour Energy plc is a London headquartered independent producer focused on acquiring, developing and operating oil and gas fields across Norway, the UK, Germany, Mexico, Argentina, North Africa and Southeast Asia, with revenue concentrated in Norway at about US$4.9b and the UK at roughly US$3.9b, backed by a market value of about £5.46b.
"The integration of the Wintershall Dea acquisition has significantly increased Harbour Energy's production scale and asset diversification, substantially reducing reliance on mature UK North Sea assets and enabling expanded exposure to resilient international demand, which supports future revenue growth and earnings resilience."
What matters next for Harbour Energy is how one unresolved pressure on European gas pricing shapes margins and cash generation across that enlarged asset base.
That pressure point is exactly why reading the full narrative for Harbour Energy can help you see whether policy risk is masking a stronger Harbour Energy cash story ahead.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches a breakout, early momentum is often gone. Scan curated shortlists that are under the radar for now and consider getting in early.
- Spot income workhorses that help keep portfolios grounded while markets swing by tracking a curated set of high yielders through the 225 dividend fortresses.
- Look at early-stage potential where small caps may be gaining quiet momentum before headlines catch up by using the focused universe in the 39 profitable AI stocks that aren't just burning cash.
- Track real asset strength while currencies and inflation stories keep shifting by reviewing producers highlighted in the 35 elite gold producer stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com