


EN
US stock outlook | Futures of the three major stock indexes rose sharply, oil prices fell slightly, and Brazilian concept stocks fell sharply before the market, AI trading ushered in a “critical trial week”
Pre-market market trends
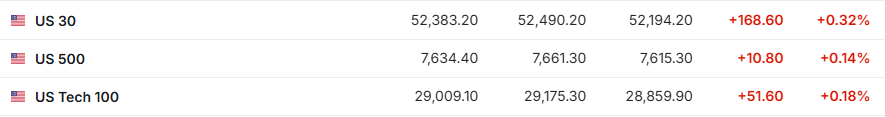
1. On October 26 (Monday), the futures of the three major US stock indexes rose sharply before the US stock market. As of press release, Dow futures were up 0.32%, S&P 500 futures were up 0.14%, and NASDAQ futures were up 0.18%.
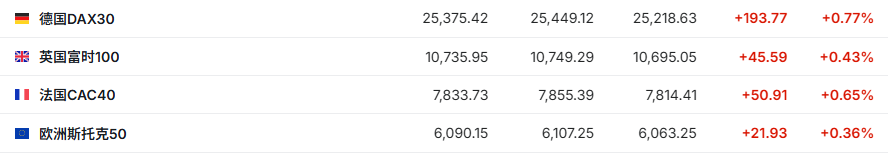
2. As of press release, the German DAX index rose 0.77%, the UK FTSE 100 index rose 0.43%, the French CAC40 index rose 0.65%, and the European Stoxx 50 index rose 0.36%.
3. As of press release, WTI crude oil fell 2.05% to $101.15 per barrel. Brent crude fell 1.49% to $110.04 per barrel.

Market news
The AI bull market in US stocks ushered in a “critical judgment week”: when the market no longer pays unconditionally, how will the financial reports of the three major cloud giants, the Federal Reserve's decision, and PCE determine the direction of the market. US stocks are entering a very decisive week. On the face of it, this is an intensive financial reporting window. Essentially, this is a simultaneous stress test of the roots of the artificial intelligence (AI) bull market narrative. The financial reports of the three largest cloud service providers to launch this week — Alphabet (GOOOGL.US), Microsoft (MST.US), and Amazon (AMZN.US), as well as two major memory chip giants — SK Hynix and Samsung Electronics — will test the success of the recently feared AI deal. Meanwhile, the Federal Reserve will announce its interest rate decision this week, and the market generally expects the central bank to stand still. What is more noteworthy about the ratio resolution itself is Chairman Walsh's communication attitude at the press conference after the meeting. Furthermore, the US personal consumption expenditure price (PCE) index for September will be released on October 29 — the day after the announcement of the Federal Reserve's decision — within the same week as the third-quarter GDP data. This schedule is expected to amplify the impact of the data on the market: investors will be forced to independently reprice the inflation trajectory less than 24 hours after digesting the perfect Federal Reserve decision.
Wall Street is hoping for a rebound after the election. BTIG threw cold water: the midterm elections may become a “starting point of decline” rather than a “starting point of rebound.” Wall Street investors looking forward to a rise in the stock market after the November midterm elections may be disappointed. BTIG strategist Jonathan Klinsky believes that as credit conditions deteriorate and multiple sectors show fatigue, the risk of a stock market decline is rising. Klinsky said in the research report that the S&P 500 index may fall back to around 7,300 points, close to its 200-day EMA and summer low. This is equivalent to a 4.3% drop from the index's recent level of 7631 points. If it falls below this technical support level, the benchmark index may decline further. This warning challenges the general expectation that “the stock market will rise after uncertainty about the November 3 election subsides”. Judging from history, midterm elections are often a turning point for the stock market, but Klinsky believes that this year's unusually strong market performance makes it less likely that this scene will be repeated. Klinsky wrote, “The reason the stock market often performs well in November of the midterm elections is that the S&P 500 usually weakens before the elections. The opposite was true this year.”
Goldman Sachs: Retail transactions are down 45% from the end of 2025, and household purchases are still the “ballast stone” for US stocks, maintaining S&P's bullish rise to 8,000 points at the end of the year. Goldman Sachs said that retail investors have drastically reduced stock trading in recent months, but the overall demand for stocks in American households is still strong enough to help support the market at a time when selling pressure rises and stock supply increases. Goldman Sachs strategist Ben Snyder said in an October 23 research report that retail trading volume has declined 20% since the summer and 45% since the end of 2025. Individual investors recently accounted for about 9% of total US stock turnover, down from 15% at the end of last year, and close to the lowest level since 2020. Meanwhile, hedge funds have reduced their market exposure after a turbulent week of heavy stock holdings. This “speculative activity is cooling down and household investment demand is still strong” is of great significance to the stock market. Households are the largest holders of US stocks, and their willingness to invest is an important source of support for stock prices. Goldman Sachs expects the largest increase in the net supply of US open stocks in 2027 since 2000, so continued household purchases may be particularly important.
Oil prices fell due to “demand disruption” and the risk of an attack on Saudi Arabia. On Monday, oil prices fell. While investors weigh the threat of further attacks on Saudi Arabia's energy infrastructure, they worry that high prices may eventually erode demand. Prior to this fall, oil prices had risen sharply last Friday — the Houthis attack on Saudi Arabia in Yemen has reignited market concerns about disruptions in global energy supply. Furthermore, according to reports, Iran confirmed that senior officials from Saudi Arabia, Pakistan, and Turkey, the three “Mecca Mutual Defense Agreement” member countries will meet with Iranian officials in Tehran today to discuss regional issues. This will be the first time that Iran and the Mecca coalition have held high-level contacts since the escalation of the situation in Yemen and frequent attacks between Saudi Arabia and the Houthis in Yemen. Iran has stated many times before that it is willing to mediate between Saudi Arabia and the Houthis.
Individual stock news
Musk warned of a “big reshuffle” to heighten market concerns, and Xinyun generally declined before the market. As of press time, CoreWeave (CRWV.US) is down nearly 5%, Nebius (NBIS.US) is down more than 3%, and IREN (IREN.US) is down more than 4%. According to the news, Musk predicts that the new cloud industry will usher in a reshuffle, and companies in the industry will face large-scale integration or even bankruptcy. Musk said that the debt market is unwilling to finance companies whose revenue is almost entirely dependent on AI data centers, adding that SpaceX has received 40 billion US dollars in debt financing to buy Nvidia GPUs, but unlike new cloud service providers, SpaceX also owns revenue from Starlink and rocket launch businesses. He concluded, “This means that more than 200 new cloud service providers will face large-scale death and consolidation. Some companies can get by, but not too many.
Brazilian concept stocks fell sharply before the market. The results of the second round of voting in Brazil's presidential election came to an end on Sunday. Current President Lula defeated leading right-wing candidate Flavio Bosonaro in the first round to win his fourth presidential term. The news triggered a wave of asset sell-offs in Brazil. As of press release, Brazilian financial services platform XP (XP.US), listed in the US, fell more than 47%, Petrobras (PBR.US) fell nearly 23%, ITUB.US (ITUB.US) fell more than 26%, PagSeguro Digital (PAGS.US) fell more than 31%, Telecom Brasil (VIV.US) fell nearly 18%, and Brazilian National Steel (SID.US) fell more than 16%. This sharp decline in Brazilian assets is related to previous investors generally betting on the victory of right-wing candidates. In the first round of voting on October 4, Flavio led Lula's 45.16% by 47.03%, which once triggered a strong rebound in Brazilian risk assets. Markets expect that when the right-wing government comes to power, it will adopt stricter fiscal policies to cut public spending, control government debt, and push interest rates down. However, Lula's eventual reversal and victory completely shattered this expectation, meaning that Brazil's current economic policies may continue, and investors' concerns about fiscal deficits, public debt, and future interest rate trends are heating up again.
Meta (META.US) is seeking equity financing of up to $95 billion to spend on artificial intelligence. Meta is seeking to raise up to $95 billion through the sale of common and preferred shares to gain investor support to lead the development of artificial intelligence. The company issued a statement on Monday saying it will issue approximately $35 billion in common and preferred shares. Additionally, the company will raise up to approximately $60 billion through the “Sell Shares at Market Price” program, which allows the company to sell shares on the open market from time to time. This time, the “Sale of Shares at Market Price” program will issue its planned Class C non-voting shares.
Verizon (VZ.US) had mixed results in Q3 and reached an AI infrastructure agreement of over $2 billion with Amazon AWS. According to financial reports, Verizon Q3 sales were US$34.313 billion, lower than market expectations of US$34.744 billion; adjusted earnings per share were US$1.31, better than market expectations of US$1.27. Thanks to improved operational efficiency, the company's net profit and adjusted EBITDA both hit record highs, and the annual results guidance was raised for the third consecutive quarter. The company currently expects full-year adjusted earnings of $5.04-5.06 per share, higher than the previous forecast of $4.99-5.04. Meanwhile, Verizon announced the expansion of strategic cooperation with Amazon AWS to reach an artificial intelligence (AI) infrastructure agreement worth more than 2 billion US dollars.
Moderna (MRNA.US) continued to decline before the market, and melanoma vaccine data was leaked for subsequent fermentation. As of press release, Moderna is down more than 8% before the market, with a cumulative decline of about 26% in the last two trading days of last week. According to the news, the personalized melanoma vaccine intismeran autogene phase III data jointly developed with MRK.US (MRK.US) was leaked ahead of time last Thursday: the combined Keytruda could reduce the risk of cancer recurrence or death by 42% and the risk of distant metastasis or death by 38%. The data itself was positive but lower than the 49%/59% drop in early studies, falling at the lower end of the investors' expected range. RBC says the data is “clinically meaningful and likely to be approved,” and UBS says it has strengthened confidence in subsequent kidney cancer and bladder cancer research, but the target prices of many institutions are still far below current prices.
$6 billion takeover! Healthcare giant Bosecourse plans to hold Surgery Partners (SGRY.US). According to people familiar with the matter, Bon Secours Mercy Health (Bon Secours Mercy Health) is in the late stages of negotiations to acquire a majority stake in surgery service provider Surgery Partners. This deal will value the company supported by Bain Capital (Bain Capital) to about $6 billion, including $3.5 billion in debt. A partial acquisition of Surgery Partners by Beaucecourse would value the company at around $20 per share. Bain Capital will retain nearly 40% of its shares. As of press release, Surgery Partners surged more than 24% in the premarket on Monday.
Performance Forecast
Tuesday Morning: Keng Teng Electronics (CDNS.US)
Tuesday pre-market: Novartis Pharmaceuticals (NVS.US), HSBC (HSBC.US), Coca Cola (KO.US), Boeing (BA.US), Union Package (UPS.US), PayPal (PYPL.US), Corning (GLW.US), McMoRan Copper & Gold (FCX.US)