


EN
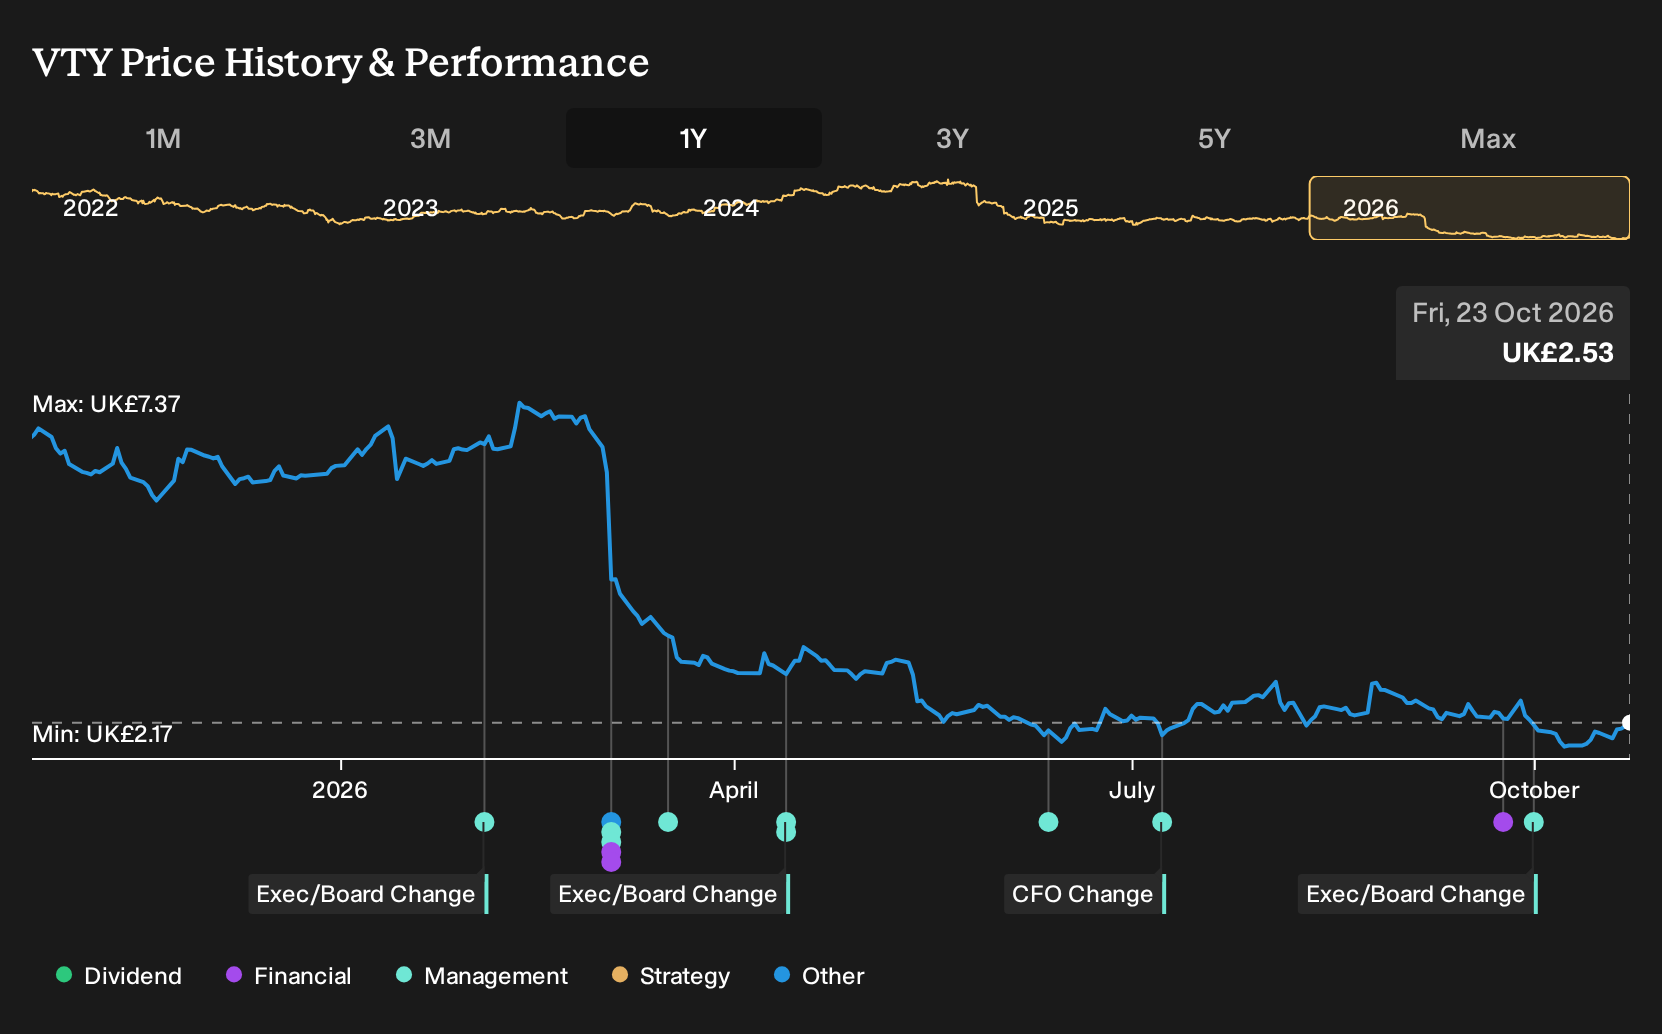
Did Vistry Group's 63% Drop Catch You Out? What Investors Missed
If you only glanced at headlines about Vistry Group’s partnerships, offsite manufacturing and government backed affordable housing pipeline, it might have sounded like a steady, operational story rather than a wealth destroyer. Investors who held Vistry Group over the past year are down 63.0%, including dividends. If you were weighing a purchase back in October 2025, how much of that eventual loss was hinted at by the early warnings already on record?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Vistry Group has already moved. See which of 9 high quality undervalued stocks still trade below our estimates.
Two Competing Stories Investors Had To Weigh On Vistry Group
The shares cost £6.88 at the start of the period, and anyone looking at Vistry Group then had to choose between two sharply different stories that still both sounded reasonable.
The bullish narrative put Fair Value at £7.73 and rested on the idea that UK affordable housing partnerships and offsite manufacturing could support 11.9% annual revenue growth and a margin lift from 2.0% to 6.1% by about 2028.
The bearish view pegged Fair Value at £4.5 and focused on slowing UK housing demand and policy risk, with an assumption that revenue would decline 0.4% a year even if margins rose to 6.6%.
What The Results Put To The Test At Vistry Group
The clearest data point came later. Vistry Group reported revenue of £1,418.2m in H1 2026 versus £1,635.6m in H1 2025, and net income swung from £31.3m profit to a £607m loss, with net margin moving from 1.9% to a loss of 42.8%. That scale of loss challenged both bullish margin expansion and cautious stability. The evidence cut both ways.
The big assumption was margin resilience. When you see a thesis leaning on future profitability, check how net income and net margin move in each set of results before trusting any growth story.
What You Would Be Paying For Today With Vistry Group
Vistry Group now trades at £2.53. The selected Narrative views Fair Value as above that level, built on the idea that higher margin partnership sites and a leaner balance sheet could matter more than recent headline losses.
A buyer today would need to believe that execution on the 12 region structure and Linden product range can reliably turn that rebuilt portfolio into the margins and returns the Narrative describes.
"More of Vistry Group’s portfolio moving from the underperforming 41% of sites into the group of locations already achieving around 18.5% gross margins and ROCE above 40% could shift the earnings mix toward higher return projects and lift group operating margin."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Vistry Group
Vistry Group raises questions about resilience and capital heavy projects. It also nudges something else. What about businesses tied to everyday discretionary spending instead?
There is a global brand that leans on scale and strong supplier terms. It uses that position to keep products reachable for middle and lower income shoppers.
That focus on affordability can matter when budgets tighten. People may still trade down within a category rather than stop buying entirely.
This other business also pushes deeper into selling directly to consumers. That mix of brand, cost discipline and direct reach leaves a different long haul puzzle.
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com