


EN
Synaptics (SYNA) Stock Could Be 41% Overvalued Following Edge AI Launch
Synaptics has ridden a strong share price run into late 2026, helped by new product launches and a pending acquisition, which puts fresh attention on whether the current valuation can be supported by its underlying cash flows. With a live Discounted Cash Flow (DCF) estimate available, the question is how closely that intrinsic value aligns with where the stock now trades.
- Over the past year the stock has returned 61.0%, which raises the issue of whether cash generation has kept pace with the market's optimism.
- ON Semiconductor's agreed all cash offer of US$123 per share and Synaptics' push into Edge AI hardware through its Astra SR200 Series may support expectations for future cash flow strength and timing that matter for any intrinsic value estimate.
- If you'd rather focus on sales, this one's for you. See what Synaptics's 3.8x P/S says about the price.
The issue now is whether Synaptics' current share price near US$117, after that 1 year run and recent deal news, is adequately explained by the cash flows implied in its Discounted Cash Flow (DCF) valuation.
If you want a broader watchlist built around this kind of AI hardware and cash flow focus, start your research with 55 AI infrastructure stocks.
Does Synaptics Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on how much cash Synaptics can return to shareholders over time. Latest twelve month Free Cash Flow sits at about $56.6 million, while the projections used in the model assume growing Free Cash Flow, with analyst and modelled figures stepping up into the low to mid hundreds of millions of dollars over the next decade.
Those assumptions imply a business that scales cash generation meaningfully from current levels. However, the DCF output still places Synaptics' estimated intrinsic worth substantially below today's share price of $117.26. ON Semiconductor's agreed all cash offer of US$123 per share helps explain why the traded price can stay above what the discounted cash flow projections alone would support, since deal terms, timing and perceived certainty all feed into how investors weigh that gap. Find out what Synaptics could be worth using our Discounted Cash Flow (DCF) estimate.
The Synaptics Narrative: What Would Justify Today's Price?
Synaptics' valuation gap raises a simple question for anyone watching the stock. Narratives on Simply Wall St's Community page spell out which paths for growth, margins and earnings would need to unfold for the shares to be worth materially more or less than today. Each storyline links a fair value estimate to a clear set of potential catalysts and risks so you can track which version of events appears to be taking shape over time.
Community views on Synaptics split between those who see the all stock merger and Edge AI push as underappreciated and those who think the deal already captures most of the upside.
Bull case: 10% undervalued
"The launch and initial customer traction of native Edge AI processors (Astra family, featuring Google Research collaboration and neural transformer support) targets the growing shift toward on-device processing for AI workloads…"
Discover why this Narrative puts Synaptics at 10% undervalued.
Bear case: 12% overvalued
"The push toward Edge AI and hybrid compute between data centers and devices could lead to heavy, ongoing R&D and capital needs for Astra and Torq AI, which may pressure net margins if revenue from these platforms scales more slowly than current investor expectations…"
Explore why this Narrative puts Synaptics at 12% overvalued.
One more Synaptics signal that could change how you read the story
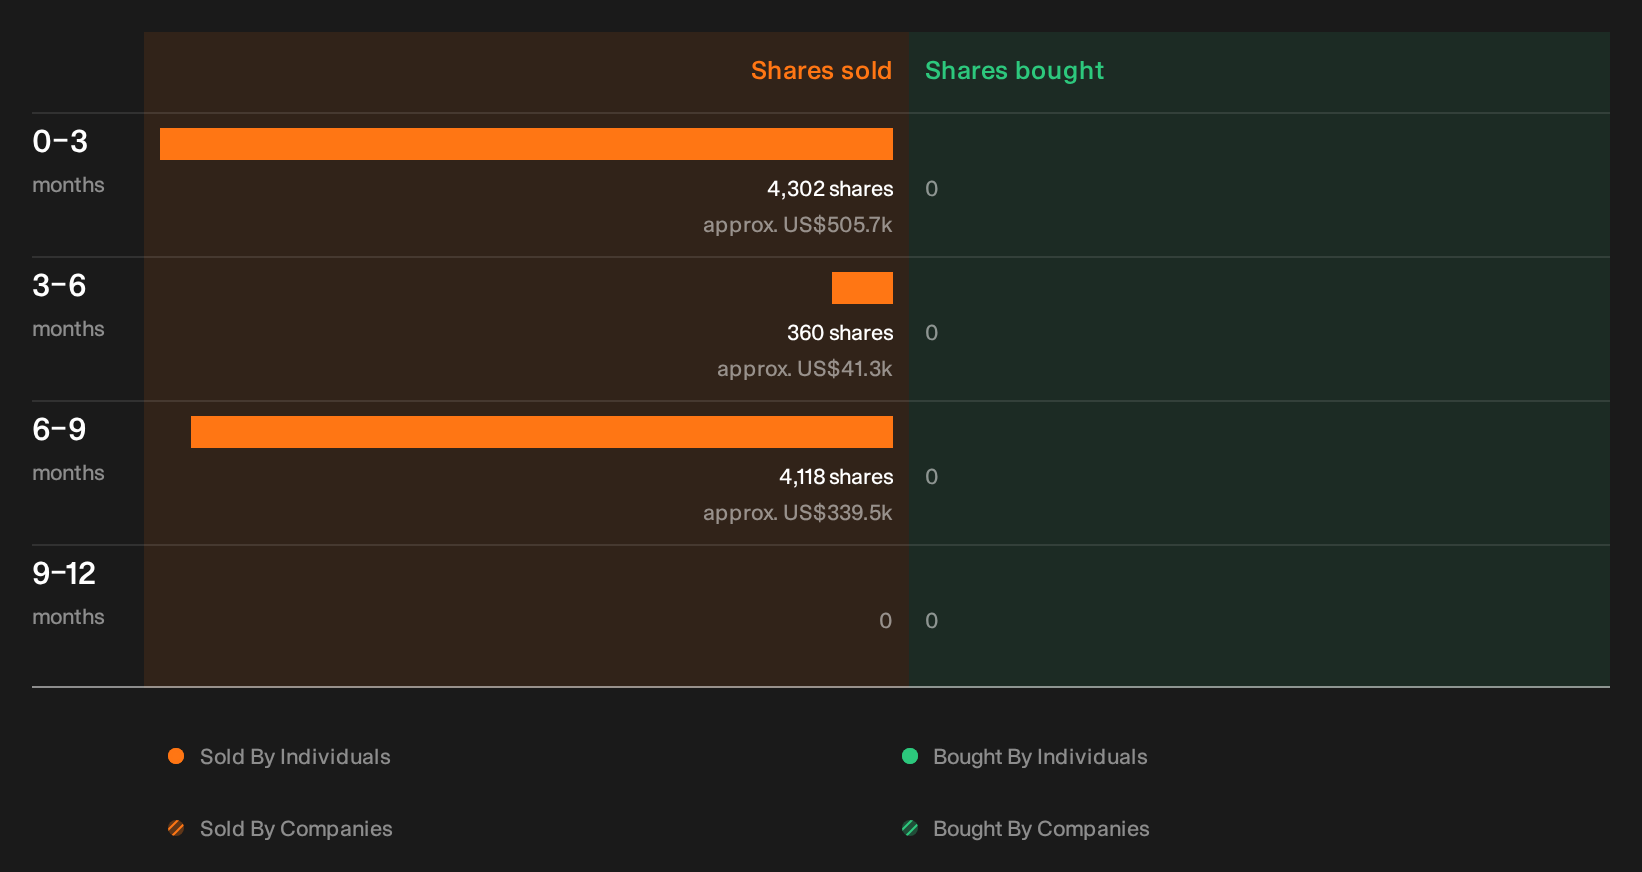
Valuation models and deal terms only go so far if insiders are making different decisions with their own holdings. Recent selling activity our checks have picked up deserves a closer look on who sold, how much, and why. See the recent insider selling flagged for Synaptics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com