


EN
MPLX (MPLX) Stock May Be Below Fair Value On Earnings Support
MPLX has delivered a long run of strong share returns, and that raises a straightforward question for investors who care about fundamentals. Is the current price being asked for MPLX stock now adequately supported by the earnings the partnership is generating?
- Over the past 5 years, MPLX has returned 199.1%, which puts real weight on the question of whether its earnings can support today’s valuation.
- The partnership’s business model is heavily tied to fee-based midstream infrastructure, which can influence how reliably earnings translate into cash that equity holders ultimately rely on.
- There is a second opinion on MPLX worth weighing. See what analysts think MPLX's shares could be worth.
The stock’s next move may depend on whether MPLX’s current earnings level is enough to justify the price investors are paying today.
To pressure test MPLX against similar opportunities built on earnings support, it can help to line it up beside 28 high quality undervalued stocks.
Is MPLX a Bargain on Earnings?
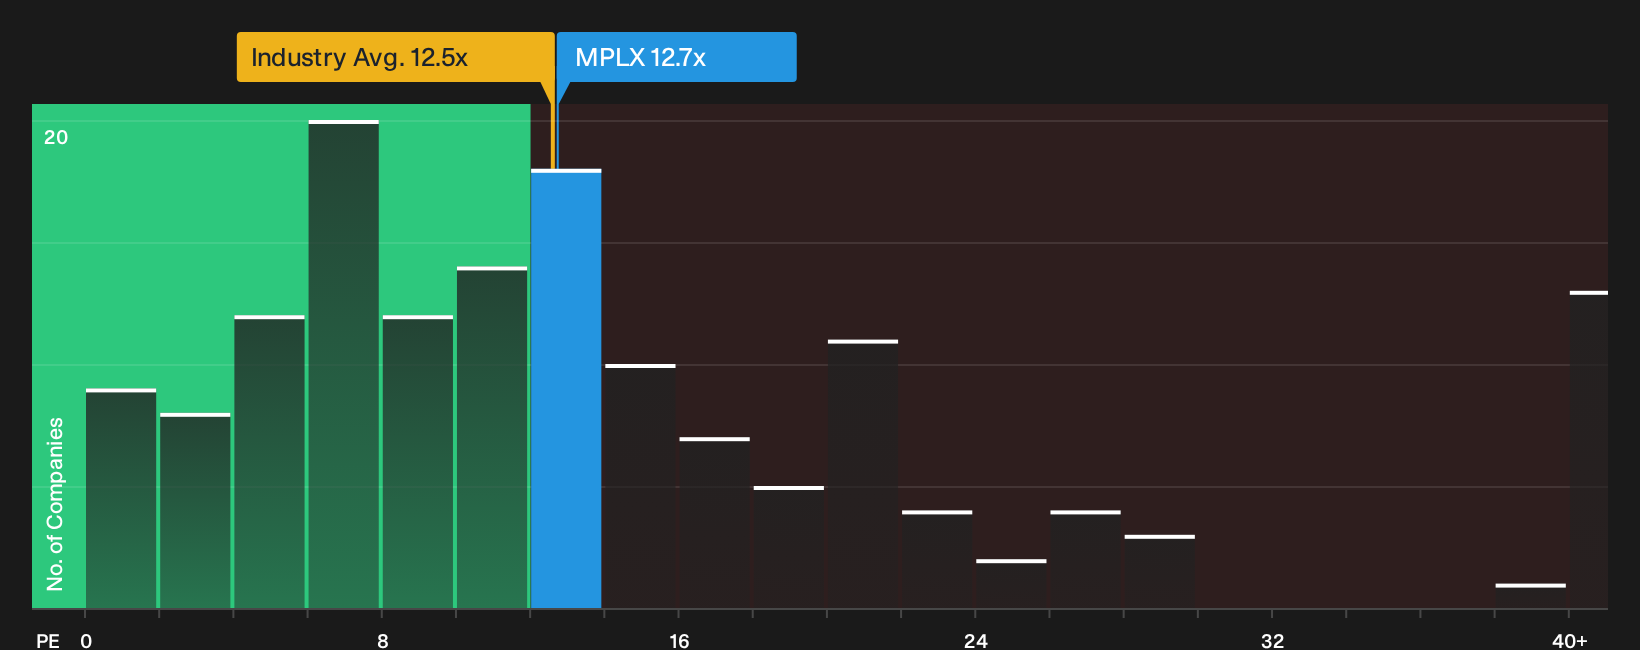
The P/E ratio suits MPLX because earnings are a central reference point for a fee-based pipeline partnership. MPLX trades on a P/E of 12.7x, which is very close to the wider Oil and Gas sector average of 12.5x. Against a group of broader peers, where the average multiple is 21.4x, the partnership changes hands at a visibly lower earnings multiple.
The fair-value framework that blends MPLX’s growth expectations, profitability profile, sector and risk inputs points to a higher P/E than where the units currently change hands. That places today’s 12.7x P/E below the level suggested by this tailored benchmark. Anyone assessing the stock through an earnings lens would need to decide whether that discount lines up with their view of the partnership’s long term cash generation and risk profile. Explore the numbers behind MPLX's P/E valuation.
The MPLX Narrative: What Would Justify Today's Price?
MPLX Narratives on Simply Wall St pick up where the valuation question leaves off and explain what would need to happen to MPLX's earnings, margins and growth for the units to be worth meaningfully more or less than today’s price on the Community page. Rather than a single headline multiple or model figure, each narrative lays out the assumptions behind its view of fair value so you can later compare them with MPLX's reported results.
One of the top community narratives on MPLX: 6% undervalued
"The main factor that has to go right is that MPLX executes its large slate of gas and NGL projects while keeping returns in line…"
Discover why this Narrative puts MPLX at 6% undervalued.
MPLX valuation leaves one crucial issue hanging
MPLX’s pricing story only goes so far before another question starts to matter, because recent research has also highlighted specific concerns that investors may want to weigh alongside the earnings case. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com