


EN
Everpure (P) Stock Could Be Undervalued On Its 354% Five Year Run
Everpure has delivered a huge multi year share price run, yet recent price softness now raises a sharper question for investors about how fully its current sales base is already reflected in the valuation. With the stock changing hands at US$123.33 after a long climb, the key issue is whether today’s tag still lines up with what the business is generating in revenue.
- Over the past 5 years, Everpure has returned 354.3%, which puts a lot of accumulated optimism on the line when you assess what each dollar of its sales is worth today.
- The recent Cisco AI POD collaboration, built on Everpure’s FlashBlade//S500 storage, may support expectations for enterprise AI related data workloads and could influence how investors think about future sales growth relative to the current price to sales profile.
- There is a second opinion on Everpure worth weighing. See what analysts think Everpure's shares could be worth.
The issue now is whether the current Everpure share price is adequately supported by its sales when set against the Fair Ratio benchmark.
If you are weighing Everpure against other ways to play enterprise AI infrastructure, a focused stock screen of 55 AI infrastructure stocks.
Does Everpure Look Undervalued on Sales?
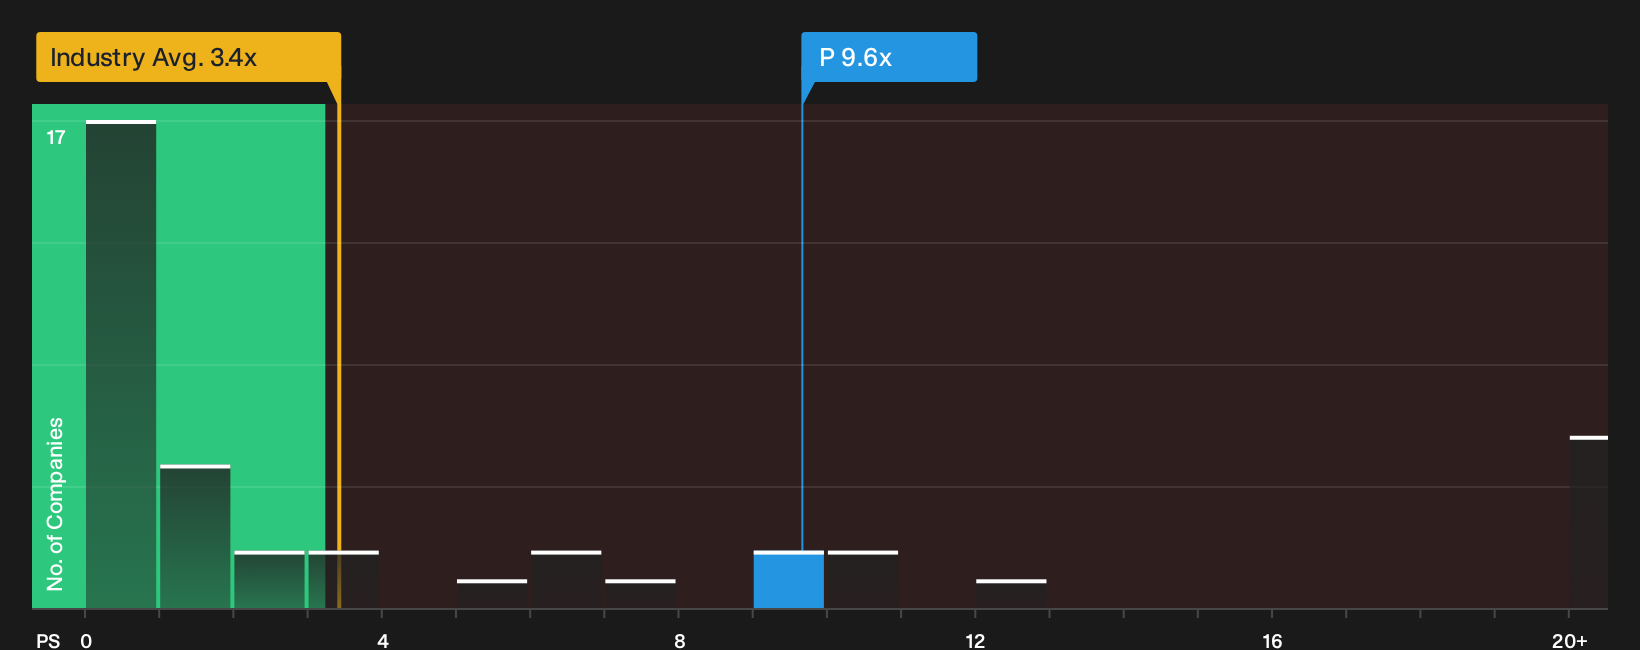
P/S is often a cleaner lens for Everpure because much of the recent AI infrastructure story still flows through revenue rather than mature earnings. On this measure, the stock trades on a P/S of 9.6x, compared with a Tech industry average of about 3.4x and a peer group closer to 4.2x. That is a sizeable premium for each dollar of sales, even before considering what the Cisco AI POD work might mean for demand.
The Fair Ratio model, which blends Everpure’s growth profile, margins, scale and risk, points to a higher P/S benchmark than where the shares change hands today. As a result, the current multiple screens as undervalued on this framework rather than stretched. Because the Cisco collaboration has already been flagged and the share price moved on that news, the fact that the P/S still sits below this tailored yardstick suggests the market may not be fully pricing in what the existing sales base could justify on this metric. Explore the numbers behind Everpure's P/S valuation.
The Everpure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Everpure valuation puzzle leaves off and explain which paths for growth, profitability and earnings would need to unfold for the current share price to become meaningfully higher or lower over time. Each scenario links its figures to a clear view of how Everpure's revenue trajectory, margin profile and risk picture might change, giving you a reference point you can revisit as fresh information becomes available.
Community views on Everpure are split between a re-rating opportunity and a stock that already bakes in much of the AI story.
Bull case: 31% undervalued
"A storage company that demonstrably reduces GPU capex requirements gets re-rated somewhere in between…"
Discover why this Narrative puts Everpure at 31% undervalued.
Bear case: 65% overvalued
"The key investment thesis is a multiple re-rating, not just earnings growth…"
Explore why this Narrative puts Everpure at 65% overvalued.
Everpure’s price is only one question you need to answer
Valuation tells you what investors are willing to pay today, but Simply Wall St’s checks on Everpure have turned up specific risk signals that deserve your attention before you lean on the numbers alone. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com