


EN
European Growth Companies With Insider Ownership In October 2026
In October 2026, European markets faced a challenging environment marked by heightened inflationary pressures and geopolitical tensions, leading to a decline in major indices such as the STOXX Europe 600. Amid these uncertainties, growth companies with substantial insider ownership can offer potential stability and confidence to investors, as insider stakes often align management interests with shareholder value.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Envipco Holding (ENXTAM:ENVI) | 15.2% | 101.6% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.1% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.6% |
We're going to check out a few of the best picks from our screener tool.
Moltiply Group (BIT:MOL)
Simply Wall St Growth Rating: ★★★★☆☆
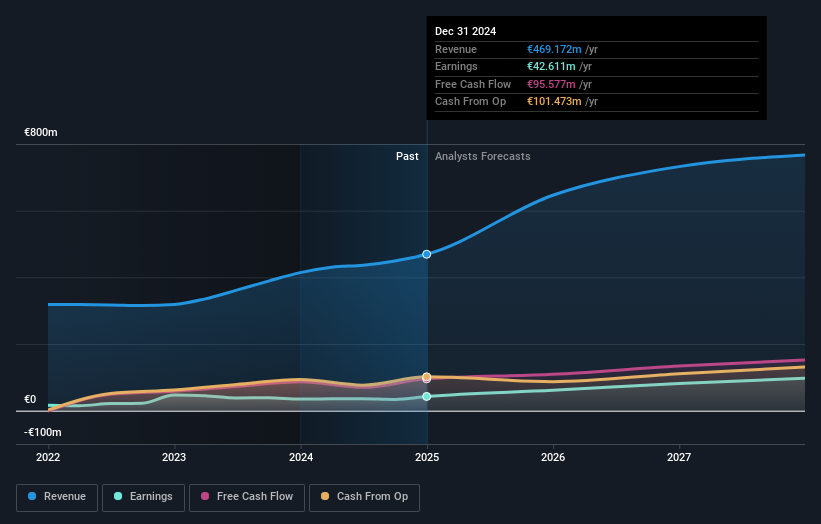
Overview: Moltiply Group S.p.A. is a holding company in the financial services industry with operations in Italy, Germany, and internationally, and it has a market cap of €1.24 billion.
Operations: The company's revenue is primarily derived from the Mavriq Division, contributing €458.79 million, and Moltiply BPO&Tech, which adds €256.71 million.
Insider Ownership: 18.5%
Earnings Growth Forecast: 27.9% p.a.
Moltiply Group's recent earnings report shows robust growth, with sales increasing to €353.8 million and net income rising to €36.71 million for H1 2026. Despite high debt levels, its earnings are forecasted to grow significantly at 27.87% annually over the next three years, outpacing the Italian market average of 9.2%. Insider ownership remains stable with no significant buying or selling in recent months, while share price volatility persists despite a completed share buyback program worth €5.94 million.
- Delve into the full analysis future growth report here for a deeper understanding of Moltiply Group.
- The analysis detailed in our Moltiply Group valuation report hints at an inflated share price compared to its estimated value.
Sdiptech (OM:SDIP B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Sdiptech AB (publ) offers technical services for infrastructure across several countries including Sweden, the United Kingdom, Germany, and others, with a market cap of SEK10.03 billion.
Operations: The company's revenue is primarily derived from its Supply Chain & Transportation segment at SEK2.29 billion, followed by Energy & Electrification at SEK1.20 billion, Water & Bioeconomy at SEK921 million, and Safety & Security at SEK466 million.
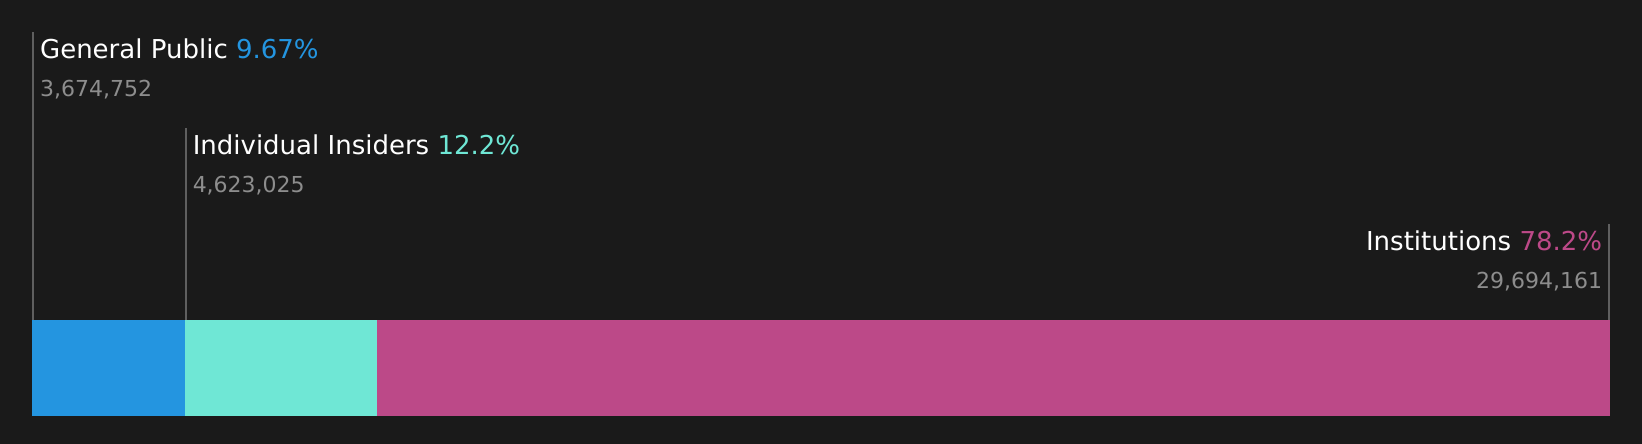
Insider Ownership: 12.2%
Earnings Growth Forecast: 23.8% p.a.
Sdiptech's recent earnings reveal a turnaround, with net income reaching SEK 114 million in Q3 2026 from a loss last year. The company trades at a significant discount to its estimated fair value and is expected to see substantial annual profit growth of 23.8%, outpacing the Swedish market. Insider activity shows more buying than selling recently, despite modest volumes. However, interest payments remain poorly covered by earnings, indicating financial challenges ahead.
- Click to explore a detailed breakdown of our findings in Sdiptech's earnings growth report.
- According our valuation report, there's an indication that Sdiptech's share price might be on the cheaper side.
Grupa Pracuj (WSE:GPP)
Simply Wall St Growth Rating: ★★★★☆☆
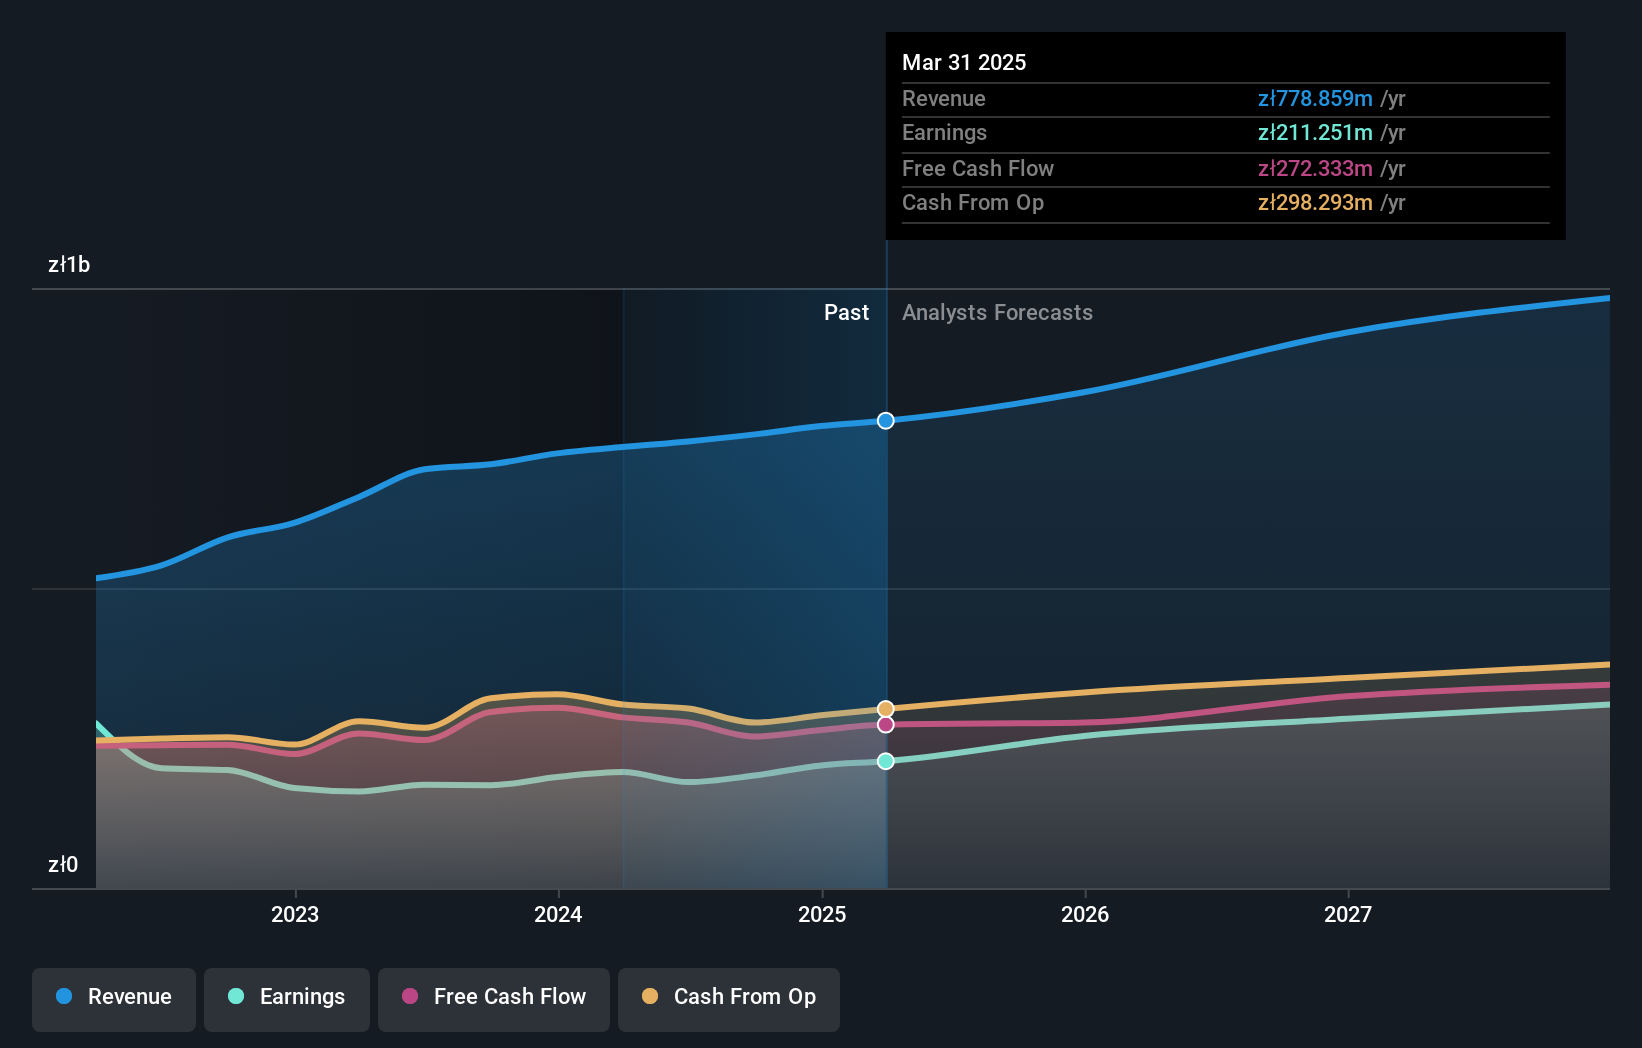
Overview: Grupa Pracuj S.A. operates an HR technology platform in Poland, Ukraine, and Germany with a market cap of PLN3.80 billion.
Operations: The company generates revenue primarily from its Staffing & Outsourcing Services segment, which accounts for PLN827.35 million.
Insider Ownership: 11.7%
Earnings Growth Forecast: 12.1% p.a.
Grupa Pracuj's earnings have shown steady growth, with net income rising to PLN 65.65 million in Q2 2026 from PLN 54.75 million a year earlier. Despite trading at a significant discount to its estimated fair value, the company's revenue is forecast to grow modestly at 6% annually, surpassing the Polish market average of 5.4%. Earnings are projected to increase by 12.1% per year, outpacing local market expectations but not significantly high overall.
- Get an in-depth perspective on Grupa Pracuj's performance by reading our analyst estimates report here.
- Upon reviewing our latest valuation report, Grupa Pracuj's share price might be too pessimistic.
Summing It All Up
- Click this link to deep-dive into the 200 companies within our Fast Growing European Companies With High Insider Ownership screener.
- Interested In Other Possibilities? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com