


EN
How AI Product Expansion At Costco (COST) Has Changed Its Investment Story
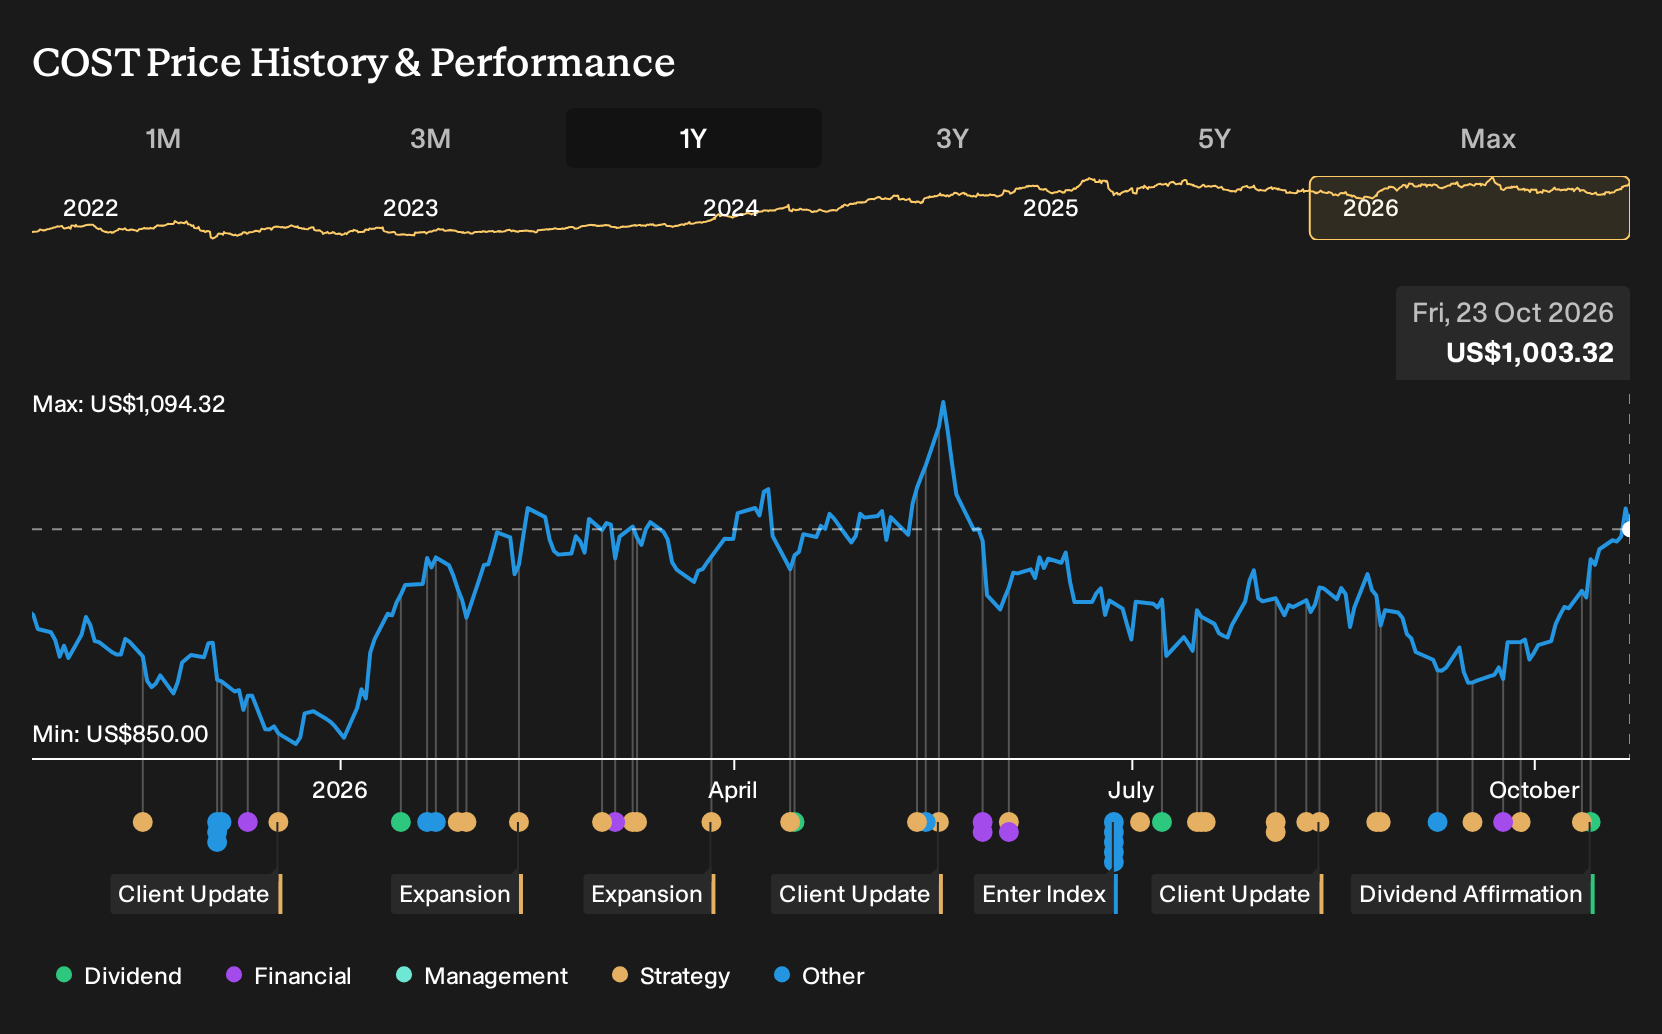
- Costco Wholesale declared a quarterly cash dividend of $1.47 per share, payable on November 13, 2026, and also began offering Hohem’s iSteady M7 AI tracking smartphone gimbal to members at a discounted price compared with its U.S. MSRP.
- The combination of a steady dividend payout and fresh AI driven electronics, alongside expanding travel services, suggests that Costco Wholesale is using digital products and ancillary offerings to reinforce the value of its membership model.
- We will now examine how Costco Wholesale's push into AI focused electronics could influence the broader investment narrative around membership economics.
Scan beyond Costco Wholesale and compare its mix of dividends, AI tools and member perks with a curated list of 39 profitable AI stocks that aren't just burning cash.
Costco Wholesale Investment Narrative Recap
For Costco Wholesale, the core belief is that a membership model funded by fees and steady warehouse traffic can keep supporting earnings while capital spending rises and digital channels scale. The fresh dividend affirmation at $1.47 per share fits that story, but does not meaningfully change the near term picture for cash returns or capital plans.
The key short term swing factor remains whether slower membership additions still translate into healthy spending per member, especially as Costco Wholesale leans harder on e commerce, delivery and ancillary lines like travel. The biggest risk is that prolonged membership deceleration or regulatory pressure on categories such as beef interrupts that spending and compresses reported margins.
The Hohem iSteady M7 launch inside Costco Wholesale appears closely tied to the existing digital catalyst. Management has already reported digitally enabled sales of more than US$33b in FY26, supported by higher app traffic and strong conversion from AI search. Offering AI driven accessories at a member only price gives that online funnel another reason to convert interest into actual spend.
For you as a shareholder, the operational question is whether this type of AI focused electronics can lift basket size and keep members engaged even as overall membership growth slows. If Costco Wholesale executes well, these products, together with travel, gas and pharmacy, could deepen ancillary mix, while foreign exchange swings and any further slowdown in new members remain on the risk list.
Costco Wholesale Forecasts Behind the AI Push
Costco Wholesale's current analyst playbook ties the AI driven merchandising push to a broader earnings and revenue framework that runs out to 2029. The working assumption is that annual sales growth of 7.6% can support a move in profit margins from 3.0% today to 3.2% over the next few years, with membership fees, ancillary services and digital add ons all feeding into that shift.
On the earnings side, analysts see Costco Wholesale moving from US$9.2b in profit today to US$12.2b by 2029, a value increase of about US$3.0b. That consensus number underpins a forecast of earnings per share of US$27.52, with expectations that the share count stays broadly flat, so most of the growth in profit per share would need to come from higher margins and a larger revenue base rather than financial engineering.
Costco Wholesale's valuation story in those reports relies on that earnings bridge and a higher multiple. Analysts are effectively penciling in a P/E of 47.4x on the forecast US$12.2b of earnings in 2029, compared with about 44.4x today and roughly 18.1x for the wider US consumer retailing group. For readers, the key question is whether the combination of higher capital spending, stronger digital conversion and member centric perks such as AI gear and travel justifies that richer earnings multiple versus the sector.
Costco Wholesale's narrative projects US$377.5b revenue and US$12.2b earnings by 2029. This assumes 7.6% yearly revenue growth and an earnings increase of about US$3.0b from US$9.2b today.
Uncover why Costco Wholesale's fair value indicates a 5% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
Some of the lowest Costco Wholesale forecasts lean on a different concern. You see more focus on margin pressure from items tied to memory and petroleum products. Those analysts were only penciling in about 6.4% yearly revenue growth and roughly US$11.8b of earnings by 2029, so they may view this dividend and AI gimbal launch very differently once their models refresh.
Explore 12 other Costco Wholesale fair value estimates, including one that suggests as much as 44% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Costco Wholesale research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Costco Wholesale. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Costco Wholesale's overall financial health at a glance.
Looking for more investment ideas beyond Costco Wholesale?
If you want to put Costco Wholesale in context and broaden your watchlist, the Simply Wall St Screener can help you line up other candidates that fit the type of portfolio you are trying to build.
- If downside protection matters most to you, start with companies that carry lower overall risk and tighter fundamentals through a 30 resilient stocks with low risk scores.
- Income focused investors who care about reliability as much as yield can scan for payout heavy businesses using the 5 dividend fortresses.
- For those hunting for mispriced opportunities with solid financial footing, filter the market with a 28 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com