


EN
Antero Midstream (AM) Keeps Its Dividend Steady As Valuation Debate Heats Up
Antero Midstream (AM) just affirmed its income story again by declaring a third quarter 2026 cash dividend of $0.225 per share, equal to $0.90 on an annualized basis for shareholders.
Income investors have been rewarded with more than just the dividend. Antero Midstream’s share price is at $20.85 after a year-to-date share price return of 16.22%, while the 1-year total shareholder return of 21.73% and 5-year total shareholder return of 168.21% point to strong compounding around its consistent payouts and recent buyback activity, even though shorter term share price performance has softened over the past three months as the market reassesses growth expectations and risk around the story.
Scan other income-focused ideas with consistent cash returns by reviewing the hand-picked 5 dividend fortresses along with Antero Midstream’s latest dividend move.
Antero Midstream has already delivered a powerful multi year run, yet the latest dividend affirmation and stepped up buybacks raise a fresh question: Is most of the return story already behind investors, or does valuation still leave room ahead?
Most Popular Narrative: 13% Undervalued
Antero Midstream’s most followed narrative pegs fair value at $24.00, compared with the recent $20.85 close, which points to a valuation gap that investors are actively debating.
Integration of the HG Midstream assets, including about 50 miles of east to west gathering lines and adjacent water infrastructure, is expected to support high single digit EBITDA growth through at least 2027 with limited incremental capital, which can lift earnings and free cash flow.
Expansion of the cost plus 13% closed loop water system into the HG area, with identified capital avoidance synergies of over US$100 million in present value and limited required maintenance capital, is expected to lower capital intensity and support high single digit EBITDA growth in 2027, which can support stronger net margins.
See why 20 investors see Antero Midstream as 13% undervalued.
Result: Fair Value of $24.00 (UNDERVALUED)
Still, heavy reliance on Antero Resources in Appalachia and the need to deliver on ambitious margin and earnings forecasts could quickly challenge the Antero Midstream undervaluation story.
Find out about the key risks to this Antero Midstream narrative.
Another View: Antero Midstream Looks Expensive On Earnings
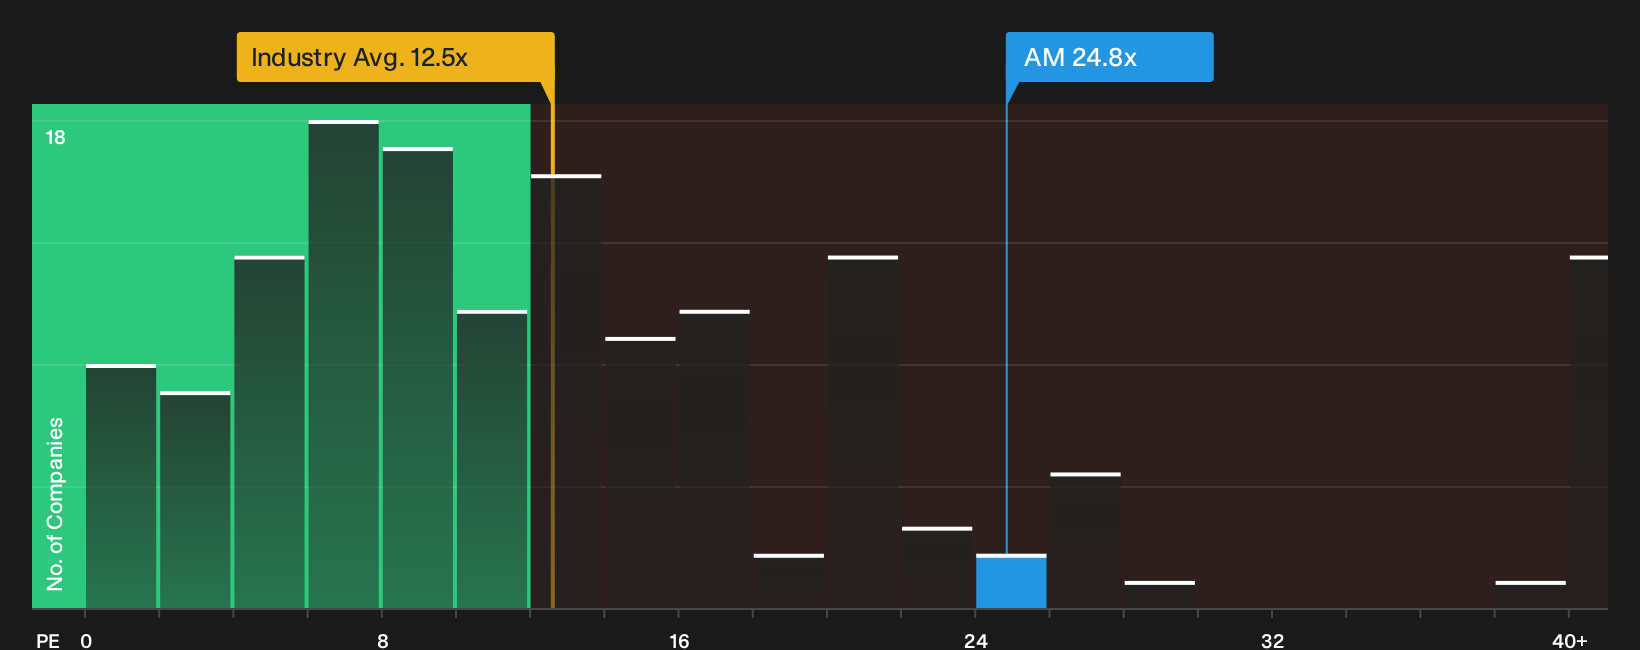
There is a very different message when you look at Antero Midstream through its P/E. The shares trade at 24.8x earnings compared with a fair ratio of 22.5x, the US Oil and Gas sector at 12.5x, and peers at 17.4x. That premium points to real valuation risk if sentiment cools.
Before leaning too hard on any single earnings multiple, it helps to understand how these valuation gaps are built from the ground up and where they could close over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Antero Midstream’s value story mean opinion is split, so move quickly, test the numbers yourself and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Antero Midstream?
If you stop at Antero Midstream, you risk missing other setups where income, quality and valuation all line up in your favor.
- Target robust cash generators that still look overlooked using the 28 high quality undervalued stocks.
- Lock in sturdier sleep-at-night positions by filtering companies with the 30 resilient stocks with low risk scores.
- Hunt for fresh opportunities the market has not crowded yet with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com