


EN
3M (MMM) Is Getting Fresh Attention, What Is The Market Looking At?
3M earnings and AWS deal put optical connectivity in focus
3M (MMM) reported stronger third quarter earnings and announced a new collaboration update with Amazon Web Services, linking its Expanded Beam Optical platform directly to spending on big data center and artificial intelligence infrastructure.
After a strong earnings print and the AWS agreement, 3M’s recent price action reflects a mix of near-term confidence and longer-term curiosity. The share price return is up 7.2% year to date, and the 3-year total shareholder return is very large at around 15x. However, momentum has eased over the past 90 days, with a 4.9% decline in the share price return and a 1-day share price move down 1.2% to US$173.46.
Scan for other industrials tied to AI infrastructure by reviewing the hand picked 55 AI infrastructure stocks, which echoes the optical connectivity theme behind 3M’s latest AWS collaboration.
Recent gains, softer three-month momentum and a fresh AWS tie up leave 3M at an awkward middle point. Is this the moment to commit capital, or does patience around valuation make more sense?
Most Popular Narrative: 7% Undervalued
On Simply Wall St’s most followed view, 3M’s fair value sits at $186.98, a touch above the latest $173.46 close. This keeps the AWS and data center story tied directly into valuation work built on a 7.87% discount rate.
The acceleration in new product launches, now at an expected 350 plus in 2026 with 176 launches in the first half and five-year new product sales expected to reach about US$4b, continues to build on 3M’s R&D factory model and rising New Product Vitality Index. This can support future revenue outgrowth versus end markets and help mix up gross margins and earnings.
See why 186 investors see 3M as 7% undervalued.
Result: Fair Value of $186.98 (UNDERVALUED)
Still, unresolved PFAS and safety lawsuits, along with inflation driven input costs that pressure pricing power, could quickly challenge the optimistic 3M valuation story.
Find out about the key risks to this 3M narrative.
Another View: What 3M’s P/E Is Really Saying
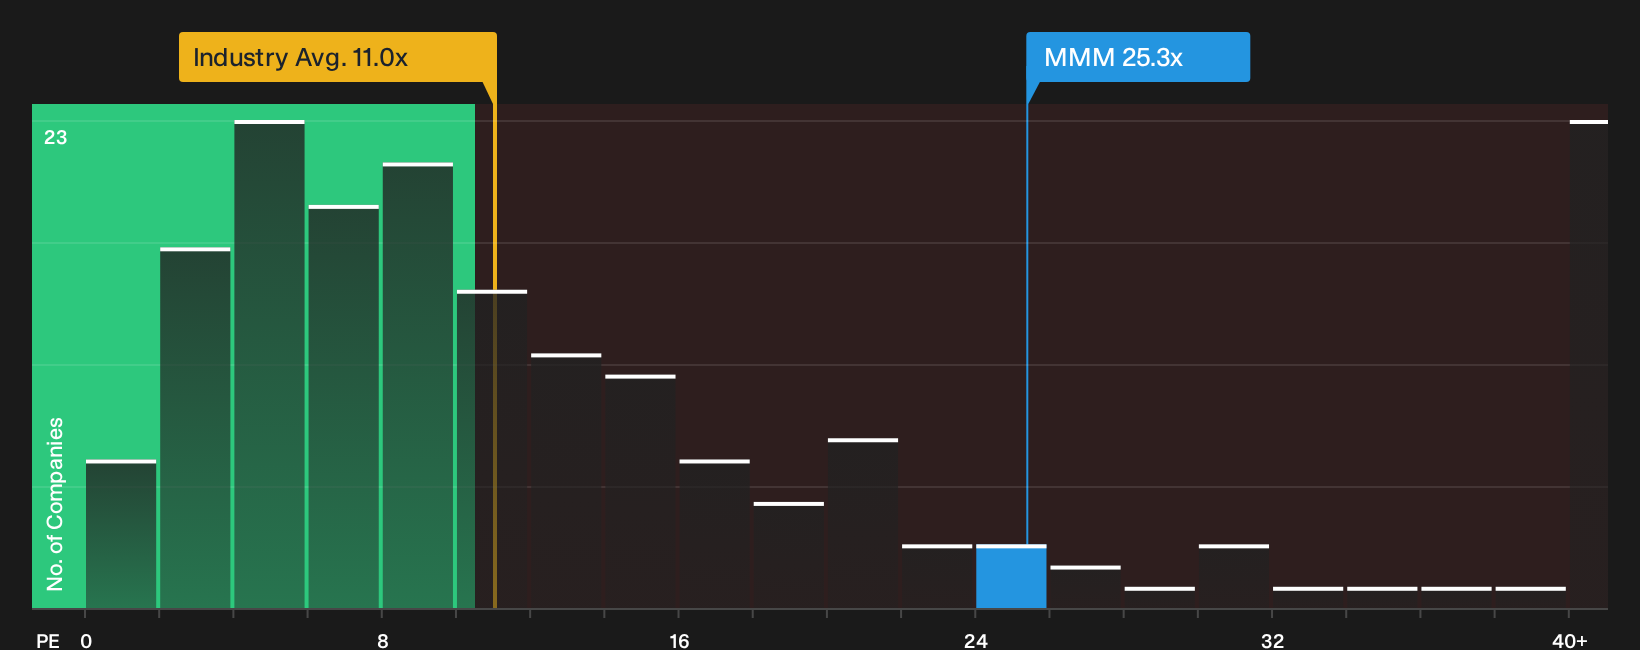
There is a different lens investors use on 3M. On simple earnings multiples, the stock trades on a P/E of 25.3x, which is more than double the global Industrials group at 11x and below its own fair ratio of 28.1x that our model suggests the market could move toward.
That mix creates an odd setup. The share price already carries a clear premium to the wider sector and still sits below where the fair ratio pins it, which points to both potential valuation upside and the risk that sentiment cools if expectations reset. Which side of that trade-off are you more inclined to accept?
See what the numbers indicate about this price in the valuation breakdown here, then decide how comfortable you are with paying up for 3M’s earnings profile relative to peers See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how 3M compares with the sector on this measure, review the latest comparison chart
Next Steps
Mixed signals on 3M’s value and risks can either feel like noise or a useful prompt. Treat this as your cue to review the data yourself, weigh both the upside and the legal or operational pressure points, and then stress test your own thesis against the stock’s 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond 3M?
Do not leave your research parked on a single ticker. Broaden your opportunity set and pressure test your thinking against different balance sheets, sectors and risk profiles.
- Target resilient income by checking out dividend payers that combine yield with staying power through the 5 dividend fortresses.
- Hunt for quality at a discount by reviewing the 28 high quality undervalued stocks that pair stronger fundamentals with more modest price tags.
- Dial down portfolio stress by focusing on companies in the 30 resilient stocks with low risk scores that score well on financial strength and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com