


EN
Amcor’s Quarterly Earnings Preview: What You Need to Know
Headquartered in Zurich, Switzerland, Amcor plc (AMCR) develops and manufactures flexible and rigid packaging for the nutrition, healthcare, beauty, and wellness industries. Its portfolio ranges from bottles, containers, films, bags, and closures to pharmaceutical packaging, giving the company a presence across several essential consumer and healthcare markets.
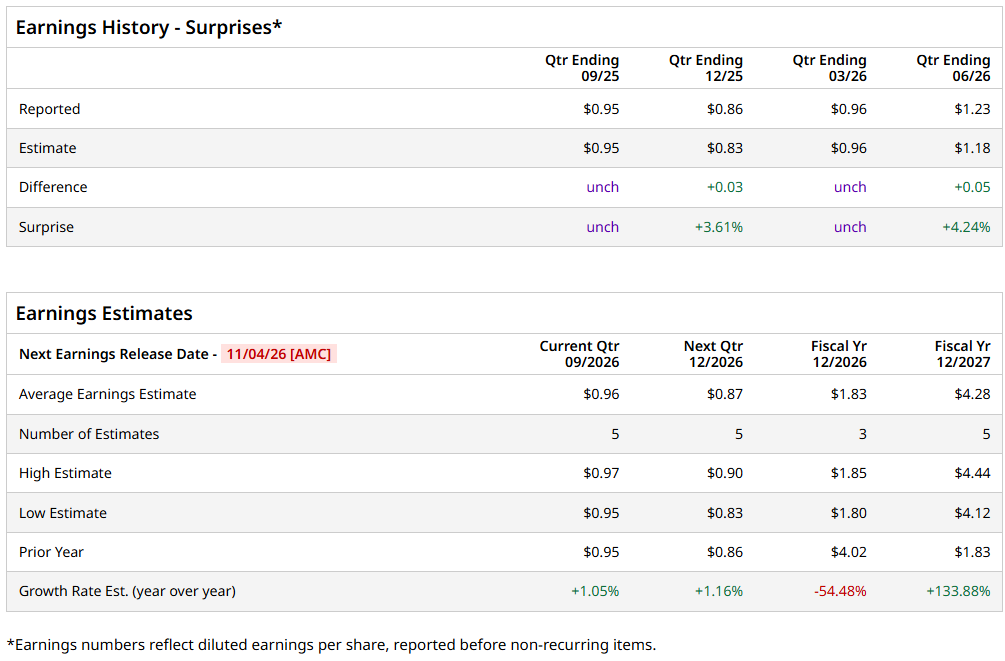
With a market cap of around $21.4 billion, Amcor is scheduled to report its Q1 FY2027 results on Wednesday, Nov. 4, after the market closes. Analysts expect diluted EPS of $0.96, compared with $0.95 in the year-ago quarter. Notably, the company has beaten EPS estimates in two of the past four quarters.
While the upcoming report will offer a fresh look at Amcor’s performance, its long-term outlook also warrants attention. Wall Street expects diluted EPS to reach $1.83 for full-year FY2026, down 54.5% year over year (YOY). For FY2027, however, forecasts climb to $4.28, representing a 133.9% increase from the preceding year.
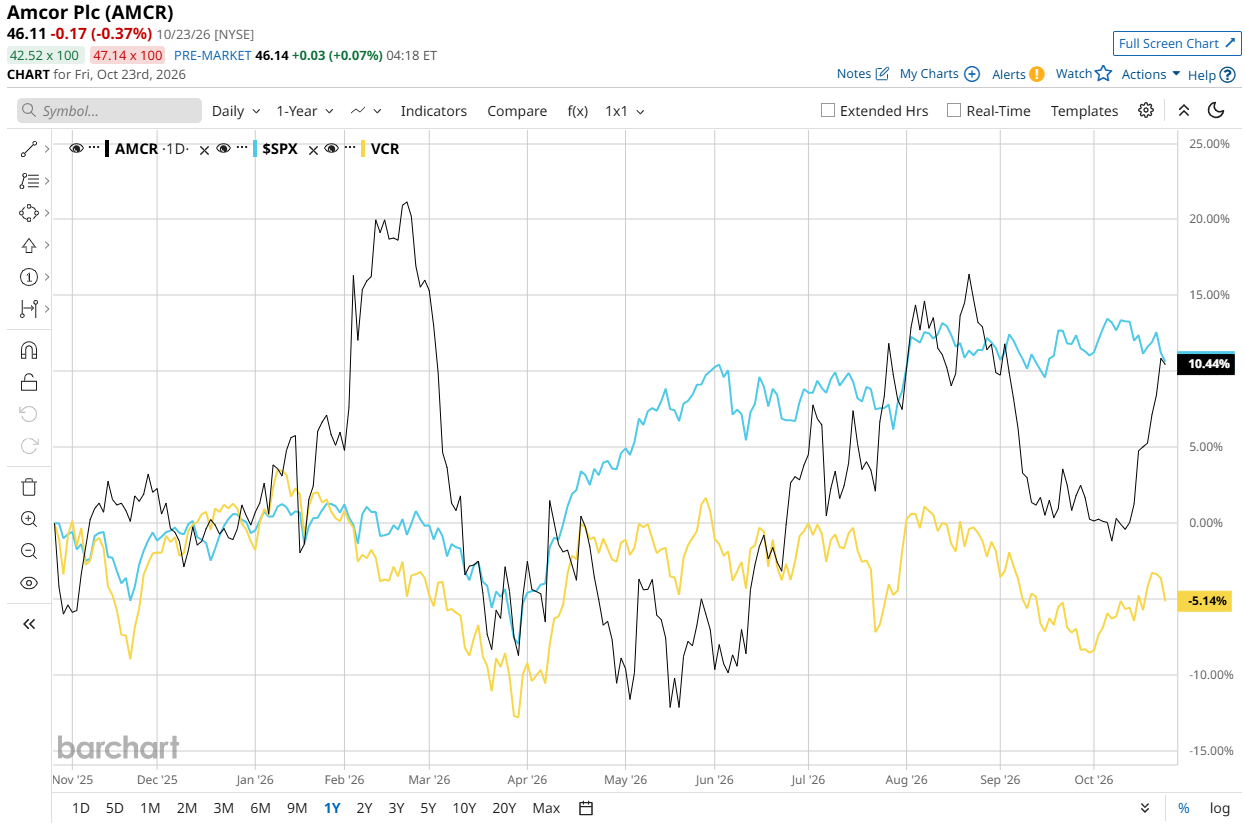
These projections provide context for a stock that has delivered solid gains over the past year, though it has not quite kept pace with the broader market. Amcor’s shares have risen 12.1% over the past 52 weeks, compared with a 13.1% gain for the S&P 500 Index ($SPX). The same pattern holds in 2026, with AMCR stock up 10.6% year-to-date (YTD), versus an 11.4% rise for the benchmark.
The sector backdrop adds another layer to that comparison. The Vanguard Consumer Discretionary Index Fund ETF Shares (VCR) has fallen 4% over the past 52 weeks and is also down 4% YTD. Against that weaker performance, Amcor’s gains look more substantial, even as the stock continues to trail the S&P 500 Index.
A closer look at Amcor’s recent results helps explain the stock’s momentum. In Q4 FY2026, the company reported net sales of $6.4 billion, up 25.9% YOY, while adjusted EPS rose 23% YOY to $1.23. The Berry integration also moved faster than planned, delivering $285 million in FY2026 synergies, 10% ahead of initial expectations.
These results helped shape a broadly positive view among analysts. Wall Street has assigned AMCR stock an overall “Moderate Buy” rating, with nine of the 17 analysts covering the stock recommending “Strong Buy.” The remaining eight maintain “Hold” ratings.
That sentiment is also reflected in analysts’ price targets. The average price target stands at $49.22, representing potential upside of 6.7%, while the Street-High target of $56 suggests a gain of 21.4% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.