


EN
Okeanis Eco Tankers (OB:OET) Gains From Rerouted Crude Flows, Is The Upside Already Priced In?
Recent commentary on Okeanis Eco Tankers (OB:OET) focuses on how geopolitical risk around key oil chokepoints has rerouted crude flows, lifting demand for VLCC and Suezmax capacity and supporting tanker rates for the Greek owner.
Okeanis Eco Tankers has ridden this tanker upswing hard, with a 30 day share price return of 18.35% and a 90 day gain of 55.50%. This has contributed to a powerful 170.26% year to date move, while the 1 year total shareholder return of 221.76% and 5 year total shareholder return above 15x original capital show how strong the longer term trend has been.
Scan for other crude tanker players riding similar long haul trade shifts with our curated list of 610 high quality undiscovered gems in the shipping and energy supply chain space.
After a move this steep in Okeanis Eco Tankers, the debate shifts. Is the recent run up already pricing in most of the story, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 26% Overvalued
On the most widely followed view, Okeanis Eco Tankers trades well above an assessed fair value of NOK694.63, compared with the last close at NOK877. As a result, the story now hinges on how much of the strong tanker backdrop is already embedded in the price.
The current valuation implies the share price already reflects very strong tanker markets, sustained operational outperformance and ongoing high dividend payouts. This leaves limited room for error and supports a bearish view that Okeanis Eco Tankers is overvalued.
See why 16 investors see Okeanis Eco Tankers as 26% overvalued.
Result: Fair Value of NOK694.63 (OVERVALUED)
Still, this narrative could crack if the large VLCC and Suezmax orderbook eases supply tightness, or if a weaker spot market hits Okeanis Eco Tankers' dividends.
Find out about the key risks to this Okeanis Eco Tankers narrative.
Another View: What Okeanis Eco Tankers' P/E Is Really Saying
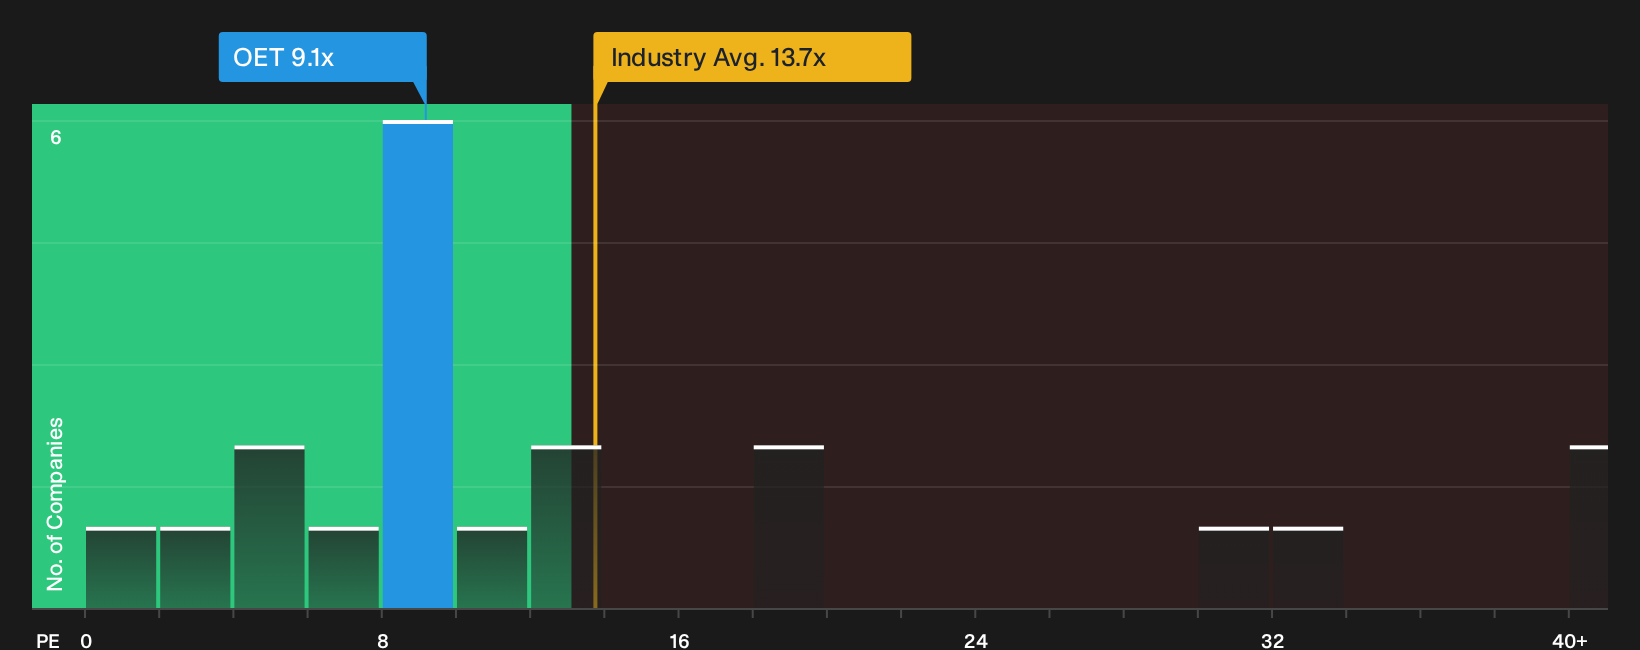
The first narrative paints Okeanis Eco Tankers as 26% overvalued versus a NOK694.63 fair value. Yet on earnings, the picture is more mixed. OET trades on a P/E of 9.1x, below both the European Oil and Gas industry at 13.7x and peer average at 17.3x, but above a fair ratio of 5.4x, which suggests the market could still compress the multiple from here. Is that a red flag about downside risk, or simply the price of paying up for high recent profitability and returns on equity?
For a closer look at how this earnings multiple stacks up against sector norms and the fair ratio, and what that might mean for future pricing power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Okeanis Eco Tankers so far. If you want to move quickly and base your own stance on the underlying data, start by weighing our 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Okeanis Eco Tankers?
Do not stop your research with Okeanis Eco Tankers. Broaden your watchlist with targeted ideas that match your goals, so you are not relying on a single tanker story.
- Target potential mispricings by scanning a curated set of 195 high quality undervalued stocks that combine solid fundamentals with pricing that may not fully reflect them.
- Strengthen your income playbook by reviewing a hand picked pool of 230 dividend fortresses built around robust cash generation and meaningful payout levels.
- Dial down portfolio stress by focusing on a carefully filtered 223 resilient stocks with low risk scores that screens for resilient balance sheets and calmer return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com