


EN
ServiceNow (NOW), What Is Drawing Fresh Attention Now?
Why ServiceNow’s AI rollout is back in focus
ServiceNow (NOW) is back in the spotlight after a rush of AI announcements, from its Arc autonomous agent and AI Passport framework to real-world deployments such as Thrive’s NextGen platform rollout.
This cluster of releases gives you something clear to track ahead of the October 28 Q3 report. The business is not just talking about agentic AI. Customers like Thrive are already routing hundreds of thousands of tasks through ServiceNow’s platform and reporting tangible workflow outcomes.
ServiceNow’s recent flood of AI product releases and security ambitions has coincided with a sharp move in the stock, with a 43.7% 90-day share price return and a 17.2% 30-day gain signaling strong momentum into the Q3 print, despite a 16% decline in 1-year total shareholder return and longer term gains over three and five years.
Scan beyond ServiceNow and size up other AI software and automation players showing strong momentum using the hand-picked 55 AI infrastructure stocks.
ServiceNow now trades on a rich AI story after a 44% 90 day run, yet still appears at a 42% intrinsic discount. Has the valuation already priced in the potential AI benefits or not?
Most Popular Narrative: 39% Undervalued
ServiceNow’s most followed valuation story pegs fair value at $260.58 per share, well above the last close at $158.96. This frames the current AI optimism against a much larger long term cash flow thesis according to John_Eric.
My own valuation work suggests ServiceNow remains meaningfully undervalued relative to its long-term cash-generating potential. Reasonable assumptions for revenue growth, operating leverage, free cash flow expansion, and terminal value produce an intrinsic value substantially above current trading levels.
See why 96 investors see ServiceNow as 39% undervalued.
Result: Fair Value of $260.58 (UNDERVALUED)
Still, the ServiceNow story hinges on continued AI workflow adoption and smooth integration of acquired platforms, both of which could disappoint if customer budgets or execution slip.
Find out about the key risks to this ServiceNow narrative.
Another view on ServiceNow’s valuation
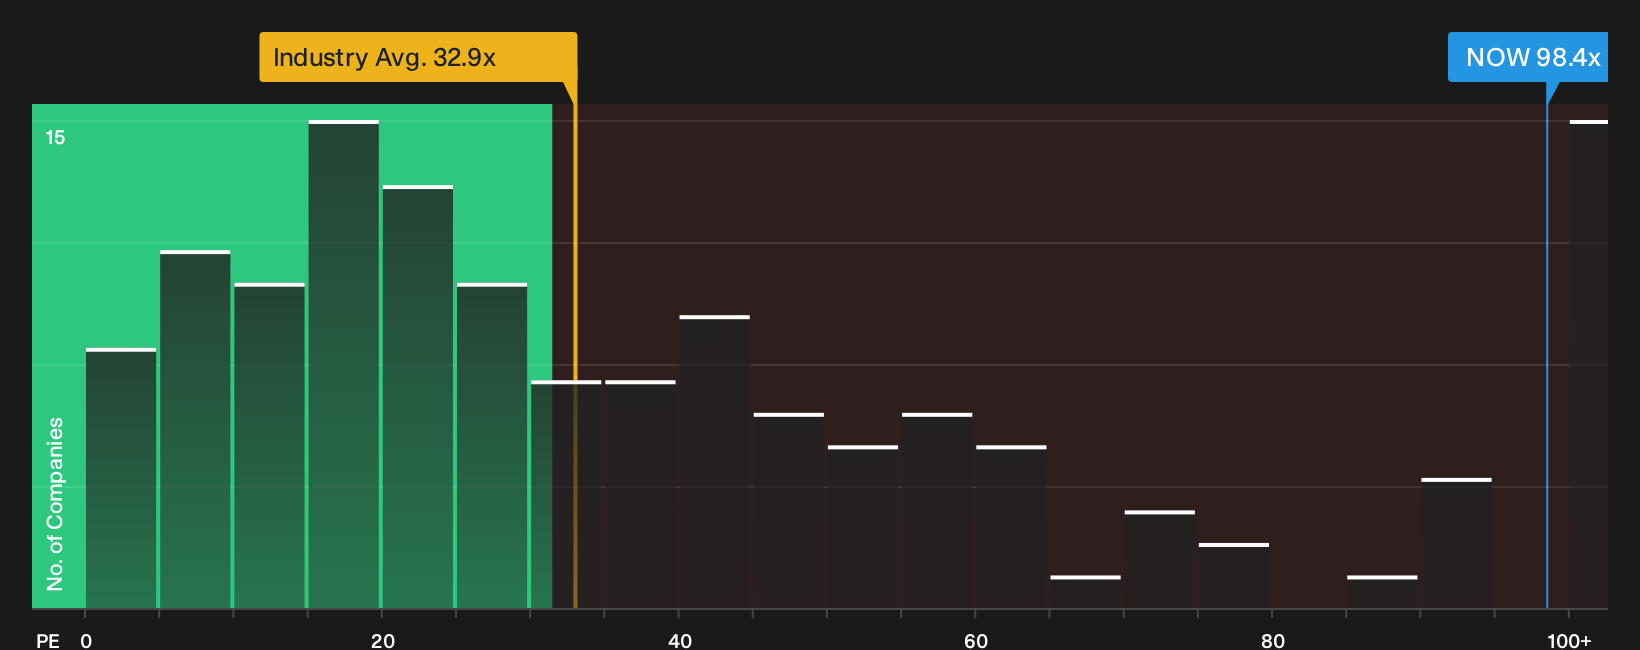
Switch lenses and the picture changes. ServiceNow trades on a P/E of 98.4x, while the US Software industry sits near 32.9x and close peers around 33.1x. The fair ratio sits at 51.5x, which points to rich pricing. Is this a quality premium or valuation risk building up?
Before leaning too hard on any one metric, it is worth stress testing what this P/E gap really implies about future expectations, competitive pressure, and how much margin for error remains for new buyers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on sentiment or a clear skew toward optimism around ServiceNow and its AI push. If you want to move quickly and build your own view off the underlying numbers, start with the 3 key rewards.
Looking for more investment ideas beyond ServiceNow?
You have a clear view on ServiceNow. Do not stop there. Use targeted stock lists to spot fresh opportunities before they are crowded trades.
- Hunt for quality at a discount by scanning companies on the 28 high quality undervalued stocks that pair strong fundamentals with appealing prices.
- Prioritise resilience first and focus on businesses in the 30 resilient stocks with low risk scores that carry sturdier balance sheets and lower risk scores.
- Spot potential future leaders early by filtering for companies in the 21 high quality undiscovered gems that have solid metrics but limited investor attention so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com