


EN
UK Stock Market Today: FTSE 100 Futures Slip On Firm PMIs And Budget Uncertainty
The Morning Bull - UK Market Morning Update Monday, 26 Oct 2026
UK stocks look set for a cautious but constructive open, with the main driver a clear pickup in domestic activity. A solid October PMI run has given investors a cleaner read on underlying UK momentum.
Manufacturing PMI printed at 52.8 and services at 53.1 in October, with the composite index also at 53.1. Those readings point to broad private sector expansion and have reinforced the sense that demand at home is holding up into the new week.
Stronger activity data can keep pressure on funding costs, since firmer growth often makes central banks slower to cut. That backdrop supports earnings resilience for UK focused companies, although it raises questions for businesses that rely heavily on cheaper credit or discretionary consumer spending.
The unresolved issue is how long this growth pulse can coexist with a soft retail picture and external risks such as supply chain disruption from the Middle East. The upcoming UK Autumn Budget now becomes the key test of whether fiscal policy leans into strength or prioritises restraint.
Stocks to Watch Before the Opening Bell
HUTCHMED (China) (HCM)
Fresh SAFFRON Phase III data put HUTCHMED in focus. Savolitinib, used with TAGRISSO, cut the risk of disease progression or death by 45% in MET driven EGFR mutated lung cancer and reduced the risk of death by 32%. A New Drug Application is already in front of the US FDA, which keeps regulatory timing in play.
AstraZeneca (AZN)
AstraZeneca is pushing two oncology updates at once. TAGRISSO plus savolitinib cut the risk of disease progression or death by 45% and reduced the risk of death by 32% in a Phase III lung cancer trial, with regulatory filings underway across major regions.
In gastric and gastroesophageal junction cancers, sonesitatug vedotin cut the risk of death by 42% in the overall trial and 53% in later line patients, with a reported manageable safety profile that could expand its treatment reach if regulators agree.
Top Movers
- Rockhopper Exploration (AIM:RKH) surged 6.89%.
- Serica Energy (AIM:SQZ) gained 5.23% as UK approval of the Jackdaw gas field supported North Sea sentiment.
- BP (LSE:BP.) advanced 4.35% after settling remaining Louisiana Deepwater Horizon claims and securing fresh LNG sales to Bangladesh.

Top Losers
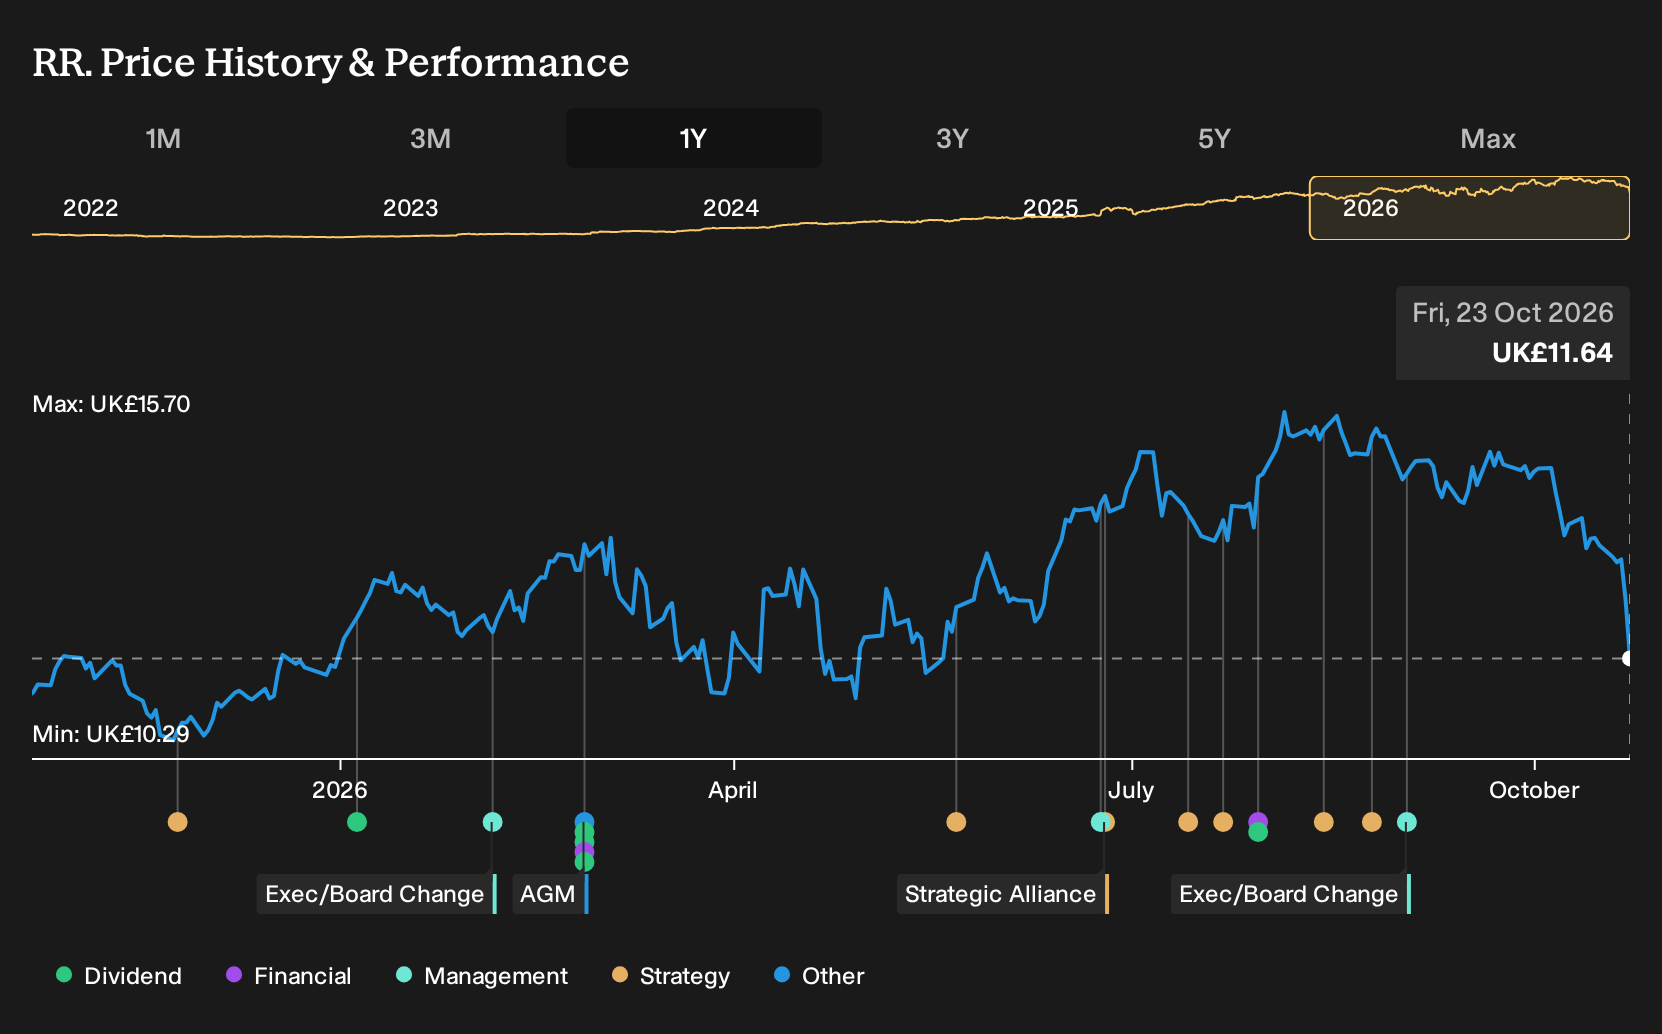
- Rolls-Royce Holdings (LSE:RR.) fell 7.57% after Safran's warning on wide body demand and ongoing concerns around valuation signals.
- Trainline (LSE:TRN) declined 6.56% after a Canaccord downgrade to Hold and a lower price target citing regulatory headwinds.
- Fresnillo (LSE:FRES) fell 6.21% after quarterly production figures highlighted softer gold and silver output versus the previous year.
On The Radar
UK housing and bank data collide with a heavy run of FTSE earnings, while Fed and ECB decisions shape the backdrop for gilts and sterling later in the week.
- UK CBI Distributive Trades, Mon 26 Oct. The October survey sits at a previous reading of 55 and a consensus of 47, so a print weaker than that would underline pressure on retailers already facing softer September sales and could weigh on UK consumer stocks.
- Standard Chartered, Wed 28 Oct. Q3 2026 results at 4:00 AM UTC put revenue mix and credit costs in focus for its Asia heavy franchise, which feeds directly into how investors price UK listed banks with emerging market exposure.
- Lloyds Banking Group, Thu 29 Oct. Q3 2026 numbers at 7:00 AM UTC highlight how net interest margins and arrears trends are holding up for the UK focused lender, a useful read across for domestic credit conditions and mortgage sensitive shares.
- Shell, Thu 29 Oct. Q3 2026 figures land with oil and gas prices back in the spotlight, so any shift in upstream cash flow or capital spending plans will matter for FTSE energy weightings and UK dividend income sentiment.
- BoE Consumer Credit and Mortgage Approvals, Thu 29 Oct. September consumer credit previously ran at £2.464b with a forecast of £2.2b, while approvals are seen near 56,000, and any clear break from those levels would shape expectations for UK borrowing costs and housing exposed stocks.
- NatWest Group, Fri 30 Oct. Q3 2026 results at 7:00 AM UTC bring attention to guidance and margins in its UK retail and commercial book, an anchor for how investors judge earnings resilience across the wider FTSE banking sector.
- BP, Fri 30 Oct. Q3 2026 earnings follow fresh LNG sales news, so production volumes and cash generation will be watched closely by holders of FTSE energy stocks looking at payout capacity and future investment plans.
Sector & Industry Watch
Energy: Oil rally keeps UK in focus
Energy has built on recent strength over the past week, helped by firm UK activity data and fresh LNG cargo contracts tied to BP. When producers gain ground, it often feeds through to petrol prices, household energy bills and the dividends many UK investors rely on.
The next swing factor is this week’s US crude and gasoline inventory data, which can quickly influence pricing for UK listed oil and gas groups.
Real Estate: Rate sensitive shares eye housing pulse
Real Estate has nudged higher over seven days while broader GB Market returns have softened slightly. That gap reflects investors weighing better UK PMI readings against still elevated borrowing costs, which shape mortgage affordability and commercial property deals.
The key domestic check is Thursday’s Bank of England mortgage approvals and lending numbers, giving a clearer view on how much higher rates are cooling housing demand.
Materials: Softer week despite stronger PMIs
Materials has retreated over the past week and month even with UK manufacturing PMI pointing to expanding factory output. That mix points to caution around miners and commodity linked businesses at a time when input costs and global demand signals remain mixed.
For anyone holding Metals and Mining or broader Materials funds, the data point to watch is Thursday’s US durable goods orders, since big ticket equipment demand often steers expectations for future metals use.
Consumer Discretionary: Retail strain caps early rebound
Consumer Discretionary has edged higher over seven days after a weaker year while the latest UK retail release showed sales volumes fell in September. Households facing higher mortgage payments and sticky inflation can pull back quickly on non essentials such as travel, fashion and electronics.
Today’s CBI Distributive Trades survey for October is the key read on how high street chains see demand heading into the Christmas period.
Pharmaceuticals & Biotech: AstraZeneca oncology data lift sector mood
Pharmaceuticals & Biotech has pushed higher over the past week, helped by strong cancer trial updates from AstraZeneca and HUTCHMED. Positive results for TAGRISSO plus savolitinib and AstraZeneca’s sonesitatug vedotin support the case for new treatments whose revenue streams are less tied to UK consumer spending.
The main catalyst now is progress on global regulatory reviews for these drugs, since milestones there can influence how investors think about longer term earnings across the sector.
Don't Wait For The Winners, Find Them
With UK mortgage approvals and consumer credit data in focus this week, it can help to start with a list of 221 resilient stocks with low risk scores that are geared toward steadier conditions if borrowing stays tight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com