


EN
How Transformation Roadmap At Forbo Holding Stock Has Changed Its Investment Story
- Forbo Holding has announced a transformation roadmap that shifts the business from a product-led approach to a customer and market segment focus, with medium-term targets for 2027 to 2029 that include 3% to 5% average annual net sales growth and an EBIT margin above 10% at group and divisional level.
- The plan hinges on sharpening sales performance management and timing heavier investment from 2027 onward, which puts execution quality and capital discipline at the center of Forbo Holding’s next phase.
- We now examine how this customer-focused transformation roadmap could reshape Forbo Holding’s broader investment narrative.
Scan how Forbo Holding’s customer-focused overhaul compares with peers by reviewing our hand picked list of solid balance sheet and fundamentals (207 results) that is already geared for disciplined execution and capital allocation.
What Is Forbo Holding's Investment Narrative?
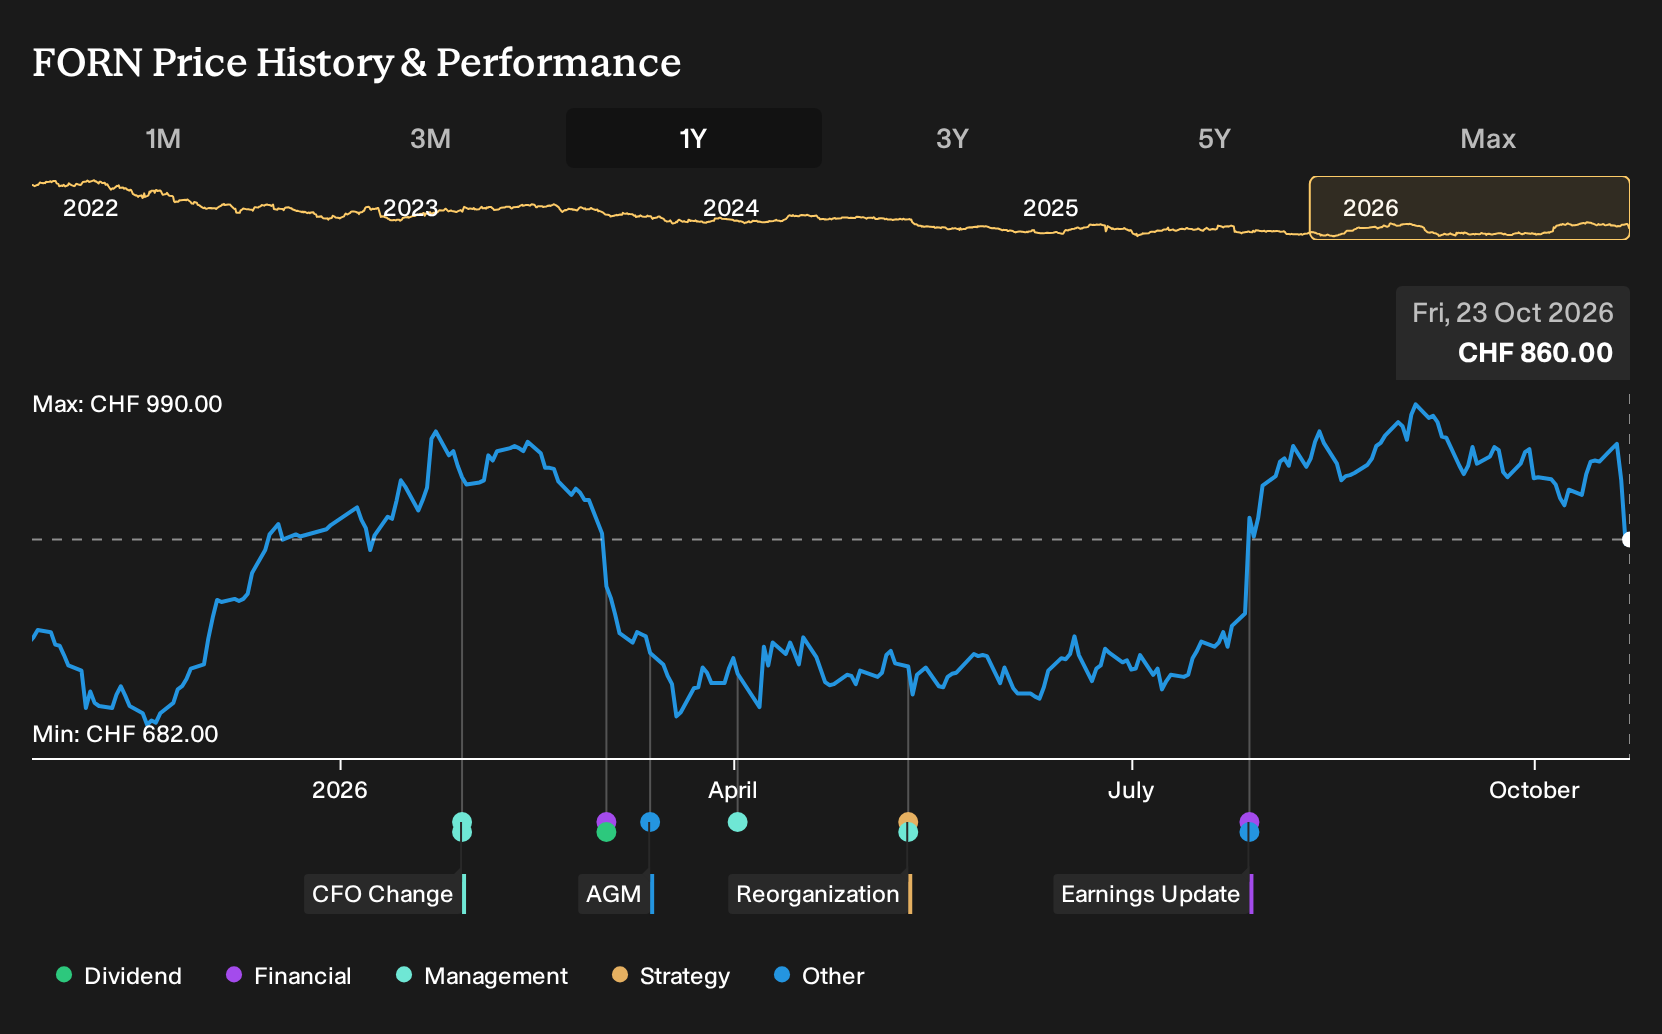
Forbo Holding asks you to believe that a focused, execution heavy industrial can still create value in fairly mature flooring and conveyor markets. The transformation roadmap tries to tackle exactly where the story has wobbled. Profitability has been under pressure, with net profit margin at 6.1% compared with 7.3% last year, and earnings declining over five years even as revenue and profit are now growing on the latest annual numbers. The share price has also been weak recently, down over the past month and quarter despite a stronger 1 year total return.
The new customer and segment oriented plan targets sharper sales discipline and heavier investment only from 2027. This means near term catalysts are mostly about operational delivery rather than big capex swings. Forbo Holding still runs capital intensive activities in Flooring Systems and Movement Systems, and funding relies fully on higher risk sources instead of customer deposits. Forecast earnings growth of 17.1% per year and a P/E of 18.6x compared with peer averages give the equity story some support, but the roadmap raises the bar on management execution.
That said, there is still a structural issue inside the Forbo Holding set up that could unsettle this whole transformation if ...
There's only one way to know the right time to buy, sell or hold Forbo Holding. Head to Simply Wall St's company report for the latest analysis of Forbo Holding's Fair Value.
Exploring Other Perspectives
Forbo Holding’s fair value estimates from the Simply Wall St Community span roughly CHF 966 to CHF 1,469 across 2 separate views, so you are looking at a wide gap between the lowest and highest conviction. Those opinions pre date the transformation roadmap, which could shift how you and other investors frame future scenarios.
Explore another Forbo Holding fair value estimate, including one that suggests it could be worth just CHF 966.33.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Forbo Holding research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Forbo Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Forbo Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Forbo Holding?
Once you have formed a view on Forbo Holding, it can help to widen the lens and compare it with other businesses that match the type of risk, balance sheet strength, or income profile you prefer.
The Simply Wall St Screener lets you do that quickly by filtering for companies that line up with your own criteria rather than someone else's checklist.
- If you care most about financial resilience and cleaner balance sheets, start with a list of solid balance sheet and fundamentals (207 results) that filters for businesses with stronger fundamentals and less fragile capital structures.
- If you are hunting for quality at a measured price, scan the 194 high quality undervalued stocks to see which stocks currently screen as both fundamentally sound and potentially mispriced.
- If reliable income matters to you, review the 230 dividend fortresses that highlights companies offering higher yields backed by more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com