


EN
MedinCell (ENXTPA:MEDCL) Stock Looks Overvalued Following Fresh Non Dilutive Financing
MedinCell has had a bumpy ride on the market in recent years, yet the share price still reflects big expectations for the business. With investors now focused on what the company can deliver, the immediate question is whether the current valuation is supported by its sales.
- Over the past 3 years, MedinCell has produced a very large share price gain of about 3.5x, which puts extra weight on whether its revenue base can justify that kind of re-rating.
- Since July 2026, the group has secured €41.8 million in non-dilutive financing. This may support its drug development pipeline while limiting pressure to raise fresh equity and affecting how investors think about sales-driven valuation.
- The analysts covering MedinCell have run their own numbers. See what analysts think MedinCell's shares could be worth.
The issue now is whether MedinCell's current share price around €25.44 is reasonable when judged against the scale of its sales.
If you want to pressure test MedinCell's share price against a broader set of businesses where sales and quality are in focus, compare it with 194 high quality undervalued stocks.
Has MedinCell Run Too Far on Sales?
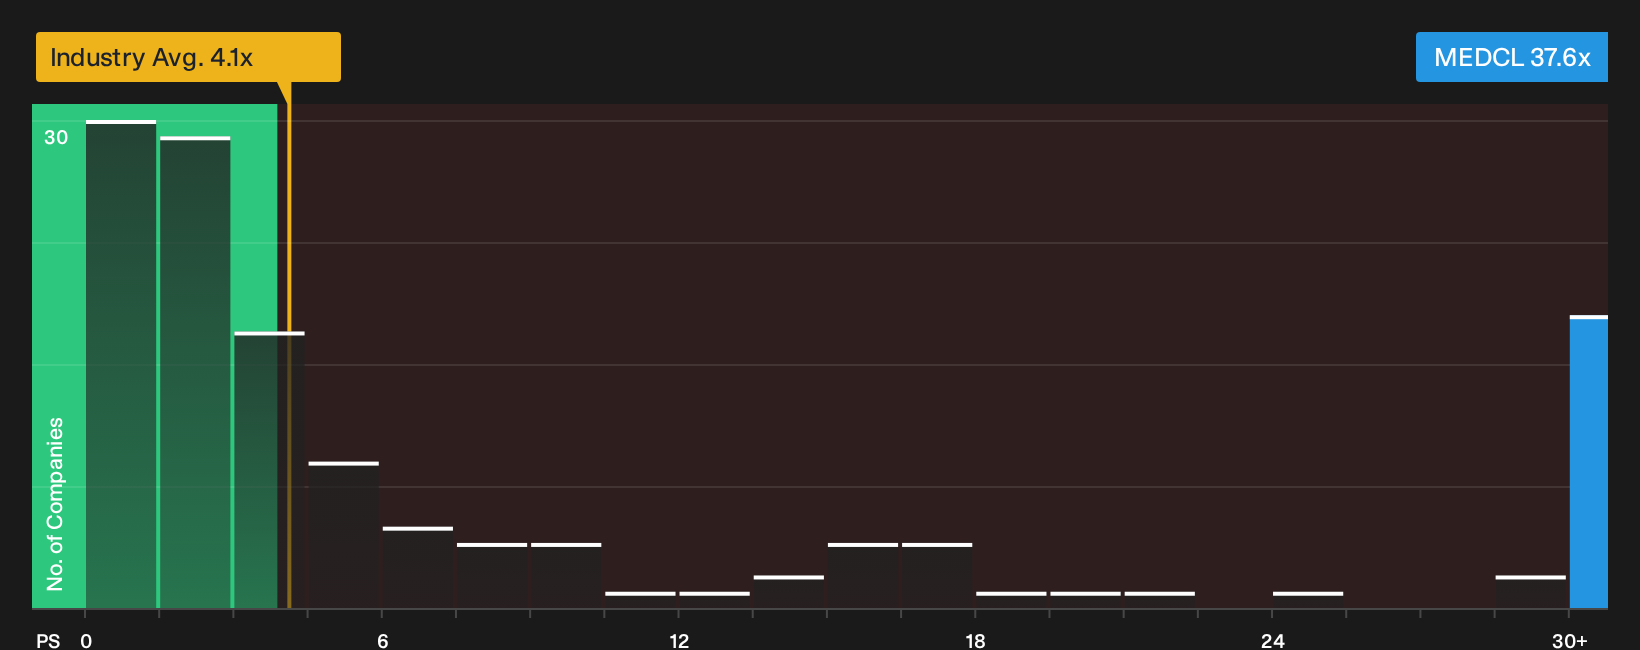
P/S is a useful lens for MedinCell because investors are mainly paying for its current and potential revenue rather than present earnings. The stock trades on a P/S of about 37.6x, which is much higher than the Pharmaceuticals industry average of roughly 2.6x and a peer group closer to 4.6x. Against a tailored fair multiple that adjusts for MedinCell's growth profile, profitability, size and risk, the current ratio screens as overvalued, and the gap is so wide that the model is effectively flagging an extreme premium rather than a fine tuned target level.
Because the recent €41.8 million of non dilutive financing removes some balance sheet pressure, the high P/S suggests investors are willing to pay a steep price for MedinCell's development pipeline and future commercialisation prospects. The figures indicate that buyers today are accepting a valuation that already prices in a strong revenue story compared with many listed drug developers, so you would need to be comfortable that the existing sales base and future contracts can support that kind of multiple over time. Explore the numbers behind MedinCell's P/S valuation.
The MedinCell Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the MedinCell valuation puzzle leaves off and explain which combinations of future growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than it is today. Each scenario links its figures to a concrete view of how MedinCell's expansion prospects, profitability path and key risks might change, giving you a reference point you can revisit as fresh information becomes available.
One of the top community narratives on MedinCell: 27% undervalued
"Positive real-world outcomes data for UZEDY, including reductions in relapse and hospitalization, responds to the growing priority among payers..."
Discover why this Narrative puts MedinCell at 27% undervalued.
Before acting on MedinCell’s valuation, weigh who is steering it
Price tags and pipelines only tell part of the story, because the people making the capital allocation calls and how they are rewarded can pull your eventual return in very different directions. See who runs MedinCell and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com