


EN
Charles River Laboratories’ Q3 2026 Earnings: What to Expect
Founded in 1947, Charles River Laboratories International, Inc. (CRL) is a pharmaceutical research services company that now commands a market cap of nearly $16.5 billion. Its portfolio covers laboratory testing, drug discovery, preclinical development, safety assessment, research models, cell therapy development, and manufacturing, giving the company a broad presence across the drug development process.
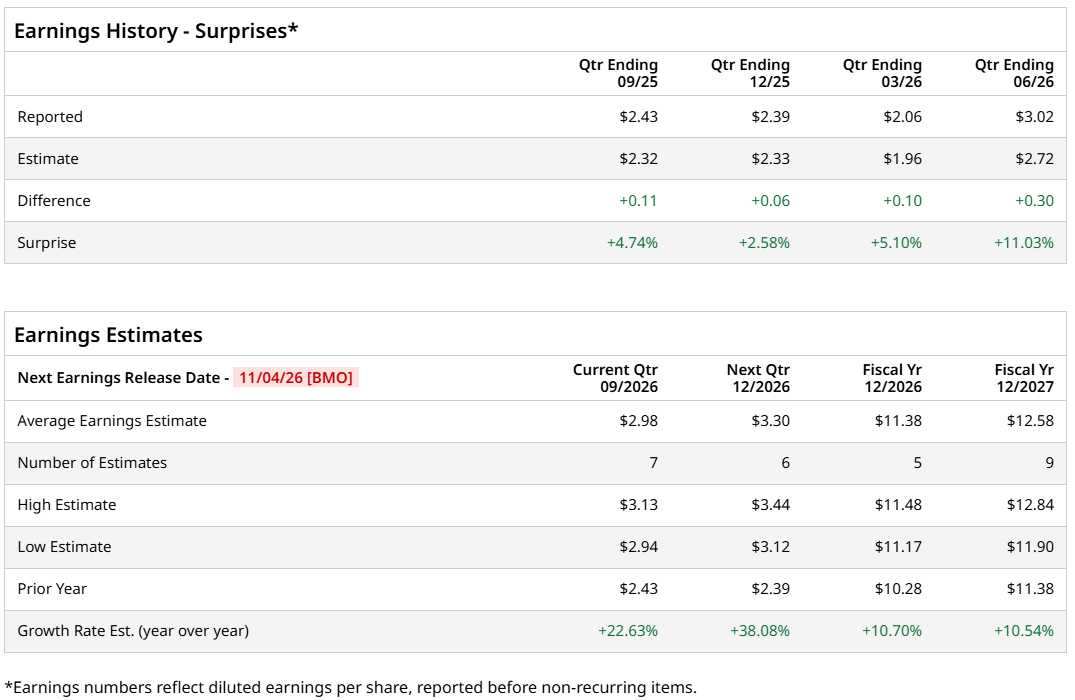
The Wilmington, Massachusetts-based Charles River is scheduled to report its Q3 FY2026 results on Wednesday, Nov. 4, before the market opens. Analysts are looking for diluted EPS of $2.98, compared with $2.43 in the year-ago quarter. Expectations are buoyed by the company’s recent consistency, with earnings beating analyst estimates in each of the past four quarters.
The earnings outlook also points to continued growth beyond the next report. Wall Street expects diluted EPS to reach $11.38 for full-year FY2026, representing year-over-year (YOY) growth of 10.7%. Meanwhile, for FY2027, forecasts rise to $12.58, implying a 10.5% increase from the preceding year.
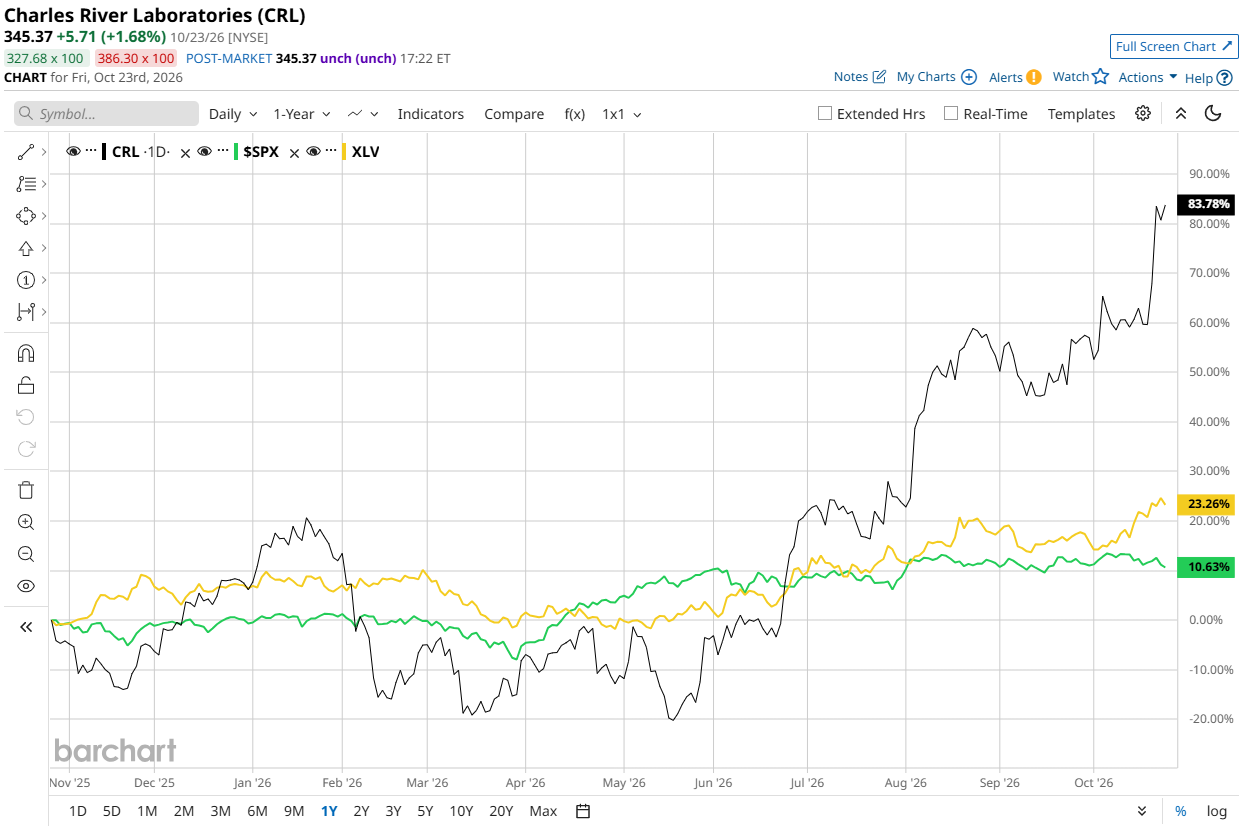
The optimism has found a clear reflection in the stock market, where CRL stock has comfortably outpaced the broader market. Shares have surged 80.9% over the past 52 weeks, while the S&P 500 Index ($SPX) gained 13.1%. The contrast remains just as striking in 2026, with CRL stock up 73.1% year-to-date (YTD), against an 11.4% gain for the benchmark.
The comparison with healthcare stocks tells a similar tale. The State Street Health Care Select Sector SPDR ETF (XLV) has gained 22.8% over the past 52 weeks and risen 15.8% in 2026. Although both advances are substantial, they remain well below Charles River's performance, underscoring the stock’s considerable outperformance across both periods.
Behind the rally lies a combination of improving demand for preclinical drug development, stronger-than-expected quarterly results, and a more encouraging earnings outlook. Charles River’s Q2 performance provided tangible support for that optimism, with revenue reaching $1 billion and surpassing estimates of approximately $978 million. Adjusted EPS also came in ahead of expectations at $3.02, compared with forecasts of $2.73.
Demand indicators offer further encouragement, as Discovery and Safety Assessment bookings rose 12.6% sequentially to $701 million, lifting the company’s backlog to $1.97 billion. Building on these results, Charles River has raised its 2026 adjusted EPS guidance to $11.15–$11.45 from the earlier range of $10.80–$11.30 and projects free cash flow of $400–$420 million.
Analyst sentiment reflects the growing confidence, with Wall Street assigning CRL stock an overall “Strong Buy” rating. Of the 16 analysts covering the name, 13 recommend “Strong Buy,” one has a “Moderate Buy” rating, and two maintain “Hold” recommendations.
Although the stock is already trading above its average price target of $320.93, analysts see further upside, with the Street-High target of $357 pointing to additional gains of 3.4% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.