


EN
What Microsoft Earnings Preview Means For Shareholders
- Recent announcements around Microsoft's AI focused alliances, product integrations and data center plans have arrived just as markets prepare for the company’s next earnings report and a closer look at how AI spending lines up with revenue and cash generation.
- Partnerships spanning Boehringer Ingelheim’s digital patient twins, CAS scientific connectors, legal data integrations and governance tools around Agent 365 give investors a clearer view of how Microsoft is trying to turn heavy AI infrastructure outlay into concrete enterprise use cases.
- Next, the discussion will look at how this earnings focused AI buildout story could reshape Microsoft's broader investment narrative.
Scan how Microsoft is wiring enterprise AI into daily workflows, then widen your watchlist with 55 AI infrastructure stocks that could benefit from the same buildout in data centers and tooling.
Microsoft Investment Narrative Recap
To own Microsoft, you need to believe its huge AI and cloud buildout can keep pulling more workloads onto Azure and Copilot, and that usage over time comfortably supports US$175b to US$190b of planned 2026 capex. The near term catalyst is clear. Investors want this week’s earnings to show AI revenue and cash generation tracking that spend.
The biggest risk is that AI demand or pricing falls short of the infrastructure already committed, which could pressure free cash flow and margins just as scrutiny of AI tax breaks and off balance sheet obligations rises. Recent partnership news shapes the story, but does not yet change that core risk reward equation.
The Boehringer Ingelheim collaboration on digital patient twins is one of the clearest operational links between Microsoft’s AI stack and real enterprise workloads. It leans on Azure, security and data center modernization in a highly regulated field, which gives investors a concrete example of how AI agents and models can be embedded in complex, long cycle industries.
For catalysts, this kind of pharma grade deployment matters because it tests whether Microsoft’s massive AI infrastructure and tools like Foundry and Agent 365 can support mission critical applications at scale. Execution risk sits in proving reliability, governance and economics across many such clients. Earnings and cash flow will indicate whether projects like this are turning into durable, high usage contracts.
How Microsoft’s AI Build Shapes Analyst Expectations
Analysts looking at Microsoft today are effectively stress testing whether the AI infrastructure surge can carry enough usage to make future earnings targets realistic. The key assumptions in the consensus work off a projected 19.8% annual revenue growth rate over the next three years, paired with some compression in profit margins from 40.3% today to 38.0% by year three. That combination reflects a view that heavier AI and data center costs get partly offset by higher software and cloud volumes rather than fully passed through.
Earnings forecasts sit at the center of this story. Current profit is estimated at US$133.7b, with analyst consensus pointing to US$216.7b by 2029 and some outliers as high as US$262.8b. Moving from US$133.7b to US$216.7b implies roughly a 62% earnings increase, which is a substantial jump relative to the already large base. For readers tracking per share impact, that 2029 view lines up with earnings per share of US$29.41. Forecasts also assume a small decline in share count of about 0.09% a year for the next three years.
Valuation work then layers on what sort of multiple might match those profit assumptions. To align with current analyst targets, Microsoft would need to trade on a P/E of 26.3x in 2029 earnings terms, compared with 29.4x today and the US software sector sitting around 30.8x on this framework. That P/E step down is important for anyone considering the risk of overpaying for AI, since it assumes the business grows into its current share price rather than relying on further multiple expansion.
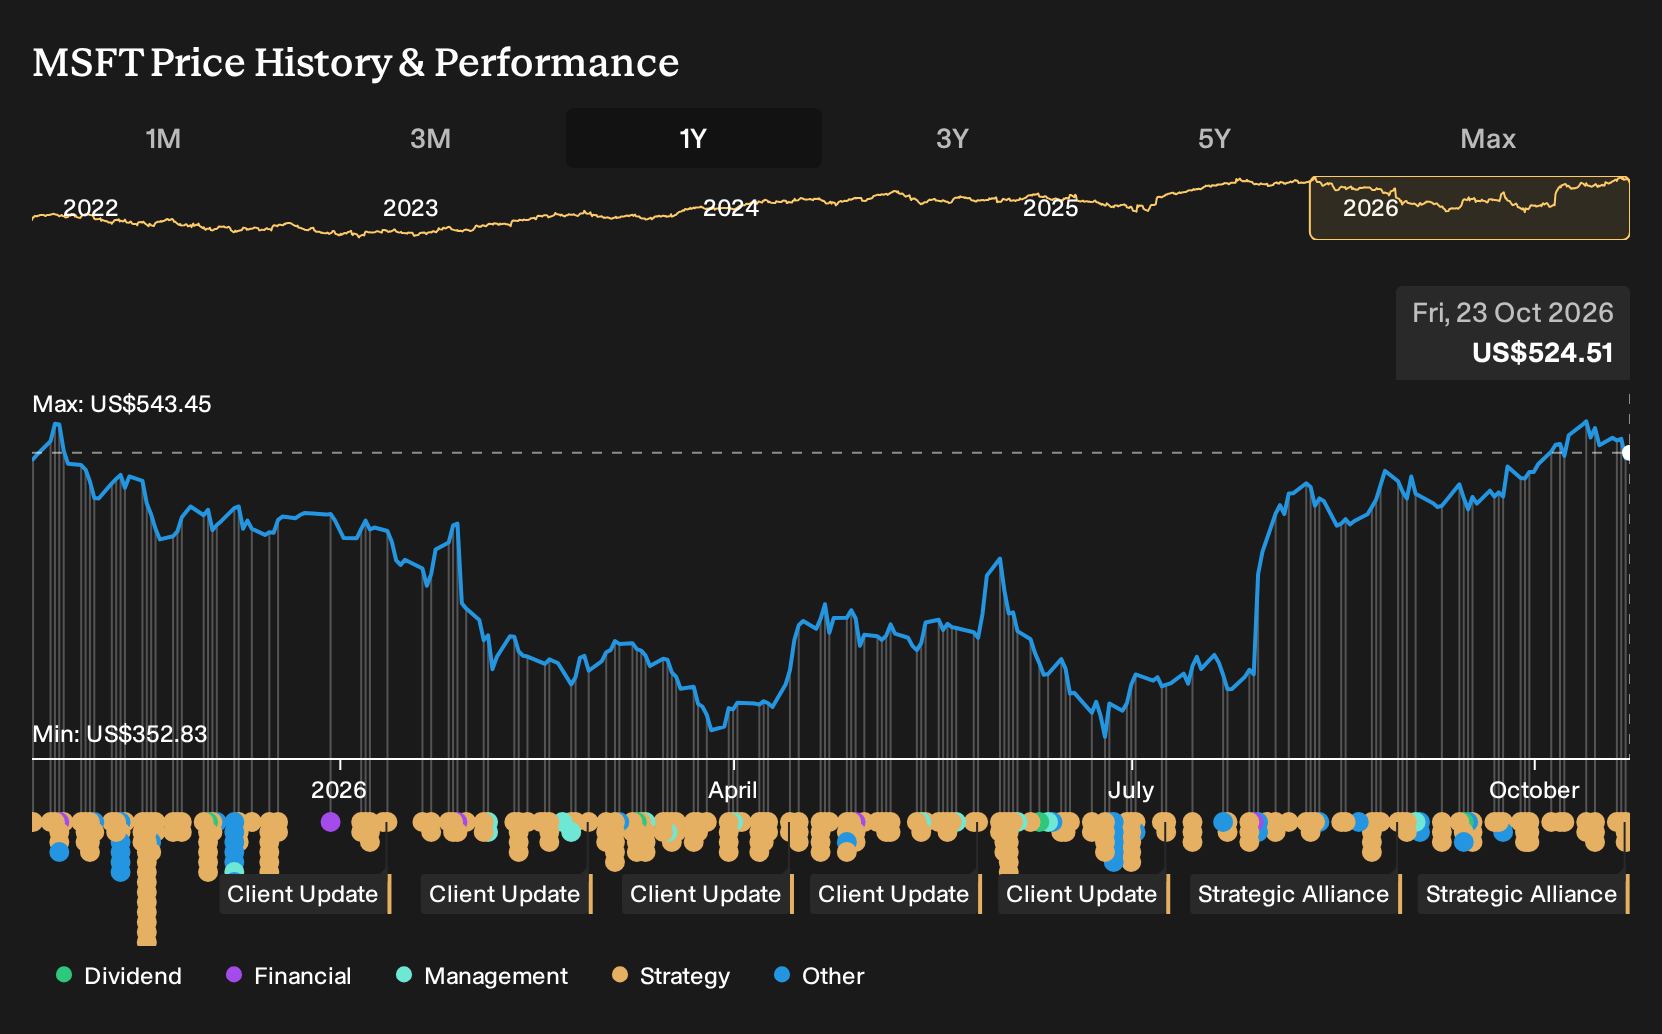
On the revenue line, the same 2029 snapshot has analysts modeling US$570.0b of annual sales and US$216.7b of profit. The consensus price target of US$599.24 against a current share price of US$529.05 implies 11.7% potential upside baked into these numbers, although the spread between the most upbeat US$870.00 target and the most cautious US$440.00 shows there is substantial disagreement about how efficiently the AI and cloud push converts into cash. For investors, the key issue is how much confidence to place in a model that combines higher capital intensity, slightly lower margins and a lower P/E with very large absolute levels of revenue and earnings.
Microsoft's narrative, as reflected in analyst models, points to US$570.0b revenue and US$216.7b earnings by 2029. That profile is based on 19.8% yearly revenue growth and roughly a 62% earnings increase from US$133.7b today.
Uncover why Microsoft's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view treats Microsoft’s AI alliances as a margin risk rather than a growth engine. The most cautious analysts were penciling in 15.5% yearly revenue growth and US$206.3b of earnings by 2029, with a P/E of 21.6x. That is a far more conservative story. Use this new Blazor and Copilot news to reassess which narrative you find more convincing.
Explore 65 other Microsoft fair value estimates, including one that suggests as much as 24% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Microsoft research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Microsoft. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Microsoft's overall financial health at a glance.
Looking for more investment ideas beyond Microsoft?
Once you have formed a view on Microsoft, it helps to compare that thesis with opportunities across different styles of stocks so your portfolio does not rely on a single AI story.
- For investors hunting for potential high risk, high reward situations, scan the 8 elite penny stocks with strong financials that already show stronger balance sheets and cash profiles than many peers.
- If your priority is resilience over excitement, focus on 30 resilient stocks with low risk scores, which score well on both financial strength and lower volatility metrics.
- For readers who want quality businesses with room to be re rated, review the 21 high quality undiscovered gems, which pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com