


EN
DICK'S Sporting Goods (DKS) Following Its Earnings Reset Looks Pricey to Some Investors
DICK'S Sporting Goods stock moves after recent performance shift
DICK'S Sporting Goods (DKS) has drawn fresh investor attention after a sharp swing in performance, with the share price up about 6% over the past month but down roughly 32% over the past 3 months.
Viewed over a longer stretch, DICK'S Sporting Goods combines a three year total shareholder return of 47.72% with a one year total shareholder return that is down 35.16%. This hints that earlier momentum has cooled and investors are reassessing both growth prospects and risk around the current US$144.67 share price.
Spot fresh momentum in DICK'S Sporting Goods, then compare it with a hand picked 29 high quality undervalued stocks that share stronger balance sheets and cash generation profiles.Bulls point to DICK'S Sporting Goods recent sales and profit growth, while bears focus on the sharp share price pullback. Which story does the current valuation actually support?
Most Popular Narrative: 28% Overvalued
On the numbers, the most followed narrative pegs fair value for DICK'S Sporting Goods at about $112.77 per share, which sits well below the recent $144.67 close and frames the stock as materially expensive at current levels.
Management's structural response to the guidance revision rests on a consistent rhetorical architecture. The DICK'S business is performing, the headwinds are real but temporary, and the investments being made today are exactly the right investments. Each claim is internally defensible. Taken together, they produce a framework in which virtually any near-term result can be framed as consistent with long-term strategy. That is not an accusation; it is a description of how the communication is built.
See why 2 investors see DICK'S Sporting Goods as 28% overvalued.
According to LunaRodas, this gap between the $112.77 fair value estimate and the live price leaves DICK'S Sporting Goods trading at roughly a 28.3% premium, with the earnings reset and Foot Locker drag playing a central role in that view while the core DICK'S chain and newer assets like GameChanger and the Media Network are treated as offsets rather than full cures for the current pressure.
Result: Fair Value of $112.77 (OVERVALUED)
Still, the Foot Locker earnings reset and a more aggressive promotional environment could pressure the DICK'S Sporting Goods narrative if those headwinds persist longer than management expects.
Find out about the key risks to this DICK'S Sporting Goods narrative.
Another View: What DICK'S Sporting Goods Multiples Are Saying
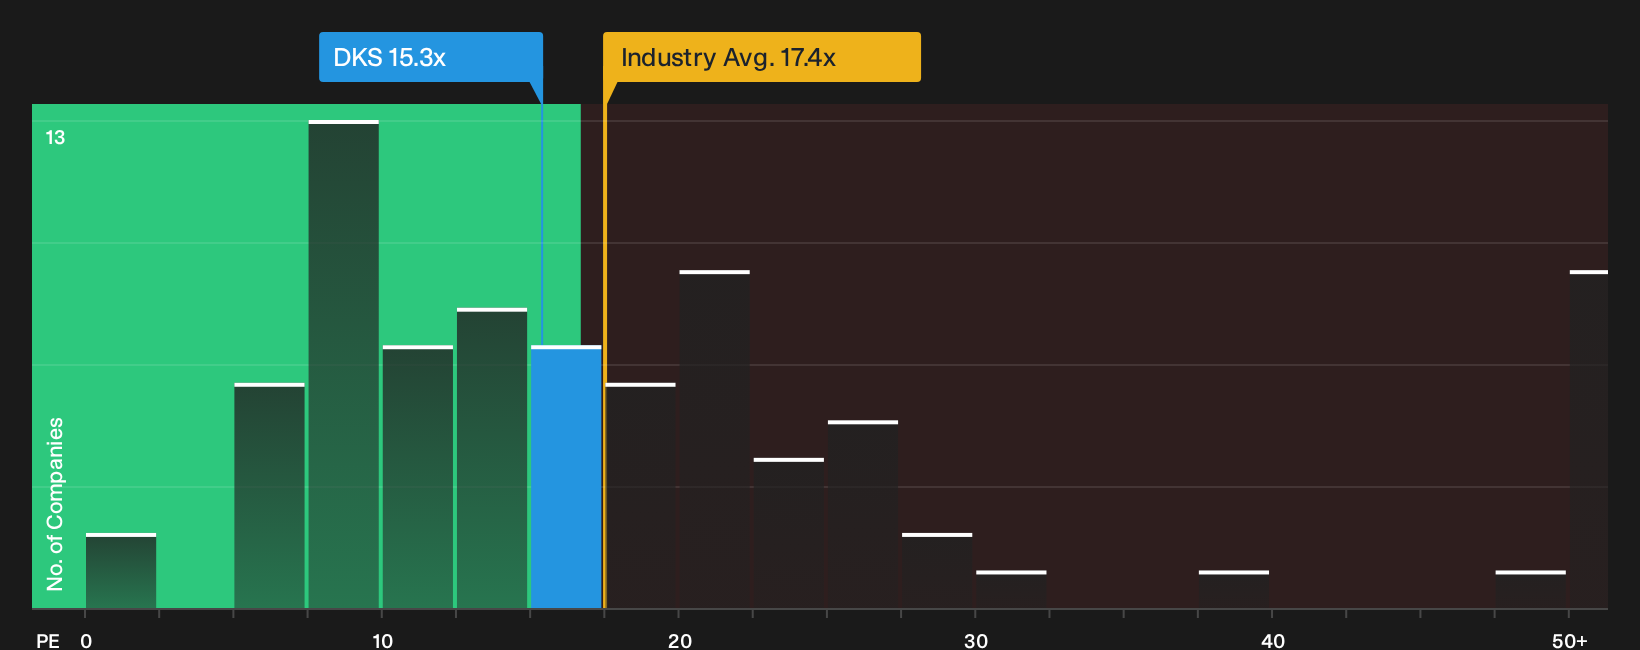
The narrative pegs DICK'S Sporting Goods at $112.77, yet the market is paying $144.67. On simple P/E math, the picture looks softer. DKS trades at 15.3x earnings, which is lower than both the US Specialty Retail industry at 17.4x and peers at 23x, and also below a fair ratio of 18.7x. That gap points to investors already pricing in some business risk rather than blue sky optimism, so the question is how much of the earnings reset is arguably in the quote already.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around DICK'S Sporting Goods valuation are clear. Move quickly, review the facts yourself, and weigh both the 3 key rewards and 4 important warning signs.
Looking for more DICK'S Sporting Goods style ideas?
Do not stop your research with DICK'S Sporting Goods alone. Use a broader watchlist so you can compare quality, value, and risk across plenty of alternatives.
- Target steady income by reviewing a curated set of higher yielding opportunities through the 5 dividend fortresses.
- Hunt for quality at a discount by scanning the 21 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Prioritize resilience by checking a list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio against weaker counterparts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com