


EN
How Investors May Respond To Whirlpool Stock Before Earnings Report
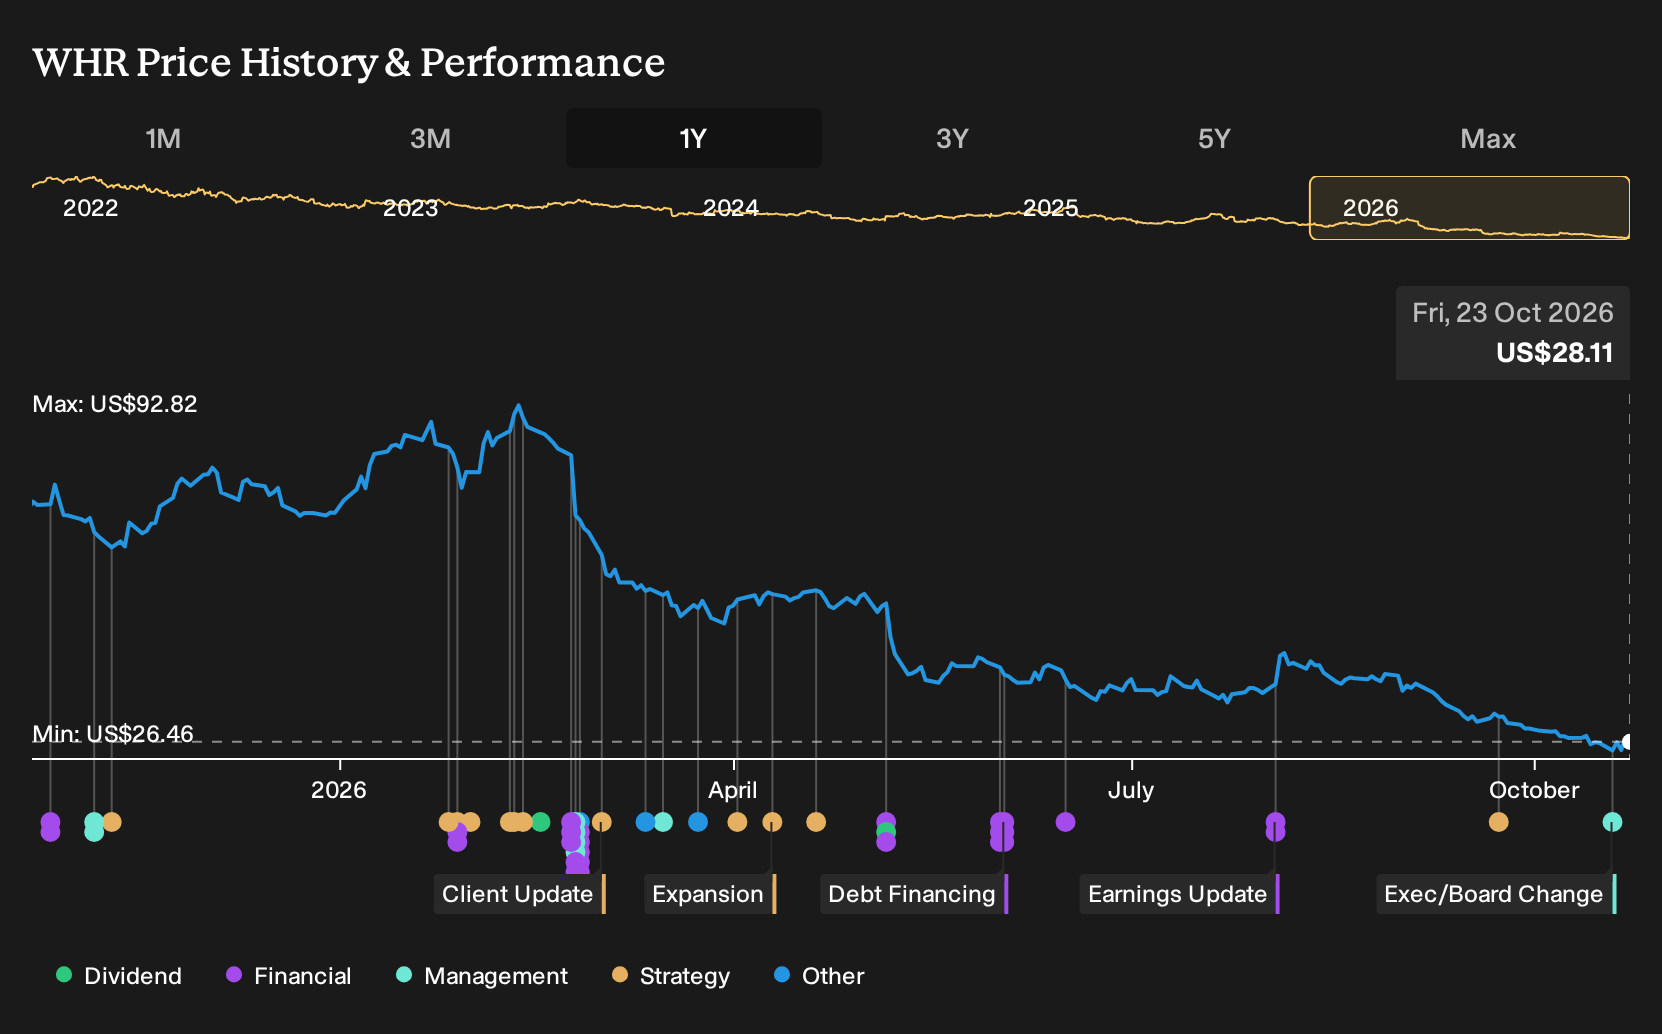
- Whirlpool appointed Karin Risi, a former Vanguard senior executive with more than 30 years in asset and wealth management, to its board on 19 October 2026 and scheduled its Q3 2026 earnings release for 26 October after market close.
- The combination of Risi’s capital allocation background and Whirlpool’s upcoming earnings report after recent revenue declines puts board level financial oversight and near term operating pressure in clear focus for investors.
- We will look at how Whirlpool's investment narrative is shaped by the looming Q3 earnings release after recent revenue softness.
Compare Whirlpool's setup ahead of earnings with a curated group of companies that pair solid finances with boardroom discipline using our list of solid balance sheet and fundamentals (24 results).
Whirlpool Investment Narrative Recap
To own Whirlpool, you need to be comfortable with a cyclical appliance producer that is leaning heavily on cost cuts, factory consolidation and a richer product mix to rebuild profitability while core U.S. and European markets stay soft. With industry demand guided down and 2026 EBIT margin around 4%, the near term hinge point is execution on cost savings and price discipline.
The Q3 release on 26 October, with revenue expected to decline 3.1% year on year after a 6.8% drop last quarter, keeps near term pressure squarely on earnings quality and cash generation. The biggest current risk is that weak volumes, heavy promotions and higher interest expense keep margins and interest cover strained.
The most relevant development for this setup is Whirlpool’s appointment of Karin Risi to its board, with seats on the Finance and Human Resources committees. Her background spans enterprise strategy, product oversight and financial performance at a very large investment platform, which speaks directly to capital allocation, return hurdles and balance sheet stewardship.
For you as a shareholder, this matters mainly because the investment case already hinges on multi year restructuring, lower leverage and disciplined reinvestment into higher margin categories like SDA Global. Stronger board oversight on funding mix, interest costs and incentive design may influence how quickly cost savings translate into more durable EBIT margins if operating conditions stay difficult.
Whirlpool earnings setup through the analyst lens
Whirlpool's current analyst blueprint points to revenues of $16.3b and earnings of $311.7m by 2029, supported by forecast yearly revenue growth of 3.0% and an earnings increase of about $141.7m from $170.0m today.
Uncover how Whirlpool's fair value indicates a 68% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Not every analyst sees Karin Risi’s appointment as a fix for Whirlpool’s pressure points. The most cautious forecasts before this news were built around slower progress on margins, with 2029 earnings at about $223.2m on roughly $16.0b of revenue. That view is far more pessimistic than consensus, and it may shift as board changes and Q3 results land.
Explore 3 other Whirlpool fair value estimates, including one that suggests it could be worth just $45.67!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Whirlpool research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Whirlpool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Whirlpool's overall financial health at a glance.
Looking for more Whirlpool investment ideas?
Once you have weighed Whirlpool on its own merits, it can help to set it beside other businesses with different profiles so you can see what really suits your approach.
- If you want potential upside coupled with balance sheet strength, scan through our 29 high quality undervalued stocks that may match a value focused checklist.
- For income focused investing where reliability and payout level both matter, review a curated set of 5 dividend fortresses that might fit a yield driven playbook.
- When capital preservation ranks high on your list, filter for companies in our 30 resilient stocks with low risk scores that score well on financial resilience and risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com