


EN
3 UK Stocks Estimated To Be Up To 43.6% Below Their Intrinsic Value
The United Kingdom's stock market has recently faced challenges, with the FTSE 100 index experiencing declines due to weak trade data from China, highlighting global economic interconnectedness. In such a climate, identifying stocks that are estimated to be trading below their intrinsic value can present opportunities for investors seeking potential long-term growth amidst broader market uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.48 | £2.49 | 40.6% |
| Skillcast Group (AIM:SKL) | £0.40 | £0.77 | 48.3% |
| Property Franchise Group (AIM:TPFG) | £4.16 | £7.35 | 43.4% |
| LSL Property Services (LSE:LSL) | £2.57 | £4.56 | 43.6% |
| IG Group Holdings (LSE:IGG) | £9.365 | £15.72 | 40.4% |
| Hollywood Bowl Group (LSE:BOWL) | £2.725 | £5.16 | 47.2% |
| Gamma Communications (LSE:GAMA) | £10.91 | £21.22 | 48.6% |
| Frontier Developments (AIM:FDEV) | £5.33 | £8.92 | 40.2% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.716 | £1.37 | 47.7% |
| Balfour Beatty (LSE:BBY) | £8.265 | £16.23 | 49.1% |
Let's review some notable picks from our screened stocks.
CAB Payments Holdings (LSE:CABP)
Overview: CAB Payments Holdings plc operates through its subsidiaries to offer business-to-business cross-border payments and foreign exchange services across various regions including the Americas, the United Kingdom, Europe, Africa, the Middle East, and Asia with a market cap of £204.11 million.
Operations: CAB Payments Holdings plc generates revenue from its business-to-business cross-border payments and foreign exchange services, amounting to £84.43 million.
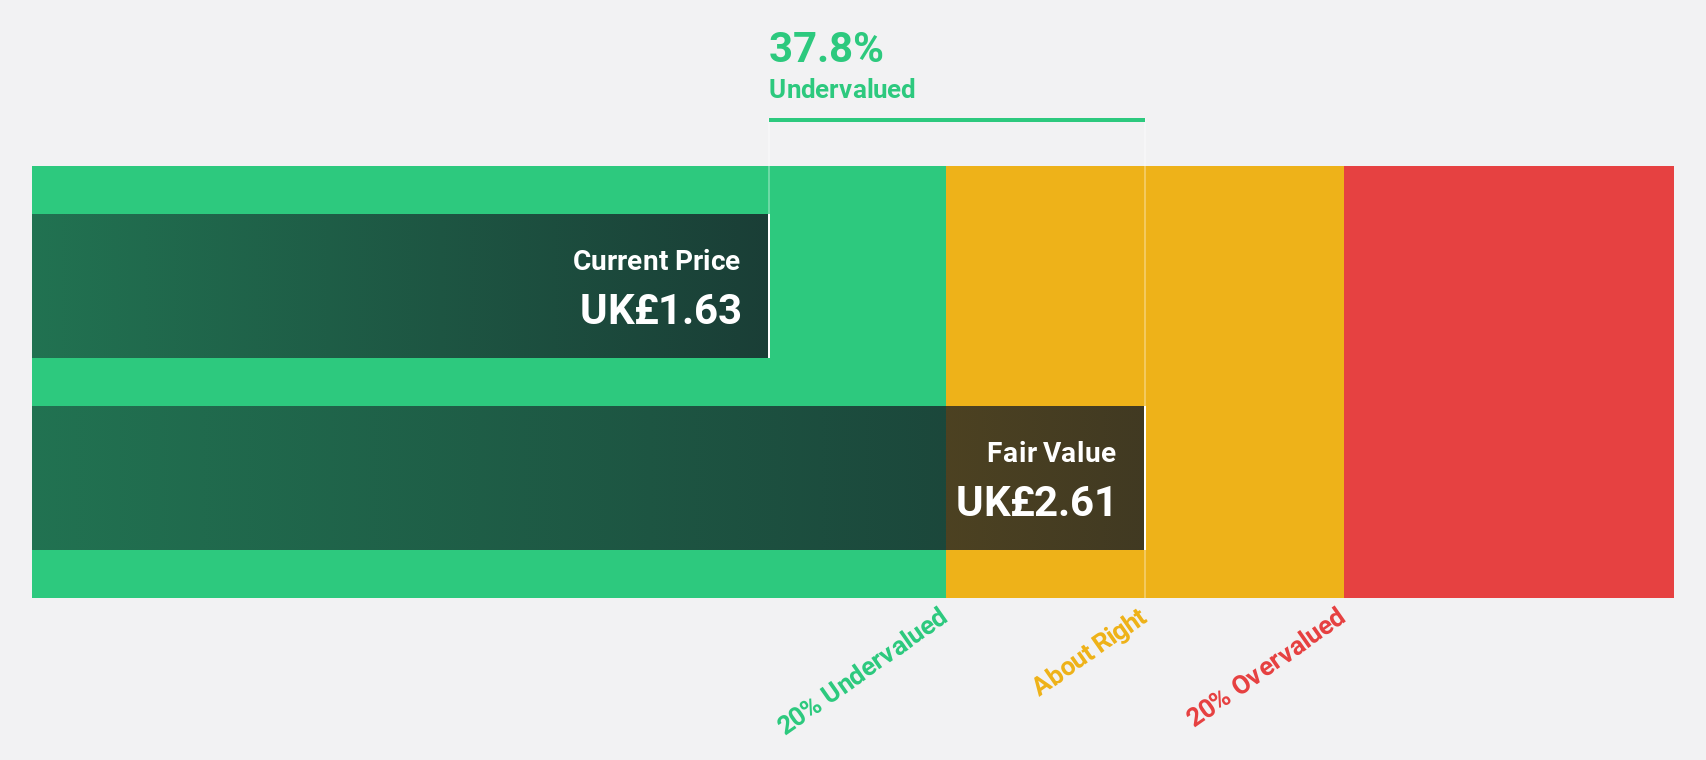
Estimated Discount To Fair Value: 27.1%
CAB Payments Holdings appears undervalued, trading 27.1% below its fair value estimate and more than 20% below future cash flow value. Despite a recent drop from the S&P Global BMI Index, it reported strong earnings growth with net income rising to £9.49 million for H1 2026. Revenue is forecast to grow significantly at 20.4% annually, outpacing the UK market's growth rate of 3.6%. However, insider selling has been significant recently.
- Our earnings growth report unveils the potential for significant increases in CAB Payments Holdings' future results.
- Unlock comprehensive insights into our analysis of CAB Payments Holdings stock in this financial health report.
LSL Property Services (LSE:LSL)
Overview: LSL Property Services plc, with a market cap of £252.69 million, operates as a business-to-business platform offering residential market services in the United Kingdom through its subsidiaries.
Operations: The company's revenue is derived from Financial Services (£48.19 million), Surveying and Valuation (£110.70 million), and Estate Agency excluding Financial Services (£26.70 million).
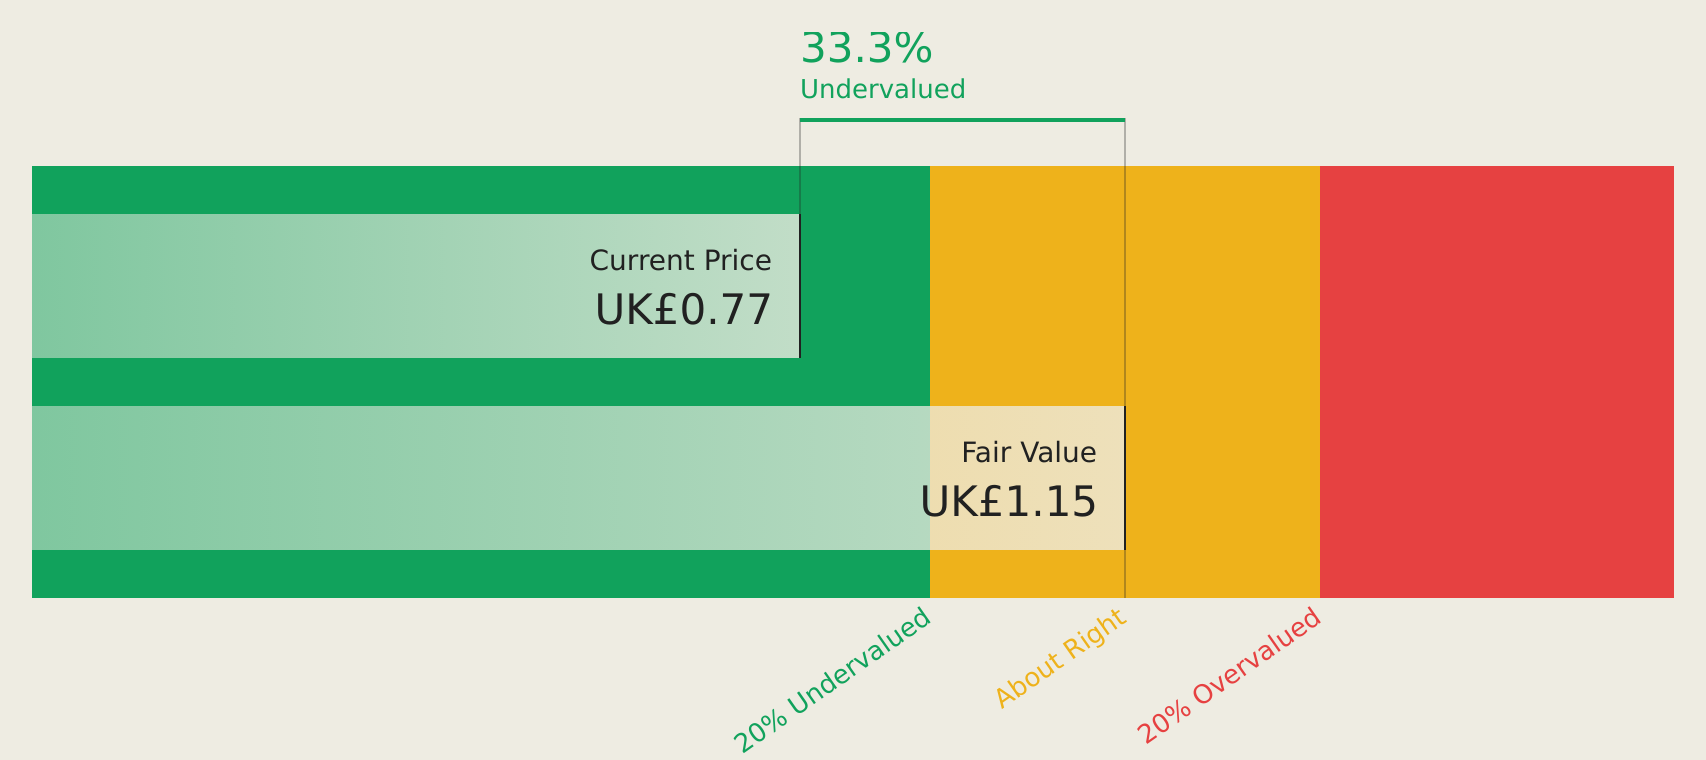
Estimated Discount To Fair Value: 43.6%
LSL Property Services is trading at a significant discount, with its stock price 43.6% below fair value estimates and more than 20% under future cash flow valuations. The company reported H1 2026 sales of £92.31 million, showing modest growth from the previous year. While revenue growth is slower than the UK market average, earnings are projected to grow faster at 11.9% annually. A recent dividend affirmation supports investor confidence despite an unstable dividend history.
- According our earnings growth report, there's an indication that LSL Property Services might be ready to expand.
- Click to explore a detailed breakdown of our findings in LSL Property Services' balance sheet health report.
Stelrad Group (LSE:SRAD)
Overview: Stelrad Group PLC manufactures and distributes radiators across the United Kingdom, Ireland, Europe, Turkey, and internationally with a market cap of £188.48 million.
Operations: The company's revenue from the manufacture and distribution of radiators amounts to £267.13 million.
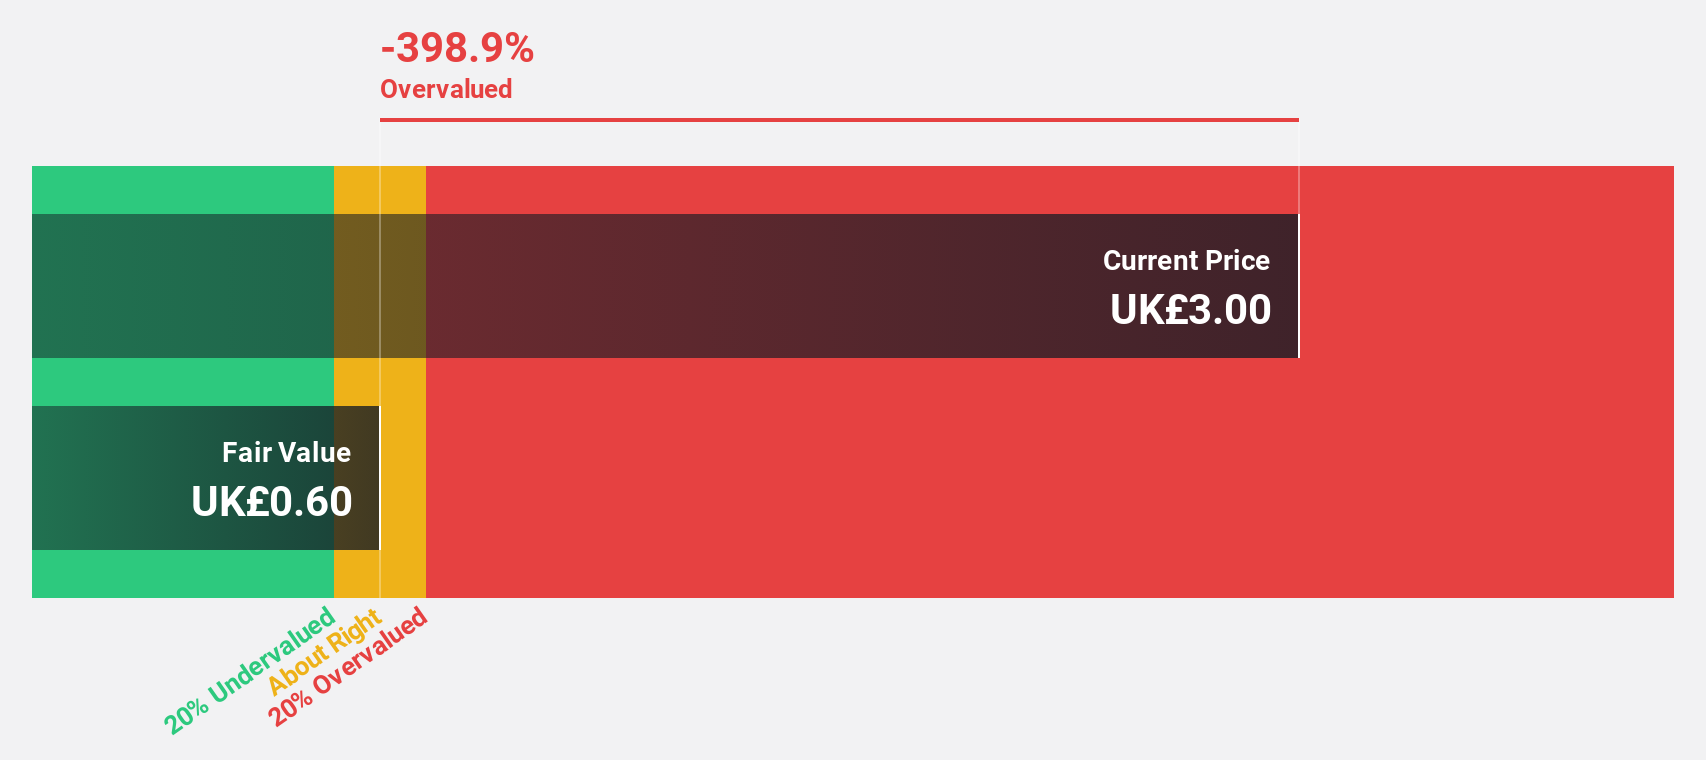
Estimated Discount To Fair Value: 40.6%
Stelrad Group's stock is trading 40.6% below its fair value estimate, with a market price of £1.48 compared to a future cash flow valuation of £2.49, indicating significant undervaluation. Despite high debt levels and recent insider selling, the company reported strong earnings growth for H1 2026 with net income reaching £8.66 million from a previous loss. Earnings are forecast to grow at 16.7% annually, outpacing the UK market average growth rate of 11%.
- The growth report we've compiled suggests that Stelrad Group's future prospects could be on the up.
- Click here to discover the nuances of Stelrad Group with our detailed financial health report.
Taking Advantage
- Delve into our full catalog of 31 Undervalued UK Stocks Based On Cash Flows here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com