


EN
Is Clean Harbors (CLH) Fully Valued After Its Strong Run?
Clean Harbors (CLH) has moved quietly higher, with the share price at $318.76 and a year-to-date total return of 30.9%. That kind of run naturally raises fresh questions about valuation.
Recent trading has been more muted, with the share price slipping 0.69% over the last day and posting a 4.97% 90-day share price return. However, Clean Harbors still carries strong longer term momentum with a 175.53% 5-year total shareholder return that keeps valuation firmly in focus.
Scan how Clean Harbors compares with other quietly compounding operators by reviewing our hand picked 21 high quality undiscovered gems, which share strong fundamentals and under the radar momentum.
Clean Harbors now trades near analyst targets after a strong multi year run. The real tension sits between further upside from here and the risk that most of the easy gains have already passed.
Most Popular Narrative: 8.9% Undervalued
Against the recent close at $318.76, the most followed narrative pegs Clean Harbors' fair value at $350. This view treats the current price as a discount to a resilient environmental infrastructure business with several ways to compound over time.
The story is not simply that Clean Harbors cleans up hazardous waste.
The deeper investment thesis is:
Modern society keeps producing hazardous waste, and somebody has to safely collect it, transport it, treat it and dispose of it. Clean Harbors owns one of the most difficult-to-replicate infrastructure networks required to do that.
That provides the basis for a long-term compounder narrative.
See why 2 investors see Clean Harbors as 9% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors story can be knocked off course if industrial activity weakens materially or if new regulations change how hazardous waste must be handled.
Find out about the key risks to this Clean Harbors narrative.
Another View: Clean Harbors Looks Pricey On P/E
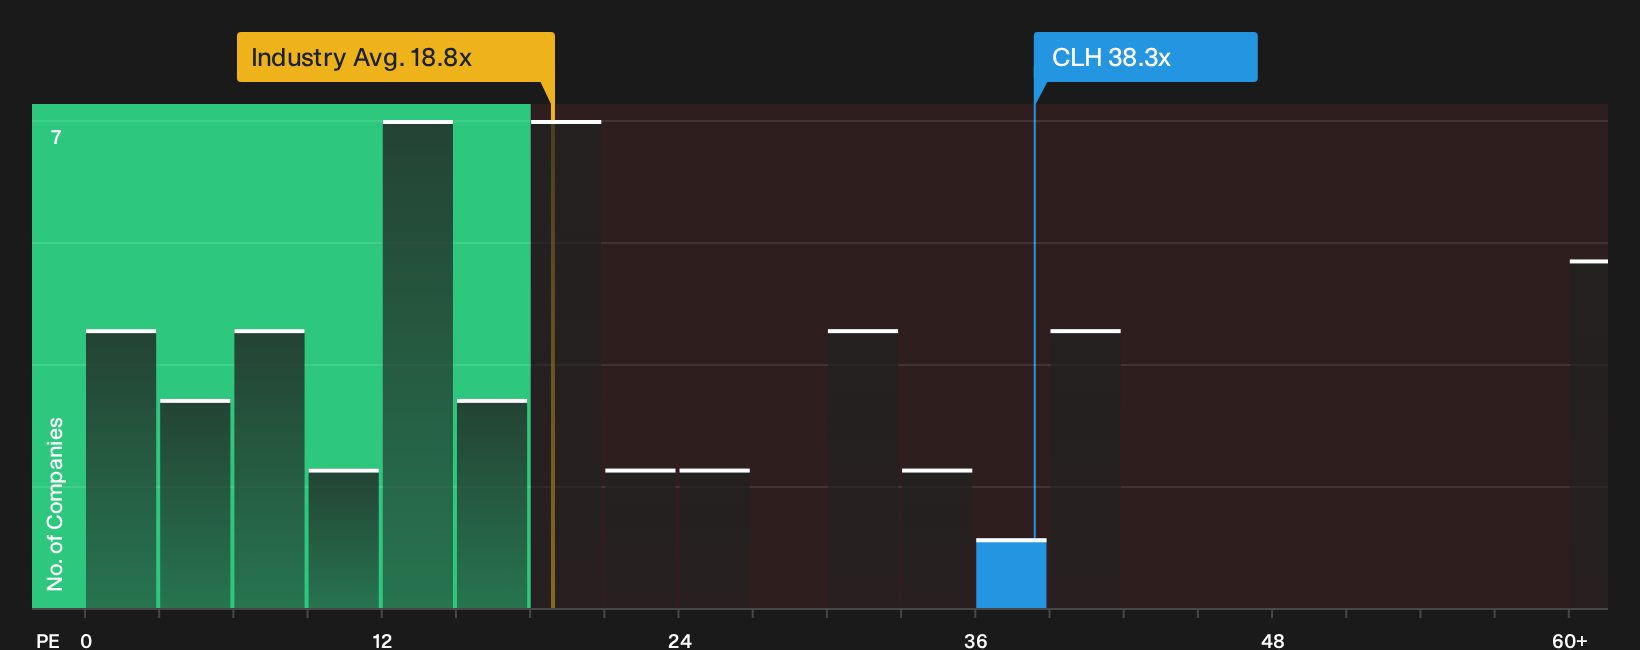
Where the most popular Clean Harbors narrative leans on a long term infrastructure story, the P/E math tells a different story. The stock trades at 38.3x earnings, compared with 30.1x for peers and 18.8x for the broader US Commercial Services group. Our fair ratio sits at 21.3x, which leaves investors paying a rich premium and taking on valuation risk if sentiment cools.
To see what the numbers say if that P/E gap narrows over time, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer visual on how this premium compares with the rest of the sector, review the
Next Steps
Mixed signals on Clean Harbors so far. For a clearer view, move quickly and test the story against the data yourself by weighing its 3 key rewards and 2 important warning signs.
Looking for more Clean Harbors sized opportunities?
If you stop at Clean Harbors, you risk missing other ideas that fit your style, so put the Simply Wall Street Screener to work for you today.
- Target value and quality together by reviewing our 29 high quality undervalued stocks, which combines strong fundamentals with potentially attractive pricing.
- Strengthen your defensive side by scanning the list of solid balance sheet and fundamentals (24 results), which highlights companies with sturdier financial foundations.
- Dial down portfolio stress by assessing the 30 resilient stocks with low risk scores, which spotlights businesses with lower risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com